



Having €10,000 saved up is a great starting point, but leaving it in a bank account with minimal returns can be a missed opportunity.
The question then arises: where is the best place to invest €10,000 in Ireland? What investment options are available to retail investors, what do they cost in tax, and what risks should you be aware of with each choice?
In this article, I’ll explore investment options for your €10,000, ranging from low-risk to high-risk opportunities. Here are some of the examples we will cover:
- Earn interest on your cash through online brokers and banks
- Invest in bond ETFs
- Invest in an ETF tracking the S&P 500
- Invest in Vanguard LifeStrategy funds
I also explain how each option is taxed in Ireland, including the changes announced in Budget 2027, which matter more here than in most European countries.
1. Low-risk options: interest on your cash
Irish banks still pay very little on deposits, but several brokers pay interest on uninvested cash at rates close to (or above) the European Central Bank’s deposit facility rate, which has stood at 2.50% since 16 September 2026. You can check our list of brokers paying interest on cash, but here we focus on two:
Trade Republic
Trade Republic pays interest on uninvested cash. Its Irish website currently advertises 3% AER (annual equivalent rate) on balances up to €50,000, paid out monthly. Cash above that limit earns no interest, and the rate can change, so check the current conditions on Trade Republic’s interest page before opening an account.
Trade Republic spreads client cash across partner banks, such as Deutsche Bank, HSBC and J.P. Morgan, where deposits are protected up to €100,000 per partner bank. Part of client money is also placed in money market funds (MMFs), which invest in short-term debt. MMFs are investments, not deposits, so deposit guarantee schemes don’t apply to them.
For more information, check our article on Trade Republic interest.
Trading 212
Trading 212 also pays interest on uninvested cash, on any balance. Rates are variable and depend on the currency and on the Trading 212 entity that holds your account, so check the live rate on its terms and fees page. The same account lets you buy ETFs with no commission (other fees may apply, see terms and fees), which makes it easy to move part of your €10,000 into the funds covered below.
Trading 212 uses a combination of qualifying money market funds (QMMFs), time deposits and current accounts to provide the rates shown on its platform. QMMFs invest in low-risk, short-term debt securities and aim to keep a stable price, but they are investments rather than deposits.
Your funds and assets are covered by the investor compensation scheme that applies to the Trading 212 entity holding your account. For its EU entities, this pays 90% of an eligible claim, up to €20,000.
For more information, check our article on Trading 212 interest, and see our Trading 212 promo code guide for the current welcome offer.
Disclaimer: When investing, your capital is at risk and you may get back less than invested. Past performance doesn’t guarantee future results. If you enable interest, Trading 212 will hold your cash in qualifying money market funds and banks. Otherwise, your cash will be held only in banks. Interest applies on cash in an investment account. Terms apply. Other fees may apply. See terms and fees. Trading 212 Markets Ltd. is registered in Cyprus (Company number HE 409763). Trading 212 Markets Ltd. Authorised and regulated by the Cyprus Securities and Exchange Commission (Licence number 398/21).
*Sponsored Link: To get a free fractional share worth up to €100, you can open an account with Trading 212 through our sponsored link or with the promo code “IITW”. The value is random: there is an 80% chance it is worth €8 to €25, 15% for €25.01 to €50, 3% for €50.01 to €75 and 2% for €75.01 to €100. Terms apply.
2. Low to intermediate-risk investment
Going up the risk scale, you can consider bond ETFs.
Bonds are loans to governments or companies. In exchange, investors receive interest for the money they lend. The loan runs for a set number of years and, if all goes well, you get your capital back at the end, plus the interest earned along the way.
Bond ETFs package many bonds into a single product. Instead of buying one government bond, you buy a fund that holds dozens or hundreds of them (Germany, France, Italy and so on).
There are four characteristics to look at in any bond ETF:
- Credit rating: how likely you are to get your money back. The higher the rating, the less likely the issuers are to default. Government bond ETFs usually have higher ratings than corporate ones.
- Yield to maturity (YTM): the average yield of all the bonds in the ETF, assuming they are held until maturity. Factsheets often show the yield to worst instead, which assumes the least favourable repayment date for the investor.
- Duration: how sensitive the ETF is to interest rates. A duration of 5 means that, for every 1 percentage point rise in rates, the ETF loses roughly 5% in value, and gains about the same if rates fall.
- Annual cost (TER): the cost of running the fund. A TER of 0.10% means €10,000 invested costs €10 a year.
Two examples of bond ETFs are the iShares Core € Govt Bond UCITS ETF (ISIN IE00B4WXJJ64), which tracks eurozone investment-grade government bonds, and the iShares Core € Corp Bond UCITS ETF (ISIN IE00B3F81R35), which tracks euro-denominated investment-grade corporate bonds. These are the key figures from their factsheets:
| ETF | iShares Core € Govt Bond | iShares Core € Corp Bond |
| Type of bonds | Eurozone government | Euro corporate |
| Yield to worst | 3.94% | 4.26% |
| Effective duration | 6.68 years | 4.37 years |
| TER | 0.07% | 0.09% |
| Fund size | €6.06 billion | €13.33 billion |
| Number of bonds | 552 | 4,214 |
Source: iShares Core € Govt Bond factsheet and iShares Core € Corp Bond factsheet, end of September 2026.
The government bond ETF’s largest positions are French, Italian, German and Spanish government bonds, and Ireland is among its 10 largest issuers, at about 1.37% of the fund:
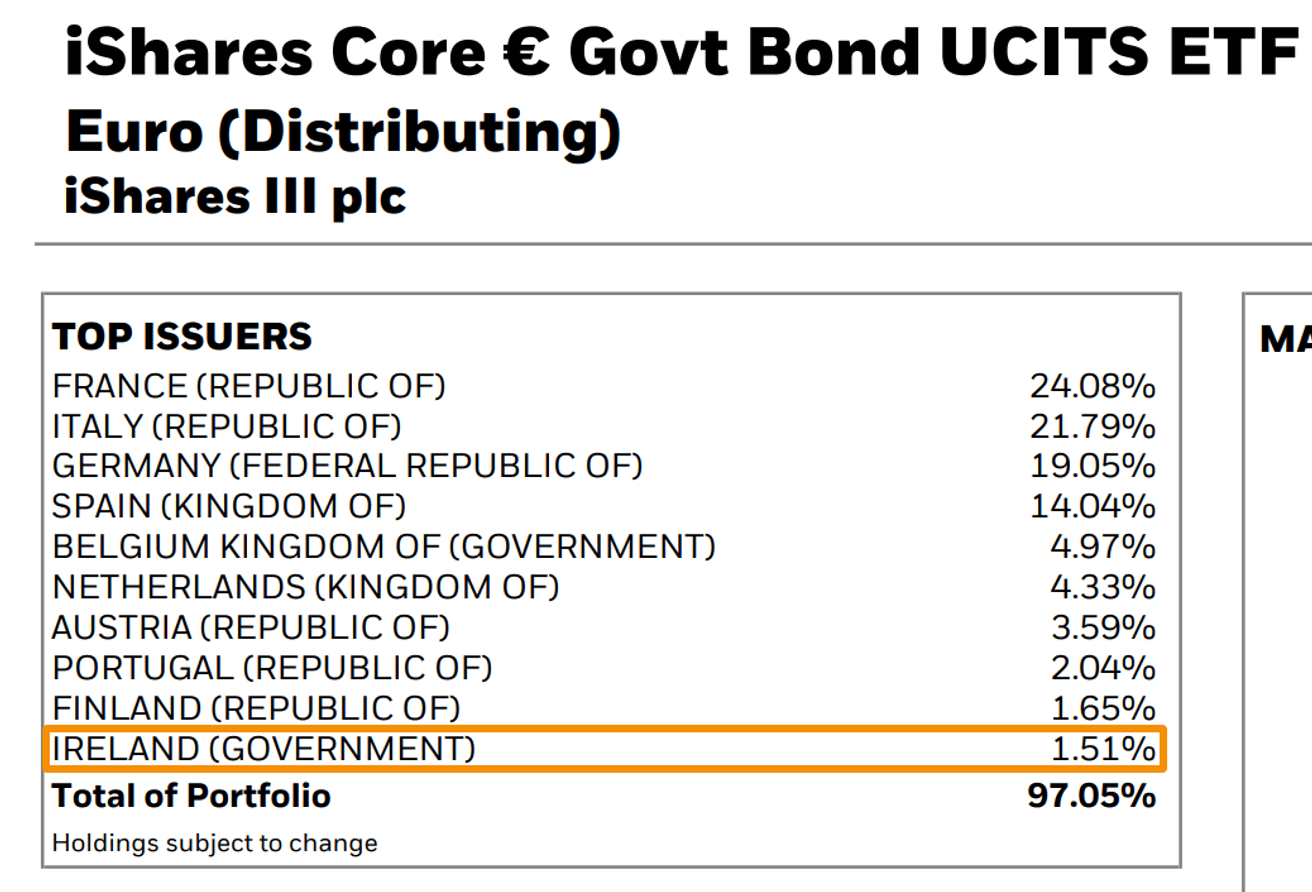
Yields, durations and ratings change with the market, so check the current factsheet before investing. Note that the corporate bond ETF pays a higher yield than the government one, but carries more credit risk, as companies are more likely to default than eurozone governments. Its index includes bonds rated down to BBB, the lowest investment-grade band. The government ETF has a longer duration, so it is more sensitive to changes in interest rates.
3. Intermediate to high-risk investments
Invest in an ETF tracking the S&P 500
The S&P 500 is a US index made up of around 500 of the largest US-listed companies. You can invest in it through an ETF and, for a low annual fee (often 0.03% to 0.10%), get exposure to a diversified basket of shares.
Our article on how to invest in the S&P 500 from Ireland covers the details, and you can also watch our video:

Invest in one of Vanguard’s LifeStrategy funds
Vanguard’s LifeStrategy range holds a mix of shares and bonds in a single ETF, rebalanced automatically. You pick the one that matches your risk tolerance and hold it, without choosing individual funds yourself.
These are the LifeStrategy ETFs available to European investors:
- Vanguard LifeStrategy 20% Equity UCITS ETF
- Vanguard LifeStrategy 40% Equity UCITS ETF
- Vanguard LifeStrategy 60% Equity UCITS ETF
- Vanguard LifeStrategy 80% Equity UCITS ETF
As the names imply, each holds between 20% and 80% in shares, with the rest in government and corporate bonds from developed and emerging markets. They are Irish-domiciled, come in accumulating and distributing versions, and have an ongoing charge of 0.25% a year.
To invest in an S&P 500 ETF or a LifeStrategy fund, you need to open an account with a broker. Compare fees, minimum deposits, security and whether the assets you want are available.
How your €10,000 is taxed in Ireland
Ireland taxes investments by wrapper, not by asset, and the differences are large. This often matters more than the fees you pay. Budget 2027, announced on 6 October 2026, changed several of these rates:
- Deposit interest: interest from bank deposits is subject to DIRT (Deposit Interest Retention Tax) at 33%. Interest paid by foreign institutions, such as a German broker, isn’t taxed at source, so you have to declare it in your tax return. It is taxed at the DIRT rate if you return it on time.
- ETFs and funds: gains and distributions from Irish and EU-domiciled ETFs (including S&P 500 ETFs, bond ETFs and LifeStrategy funds) are subject to exit tax. Budget 2026 cut this rate from 41% to 38% from 1 January 2026, and Budget 2027 cuts it again to 35%, expected from 1 January 2027 once Finance Bill 2026 is passed.
- The eight-year rule: ETFs are subject to deemed disposal. Every eight years, Revenue treats your fund as if you had sold it and taxes the gain on paper, even if you haven’t sold. The tax paid is credited against the tax due when you eventually sell. Budget 2027 kept this rule for ordinary accounts.
- No exemption or loss relief on funds: unlike shares, ETF gains don’t benefit from the €1,270 annual CGT (capital gains tax) exemption, and losses on one fund can’t offset gains on another.
- Individual shares: taxed under CGT, which Budget 2027 cut from 33% to 31% for disposals from 7 October 2026. The first €1,270 of gains is exempt each year, and losses can be offset.
| Option | Tax | Rate | €1,270 exemption | Deemed disposal |
| Cash interest | DIRT | 33% | No | No |
| ETFs and funds | Exit tax | 38% (35% from 2027) | No | Yes, every 8 years |
| Individual shares | CGT | 31% | Yes | No |
Source: Revenue and Budget 2027 tax policy changes.
Worked example: €10,000 over eight years
To see how much the wrapper matters, assume your €10,000 grows to €14,000 over eight years, a €4,000 gain, and that you are in 2027 or later:
- In an ETF: at the eighth anniversary, deemed disposal applies. Exit tax of 35% on €4,000 is €1,400, due even if you don’t sell.
- In individual shares (sold that year): CGT of 31% on €2,730 (€4,000 minus the €1,270 exemption) is about €846.
- In cash: €10,000 earning 3% for one year pays €300 of interest. DIRT of 33% takes €99, leaving €201.
These are simplified illustrations that ignore fees, distributions and changes in rates, and are not indicative of future returns. They show why many Irish investors diarise the anniversary of each ETF purchase and plan for the tax bill.
The new Investment Account
Until now, pensions were the main tax-advantaged wrapper in Ireland, as there was no equivalent to the UK ISA (Individual Savings Account). Budget 2027 announced a new Investment Account, due to start on 1 July 2027. According to the government’s budget documents, you will be able to contribute up to €12,000 a year, and instead of CGT, exit tax and deemed disposal, the account will pay a flat 1% annual tax on its value above €50,000. The details still depend on the Finance Bill, so we will update this article when the account launches.
This is general information, not tax advice. Rules change, so check the current position with Revenue or a tax adviser.
Common mistakes in investing
Investing is not only about choosing the right assets, but also about avoiding the mistakes that derail your plan.
Emotional trading
Emotional trading means making decisions based on how you feel rather than on analysis. Here’s how to avoid it:
- Understand market cycles: markets go up and down. Emotional investors panic in downturns and sell, missing the recovery.
- Stick to your plan: set your strategy in advance and follow it, including when to buy and sell.
- Be patient: investing is a long-term game, so resist impulsive decisions based on short-term moves.
- Avoid the herd: just because everyone is buying or selling doesn’t mean you should.
Chasing returns
Chasing returns means buying whatever has performed well recently, without considering the risks. This often means buying high and selling low:
- Diversify: spread your money across asset classes or use broad instruments, such as an S&P 500 ETF or a LifeStrategy fund.
- Take a long-term view: past performance does not guarantee future results.
- Be sceptical of hype: be wary of investments heavily promoted by the media or online communities.
FAQ
Is €10,000 enough to start investing in Ireland?
Yes. Most online brokers have low or no minimum deposits, and ETFs let you diversify across hundreds of companies or bonds with a single purchase. It is usually sensible to keep an emergency fund in cash before investing the rest.
How is interest from a foreign broker taxed in Ireland?
Interest paid by a broker or bank based outside Ireland is not taxed at source. You must declare it in your tax return, and it is taxed at the DIRT rate of 33% if you return it on time.
When does the exit tax drop to 35%?
Budget 2027 cuts the exit tax from 38% to 35%. The change is expected to apply from 1 January 2027, subject to Finance Bill 2026.
Bottom line
The list of options doesn’t end here. You could also look at non-traditional investments, such as luxury watches or peer-to-peer lending. In our experience, they are rarely worth it for most people, as they tend to be opaque and illiquid.
For most retail investors, building a diversified portfolio of cash, bonds and equities is a more sensible approach than trying to beat the market with individual stock picks. In Ireland, it is also worth checking how each option is taxed before you commit your €10,000, since the exit tax and the eight-year rule can affect your net return more than a few basis points of fees. If you can wait until mid-2027, the new Investment Account may also change which wrapper makes most sense for you.
For further reading, explore our book recommendations and courses, and feel free to contact us if you have questions or feedback.
Disclaimer: This information does not constitute financial advice or a recommendation and should not be considered as such. The author of this article is not a financial adviser and is therefore not authorised to offer financial advice.







