



Got €100,000 sitting in your bank account and wondering what to do with it? You’re not alone. It’s a great position to be in, but leaving that much cash idle is a missed opportunity, particularly as inflation has eroded the purchasing power of uninvested savings over the past few years.
The question is: where’s the best place to invest €100,000 in Ireland in 2026? What options are available, what are the risks and returns at each level, and what should you watch out for, particularly given Ireland’s specific tax framework around investments?
Let’s explore investment strategies tailored to the Irish market, ranging from low-risk to higher-risk opportunities. First, a quick look at Ireland’s tax framework, which Budget 2027 changed in October 2026:
| Tax | Rate | What it applies to |
| DIRT (Deposit Interest Retention Tax) | 33% | Interest on deposits. Interest from foreign accounts is taxed at the same rate through your tax return |
| CGT (Capital Gains Tax) | 31% (33% before 7 October 2026) | Gains on shares, investment trusts and bonds, above the €1,270 annual exemption |
| Exit tax | 38% in 2026, 35% from 1 January 2027 | Gains on Irish and EU-domiciled funds, including UCITS ETFs, with deemed disposal every 8 years |
| Income tax on dividends | Your marginal rate (up to 52% with USC and PRSI) | Dividends from shares and investment trusts |
Irish tax rates for investors, October 2026. Sources: The Irish Times and Goodbody on Budget 2027.
The exit tax plus deemed disposal still make ETF investing less attractive in Ireland than in most other EU countries, even after the cut to 35%. That is why we also look at investment trusts (taxed under CGT instead) alongside the traditional ETF route.
A new option from July 2027: Budget 2027 announced a new Investment Account. You will be able to put in up to €12,000 a year in shares, bonds and funds, with no tax on the first €50,000 of account value, a flat 1% a year on the value above that, and no deemed disposal. Providers are expected to launch it on 1 July 2027, and the details will follow in the Finance Bill. If you plan to invest gradually, it is worth keeping part of your €100,000 in mind for it.
1. Risk-free to low-risk investments
If your money is just sitting in the bank, you’re probably earning very little interest. Did you know you could earn up to 3% on euro cash balances through certain brokers in October 2026? You can check our list of brokers paying interest on cash. Here, we’ll focus on two options that stand out for Irish investors:
Trade Republic: risk-free option
Trade Republic pays interest on unlimited cash balances at the ECB deposit facility rate, currently 2.50% a year on EUR balances. In some countries new clients get a promotional 3% on up to €50,000, so check the app for the rate on offer to you. Importantly, only €100,000 per depositor is protected under the German deposit guarantee scheme, so for a full €100K position you’d be at the edge of coverage.
Note that Trade Republic’s interest rate is tied to ECB monetary policy. For example, when the ECB raised its deposit rate from 2.25% to 2.50% on 10 September 2026, Trade Republic’s rate rose to 2.50% from 16 September, when the new rate took effect.
Trade Republic now uses a mix of traditional deposit accounts and money market funds (MMFs) to deliver these rates. MMFs are still low-risk but carry slightly more risk than pure deposit accounts, and they are not covered by the deposit guarantee. From an Irish tax perspective, Trade Republic does not withhold DIRT, so you declare the deposit interest in your tax return and pay tax at the DIRT rate of 33%. Returns from money market funds can fall under different rules, so check the tax treatment before committing large sums.
Want more details? Check our full article on Trade Republic’s interest rate.
Trading 212: low-risk option
Trading 212 is another option, offering interest on uninvested cash with no balance cap. The EUR rate is variable and moves with ECB rates, and you can check the current rate on Trading 212’s Terms and fees page.
Sponsored Link: To get a free fractional share worth up to €100, you can open an account with Trading 212 through our sponsored link or with the promo code “IITW”. The value is random: there is an 80% chance it is worth €8 to €25, 15% for €25.01 to €50, 3% for €50.01 to €75 and 2% for €75.01 to €100. Terms apply.
Trading 212 uses a mix of qualifying money market funds (QMMFs), time deposits, and current accounts to provide these rates. QMMFs invest in short-term government bonds and are designed to maintain stable share prices.
Irish clients are served by Trading 212 Markets Ltd, regulated by CySEC, so client funds and assets are covered by the Cyprus Investor Compensation Fund up to €20,000 if the broker fails. Tax treatment: you declare the interest in your Irish tax return, and returns from money market funds may be taxed differently from deposit interest.
When investing, your capital is at risk. If you enable interest, Trading 212 will hold your cash in qualifying money market funds and banks. Otherwise, your cash will be held only in banks. Interest applies on cash in an investment account. Terms apply.
When investing, your capital is at risk and you may get back less than invested. Past performance doesn’t guarantee future results.
For a deeper dive into Trading 212’s interest rates, check our detailed article on Trading 212’s interest on cash.
2. Low to intermediate-risk investments
Ready to take on a bit more risk? Bond ETFs might be the next step up, though Irish investors need to weigh the bond returns against Ireland’s exit tax on ETF gains (38% in 2026, 35% from 2027), which significantly affects net returns compared to other EU jurisdictions.
Bond ETFs
Bonds are essentially loans you make to governments or companies, in return for periodic interest payments. At the end of the term, you should receive your money back plus the interest earned along the way.
Bond ETFs bundle multiple bonds into a single product, making it easier to diversify across issuers. Instead of buying one specific government bond, a Government Bond ETF lets you hold dozens or hundreds of bonds in a single instrument.
Four key factors to weigh when choosing a bond ETF:
- Credit rating: indicates how likely you are to get your money back. Higher rating = lower default risk.
- Yield to Maturity (YTM): the average expected return across all bonds in the ETF’s portfolio if held until maturity.
- Duration: measures the ETF’s sensitivity to interest rate changes. A duration of 5 means a 1 percentage point interest rate rise could cause a drop of about 5% in the ETF’s value, and vice versa for rate cuts.
- Annual cost (TER): the ongoing cost of running the fund. A 0.10% TER means €100 per year on a €100,000 position.
Examples of bond ETFs available in Ireland:
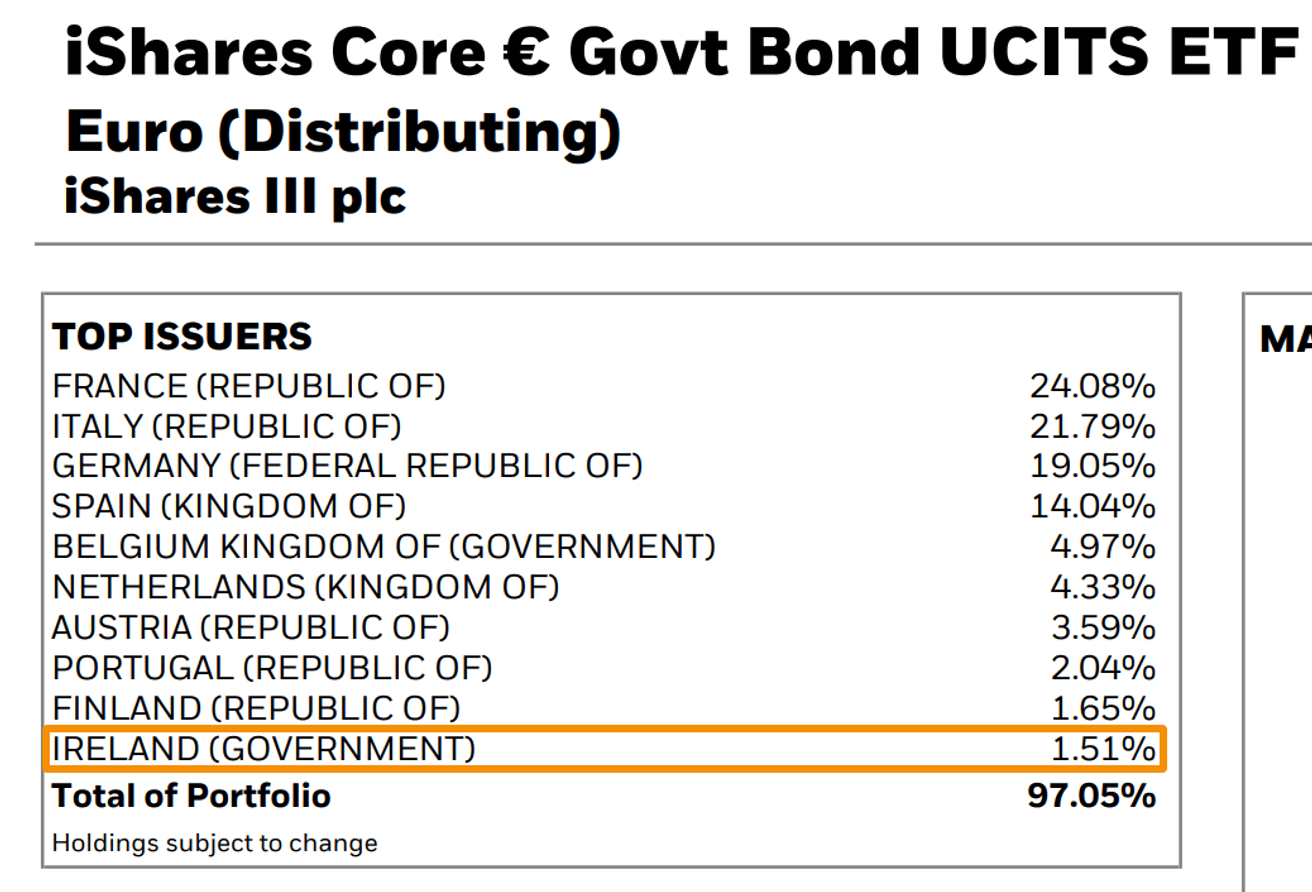
iShares Core € Govt Bond UCITS ETF (IEGA, ISIN IE00B4WXJJ64):
This ETF tracks an index of Eurozone investment-grade government bonds. Data as of 7 October 2026 (iShares product page):
- Credit rating: investment grade
- Yield to maturity: 3.90%
- Duration: 6.67 years
- TER: 0.07%
Top holdings include eurozone government bonds from France, Germany, Italy, Spain, the Netherlands, Belgium and Ireland.
Important Irish tax note: as a UCITS ETF, this product is subject to Ireland’s exit tax on gains (38% in 2026, 35% from 2027) rather than the 31% CGT, plus deemed disposal every 8 years. For long-term bond holdings, some Irish investors prefer holding individual government bonds directly (taxed under standard CGT/income tax rules), which can be more tax-efficient despite reduced diversification.
iShares Core € Corp Bond UCITS ETF (IEAC, ISIN IE00B3F81R35):
This ETF tracks an index of EUR-denominated investment-grade corporate bonds. Data as of 7 October 2026 (iShares product page):
- Credit rating: investment grade
- Yield to maturity: 4.21%
- Duration: 4.37 years
- TER: 0.09%
The same Irish tax considerations apply: exit tax on gains plus deemed disposal every 8 years.
3. Intermediate to high-risk investments
For investors willing to take on more risk in exchange for potentially higher long-term returns, equity ETFs and diversified multi-asset funds are typically the next step up.
Invest in an ETF tracking the S&P 500
The S&P 500 is the major US index covering 500 of the largest publicly traded US companies, representing approximately 80% of the US equity market capitalisation. Investing through an S&P 500 UCITS ETF is straightforward from Ireland, with TERs typically as low as 0.03% for the cheapest options. Strong options accessible to Irish investors include:
- SPYL (SPDR S&P 500 UCITS ETF): 0.03% TER, accumulating, the cheapest available.
- CSP1/CSPX (iShares Core S&P 500 UCITS ETF): 0.07% TER, accumulating.
- VUSA/VUAG (Vanguard S&P 500 UCITS ETF): 0.07% TER, distributing and accumulating versions.
- SPXP (Invesco S&P 500 UCITS ETF): 0.05% TER, synthetic, with the structural advantage of avoiding US dividend withholding tax (though counterparty risk applies).
Our guide on How to invest in the S&P 500 from Ireland has full details on getting started, including a breakdown of how Ireland’s exit tax and 8-year deemed disposal apply to these holdings.
Check our video for more details:

Invest in a Vanguard LifeStrategy fund
Vanguard LifeStrategy funds offer a one-stop diversified mix of stocks, bonds, and cash, automatically rebalanced over time. These funds let you pick an asset allocation that matches your risk tolerance and goals, all for a single low management fee. The Vanguard LifeStrategy UCITS ETF range available to Irish investors:
- Vanguard LifeStrategy 20% Equity UCITS ETF (conservative, bond-heavy)
- Vanguard LifeStrategy 40% Equity UCITS ETF (cautious balanced)
- Vanguard LifeStrategy 60% Equity UCITS ETF (balanced)
- Vanguard LifeStrategy 80% Equity UCITS ETF (growth-oriented)
Equity exposure ranges from 20% to 80%, with the remaining portion invested in global government and corporate bonds across developed and emerging markets. TER is typically around 0.25%, which is reasonable for a fully diversified one-stop multi-asset fund.
Investment trusts: a tax-efficient ETF alternative for Irish investors
Because of Ireland’s exit tax and 8-year deemed disposal regime on UCITS ETFs, many Irish investors consider investment trusts as a more tax-efficient alternative. Investment trusts are closed-end funds listed on stock exchanges, typically structured as UK companies, which means they are generally taxed under Ireland’s CGT framework (31%) rather than the exit tax regime, with no deemed disposal.
Popular UK-listed investment trusts accessible to Irish investors include:
- Scottish Mortgage Investment Trust (SMT): global growth focus.
- F&C Investment Trust (FCIT): global diversified.
- Alliance Witan (ALW): global multi-manager, formed by the merger of Alliance Trust and Witan in 2024.
These can offer comparable diversification to equity ETFs while benefiting from the CGT framework rather than the exit tax. Keep in mind that investment trusts can trade at a discount or premium to the value of their assets, and their fees are usually higher than an index ETF’s. Worth noting: dividends are still subject to Irish income tax at marginal rates. Always consult a qualified Irish tax advisor for guidance on your specific situation.
To invest in any of these instruments, you’ll need to open an account with a brokerage that serves Irish residents. Compare fees, minimum deposits, available exchanges (notably London Stock Exchange and Euronext Dublin/Amsterdam access), and regulatory protection before committing. Our broker comparison tool lets you fully compare multiple options.
Common investing mistakes to avoid
Investing isn’t just about picking the right assets. It’s also about avoiding the common pitfalls that derail long-term returns. Here are the most common mistakes to steer clear of:
Emotional trading
- Understand market cycles: markets rise and fall in cycles. Don’t panic-sell during downturns at depressed prices. History shows that staying invested through volatility typically rewards patient investors.
- Stick to your plan: have a well-thought-out written investment plan and stick to it, even when the market is volatile or news headlines feel scary.
- Patience is key: investing is a long-term game (decades, not months). Avoid making rash decisions based on short-term market moves.
- Don’t follow the herd: just because everyone else is buying (or selling) doesn’t mean you should. Base your decisions on your own research, risk tolerance, and strategy.
Chasing returns
Chasing the latest hot stock or sector can be tempting, but it’s one of the most reliable ways to buy high and sell low. Some safeguards:
- Diversify: spread your investments across multiple asset classes (stocks, bonds, cash) and geographies. A single S&P 500 ETF or a Vanguard LifeStrategy fund already provides meaningful diversification within a single instrument.
- Think long-term: don’t get distracted by short-term trends or fads. Past performance doesn’t guarantee future returns, and the most-hyped sectors of one decade are often the worst-performing of the next.
- Be wary of hype: remember the EV stock frenzy of 2020 to 2021, the meme-stock mania, the crypto ICOs of 2017? Hype-driven investments rarely deliver sustainable returns, so exercise scepticism around heavily-promoted assets.
Ignoring tax efficiency
Ireland’s specific tax framework makes tax planning unusually important. The exit tax and 8-year deemed disposal on UCITS ETFs can significantly erode long-term returns compared to alternatives. Consider:
- Using pension wrappers (PRSA, AVCs, occupational pension schemes) for tax-deferred or tax-relieved investments, one of the most tax-efficient ways for Irish residents to build long-term wealth.
- Considering investment trusts as a CGT-taxed alternative to ETFs where appropriate.
- Holding individual government bonds directly rather than bond ETFs for long-term fixed income exposure (also CGT-taxed).
- Using the annual CGT exemption of €1,270 when you rebalance.
- Planning for the new Investment Account from July 2027, with up to €12,000 a year and no deemed disposal.
Always consult a qualified Irish tax/financial advisor for guidance specific to your situation.
Best trading platforms in Ireland
If you’re ready to invest your €100,000 but want to compare the best brokers available to Irish residents, check our review of the best trading platforms in Ireland. We compare each platform in detail to help you make the right choice.
The bottom line
There are plenty of ways to invest €100,000 in Ireland, from risk-free cash accounts to higher-risk equity funds. The key is to diversify and align your investments with your specific goals, time horizon, and risk tolerance.
For most Irish retail investors, a sensible long-term approach combines:
- Cash for short-term needs and emergency fund: earning interest through Trade Republic, Trading 212 or similar.
- Pension contributions (PRSA, AVCs, occupational schemes): for tax-relieved long-term growth.
- A diversified equity allocation: through an S&P 500 UCITS ETF, a Vanguard LifeStrategy fund or investment trusts (mindful of Ireland’s exit tax on ETFs), and the new Investment Account once it launches.
- Bond exposure: through individual bonds (CGT-taxed) or bond ETFs (exit-tax-treated), depending on your tax preference.
It’s less about trying to beat the market and more about staying the course through market cycles, while being thoughtful about Ireland’s specific tax framework along the way.
For more resources, check our recommended books and courses. If you have any questions or feedback, feel free to reach out.
Disclaimer: This information does not constitute financial advice or recommendation and should not be considered as such. This article’s author is not a financial advisor and it is therefore not authorised to offer financial advice.







