Investing in the S&P 500 is a popular strategy for those looking to gain exposure to a broad spectrum of the US stock market. It is widely regarded as a barometer of the overall health of the US economy and a staple in many investors’ portfolios.
This article will guide you through the process of investing in the S&P 500 on Interactive Brokers (IBKR), covering the instruments to use and actually making your first investment. For more info, you can also read our full review on Interactive Brokers!
Pick an ETF tracking the S&P 500
It is impossible to directly buy the S&P 500 index. However, you can invest in it through an instrument replicating every movement, like an Exchange-Traded Fund (ETF).
The table below shows five S&P 500 ETFs available on IBKR. For the full universe available to European investors, which is not applicable to US residents and includes funds IBKR may not carry, see justETF. This shortlist is enough to choose from:
| Name | Annual cost | ISIN | Ticker* | Replication | Income | Fund size |
| State Street SPDR S&P 500 UCITS ETF (Acc) | 0.03% | IE000XZSV718 | SPYL | Physical | Accumulating | $18.8bn |
| Invesco S&P 500 UCITS ETF | 0.05% + 0.072% swap fee | IE00B3YCGJ38 | SPXS | Synthetic | Accumulating | $59.9bn |
| iShares Core S&P 500 UCITS ETF | 0.07% | IE00B5BMR087 | SXR8 | Physical | Accumulating | $156.1bn |
| Vanguard S&P 500 UCITS ETF | 0.07% | IE00B3XXRP09 | VUSA | Physical | Distributing | $53.4bn |
| Xtrackers S&P 500 Swap UCITS ETF | 0.15% | LU0490618542 | XSPX | Synthetic | Accumulating | €8.0bn |
*Tickers vary by listing venue. Each ETF above trades under several tickers across Xetra, Euronext, Borsa Italiana, SIX and the London Stock Exchange, and the one shown is not valid on every venue, so always search by International Securities Identification Number (ISIN) rather than by ticker on Interactive Brokers. Fund sizes are each provider’s own headline figure as at September 2026, in the currency that provider reports, and DWS reports the Xtrackers fund at whole-fund level rather than share class. TERs and fund sizes change over time, so verify current figures on the provider’s factsheet before investing.
All five track the same index, so the choice comes down to four things:
- Cost. The total expense ratio (TER) ranges from 0.03% to 0.15%. On €10,000 that is the difference between €3 and €15 a year. The 0.03% tier is recent: until a few years ago the cheapest S&P 500 ETFs charged 0.07%, and State Street, UBS, Amundi and Xtrackers have all since launched funds below that. Note that the Xtrackers fund in the table is the older swap version at 0.15%, not its 0.03% one;
- Scale. iShares is by far the largest at about $156 billion, followed by Invesco and Vanguard. A larger fund is less likely to be wound up, which would force you to realise a gain at a time you did not choose;
- What you want the dividends to do. Four of the five accumulate them inside the fund. Only Vanguard pays them out;
- How the fund tracks the index, physically or through a swap. The section on why the synthetic funds have run slightly ahead sets out how the two methods differ and what the returns have looked like.
If you want to explore more S&P 500 ETFs, go to the Interactive Brokers search bar and write “S&P 500”:

Please keep in mind that the same ETF can be traded in different exchanges and in different currencies. For example, the Vanguard S&P 500 UCITS ETF is traded on the Euronext Amsterdam (“AEB”), the London Stock Exchange (“LSEETF”), and the SIX Swiss Exchange:

The ETF traded on “AEB” is quoted in EUR, whereas the one traded on the “LSEETF” is quoted in GBP. This means that if you are a European-based investor, you should go for the EUR version. Why? Because you will not be charged unnecessary currency conversion fees. The same can be said for a UK-based investor by choosing the GBP version.
Place a “Buy Order”
So, let’s say you have decided to invest in iShares Core S&P 500 UCITS ETF (SXR8). The process would be the same for the other ETFs.
- Search for the chosen ETF. The screenshot uses the ticker, but the ISIN is the safer search, because it is unique across every listing venue:

- Select the ETF, and a new window will pop up. Now, press “Buy”:

- Trading window
A new window will appear on the right side of your screen with all the details you need to fulfil: the order type (limit price in this case) and the quantity (number of shares) you want to buy:

We recommend setting a limit price in the order type to make sure you will not invest more than expected. Let’s look at the image again. The screenshot was taken on an earlier date, so the price is not today’s. The ETF is shown trading at €543.02. If you set a limit order of €542.50, you are guaranteed to only invest that amount (if the ETF goes back to that price).
On the other hand, if you give a market order, the purchasing price can be higher than the €543.02. It will buy at the best possible price when you confirm your order.
- Click “Preview”: All the details will appear (including the costs), and you are ready to trade by selecting “Submit Buy Order”.

And that’s it! You are invested in the S&P 500!
All the fees when buying an S&P 500 ETF on IBKR
By purchasing an S&P 500 ETF, you will incur several fees. According to the IBKR European stock and ETF pricing page, these are the charges:
- Trading commission on the Tiered plan: 0.05% of the trade value. The minimum and maximum depend on the currency of the exchange, not on the country. On the euro venues, which include Euronext Amsterdam, Xetra and Borsa Italiana, it is a minimum of €1.25 and a maximum of €29. On the SIX Swiss Exchange it is CHF 1.50 and CHF 49. On the London Stock Exchange it is £1.00 with no maximum at all;
- Trading commission on the Fixed plan: also 0.05%, but with a minimum of €3.00 on the euro venues and, importantly, no maximum. Many retail accounts default to Fixed. On a small order Tiered is cheaper because of the lower minimum, and on a large order Tiered is cheaper because of the €29 cap, so it is worth checking which plan your account is on;
- Currency conversion: IBKR publishes this as “0.20 basis point * Trade Value” with a minimum of USD 2.00, which is 0.002%. In practice the minimum is what you pay, since 0.002% only reaches $2 on a $100,000 conversion;
- The automatic conversion markup: the 0.002% above applies when you place the currency trade yourself. If you simply buy an ETF in a currency you do not hold and let IBKR convert for you, IBKR states it “will typically add or subtract (at its discretion) 0.03% to the exchange rate”, and charges no commission on top. Which route costs less depends entirely on size, because of that USD 2.00 minimum. A manual currency (FX) order only becomes the cheaper option once the conversion is worth roughly $6,700. Below that, letting IBKR convert automatically costs less, and on a €1,000 purchase it is the difference between about €0.30 and about $2;
- What you do not pay: IBKR removed its monthly inactivity fee on 1 July 2021, and charges no custody fee and no account minimum. Real-time market data is an optional paid subscription, while delayed data is free.
One more point on order size. IBKR offers fractional dealing on European ETFs that are liquid and large enough, which puts a share costing several hundred euros within reach of a small contribution. The commission minimum still applies to fractional orders, so a €50 fractional buy on a euro venue costs €1.25, or 2.5% of what you invested. Fractional dealing helps you own the fund. It does not make a small order cheap.
What to look for in any ETF?
Not all ETFs are created equal. Different asset managers provide different ETFs tracking the same indices (like the S&P 500). The main differences are:
1. Fees (TER)
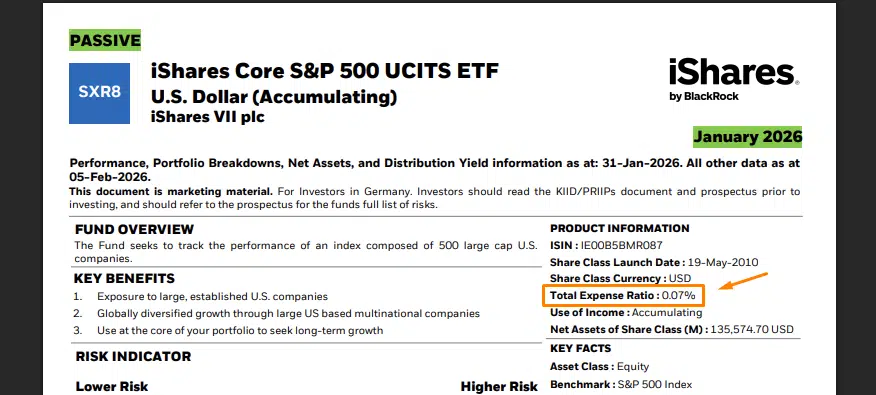
Asset managers like BlackRock (iShares) or Vanguard do not offer ETFs for free as they incur costs as well. Throughout the year, a small fee is subtracted from the fund’s assets. A lower fee will mean lower costs for you and, consequently, higher returns on our investments. Asset managers often list the overall cost of the fund. Ongoing charge (OCF) or total expense ratio (TER) are standard terms for this overall management fee.
Using the iShares Core S&P 500 UCITS ETF (SXR8) as an example, you can check its TER of 0.07% in the factsheet:
2. Replication method
It can be done in two ways:
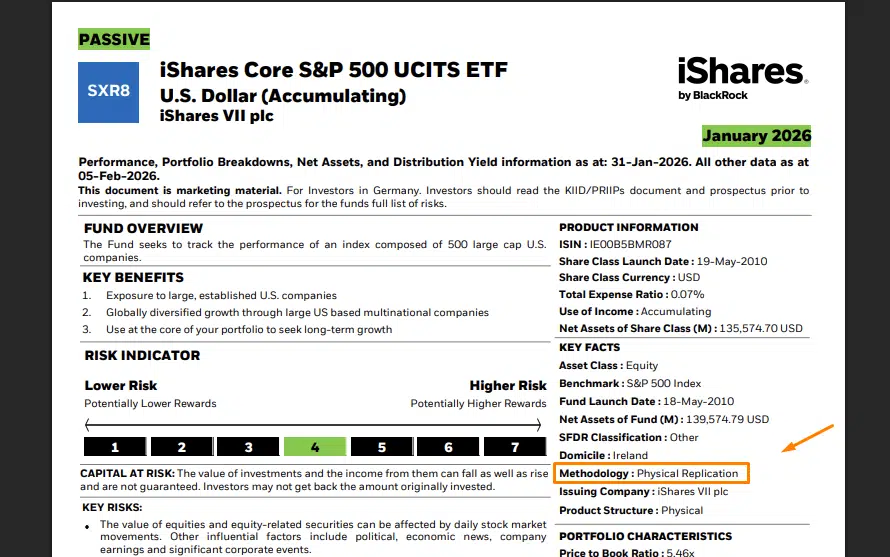
- Physical replication ETFs buy the underlying shares laid out in the index.
- Synthetic replication ETFs hold a substitute basket of shares and sign a swap with one or more banks, who pay the fund the index return in exchange for the basket’s return.
Using the same ETF, you can see its methodology as “Physical Replication”:
Why the synthetic S&P 500 ETFs have run slightly ahead
The usual description is that physical funds hold the shares and synthetic funds use derivatives. For the S&P 500 there is a tax mechanism underneath that, and it shows up in the returns.
The United States withholds tax on dividends paid to foreign funds. An Irish-domiciled fund that physically holds US shares pays 15% under the US and Ireland tax treaty, rather than the standard 30%. That treaty rate is the main reason almost every European S&P 500 ETF is domiciled in Ireland.
A swap-based fund does not hold the US shares, so it never receives those dividends. It receives a swap payment instead, and a swap referencing what US tax rules call a qualified index is not treated as referencing US shares, so its payments are not dividend equivalents and no US withholding arises on them under section 1.871-15(l) of the Treasury regulations. S&P Dow Jones Indices publishes the S&P 500’s figures against the seven criteria, and on its January 2026 data the index sits inside every threshold, including 503 constituents, long positions only, a largest single holding of 7.84% and a largest five of 27.58% combined. S&P states that it makes no representation or warranty as to whether any index is a qualified index, and publishes the data so that its licensees can make that determination themselves.
The practical effect is that a swap fund tracks the index before the withholding, while a physical Irish fund tracks it after paying 15%. That is a description of how the two structures are taxed today, not a forecast. Withholding treatment, swap pricing and fees can all change. Against the S&P 500 Net Total Return benchmark, which assumes the full 30%, here is what the providers themselves reported to 31 August 2026, annualised and in US dollars:
| ETF | 5 years a year | 3 years a year | Structure |
| Invesco S&P 500 | 12.69% | 20.93% | Synthetic |
| Xtrackers S&P 500 Swap | 12.60% | 20.82% | Synthetic |
| iShares Core S&P 500 | 12.49% | 20.73% | Physical |
| Vanguard S&P 500 | 12.48% | 20.73% | Physical |
| S&P 500 Net Total Return | 12.31% | 20.57% | Benchmark |
Returns to 31 August 2026 in USD, net of fees, from each provider’s own factsheet, against the S&P 500 Net Total Return index. The Invesco and Xtrackers figures are annualised from the cumulative and discrete-year returns those two providers publish. Past performance is not a guide to future returns.
The gap against the physical funds is about 0.2 percentage points a year for Invesco and about 0.1 for Xtrackers, whose higher 0.15% fee absorbs part of the advantage. Note also that Invesco charges a swap fee of 0.072% a year on top of its 0.05% TER, which its factsheet discloses separately from the TER.
The other side of the swap structure is who owes you the money. A physical fund owns the shares outright and may lend some of them out. A swap fund is owed the difference between two portfolios by a bank. UCITS rules cap that exposure at 10% of the fund’s assets where the counterparty is a bank and 5% otherwise, and the fund holds a real equity basket in the meantime. Invesco puts the consequence plainly: if a counterparty failed to pay what the swap owes, the fund “would instead rely on the performance of its portfolio of equities, which could be lower than the index performance”.
Both structures are widely used by large asset managers and both sit inside the same European fund rules, known as Undertakings for Collective Investment in Transferable Securities (UCITS). What differs is the mechanism, and over the last five years the measured difference has run between about a tenth and a fifth of a percentage point a year, depending on the fund.
3. Use of income
Apart from their product structure, the ETFs also distinguish themselves in the following ways:
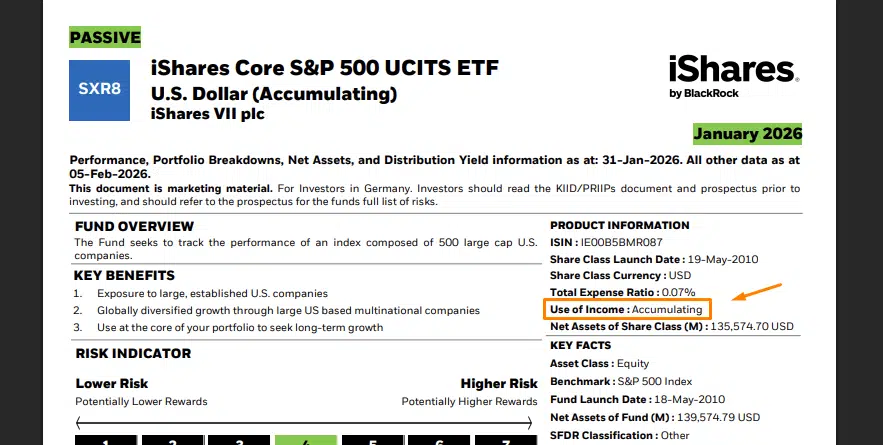
- Accumulating ETFs reinvest the dividends they receive from the companies in the index that choose to make such distributions. This will dictate a higher price for the ETF when compared to an identical distributing ETF, and, in some countries, it is tax advantageous because, since the dividends are kept inside the ETF, you are not required to declare that amount;
- Distributing ETFs gives you on a regular basis (usually quarterly) the dividends that companies distribute. So, you will receive that amount directly in your brokerage account. Here, you will have to declare the dividends received.
Which one is better? There is no “correct” answer. It all comes down to your preferences. Do you plan to withdraw your investment in a 20-year time horizon? Maybe an accumulating ETF does a better job. Do you want to earn some regular income? Well, in that case, a distributing ETF will be the most appropriate choice.
The SXR8 is “Accumulating”:
4. Size
The overall fund size should also be taken into consideration. The size of an ETF can impact the likelihood of fund liquidation. Smaller funds generally run a higher risk of being liquidated than larger funds. In such a case, the fund will sell all its holdings, settle obligations and distribute the remainder to the fund holders.
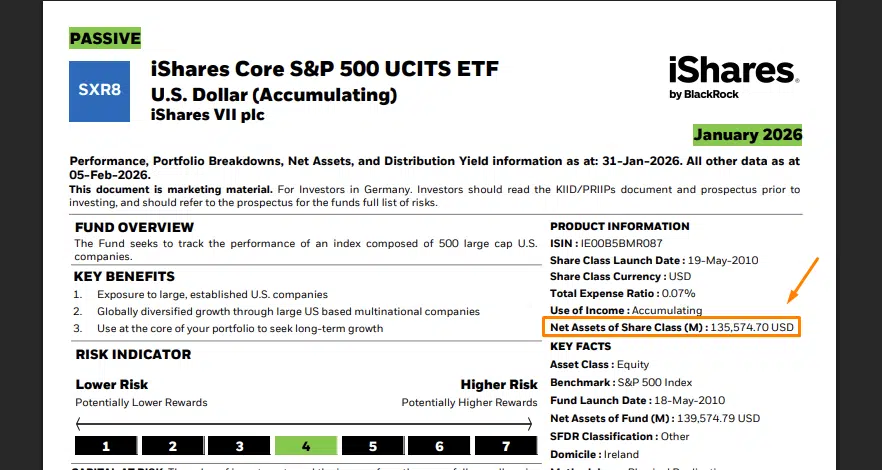
The SXR8 is the largest S&P 500 ETF in Europe. The figure to look for on the factsheet is the fund’s net assets, which is the size of the whole share class and not the value of a single share. The screenshot below shows where it appears on an earlier factsheet, so the number in it is not the current one:
5. Hedging
ETFs can use financial derivatives to protect against currency fluctuations. This comes at an additional cost but might protect you against large currency swings. The five ETFs above are all “unhedged”. Hedging adds a running cost that is certain, while the benefit depends on how currencies move over your holding period, which is why many long-term investors in broad equity funds leave the currency exposure in place.
Bottom line
To sum it up, here’s what you need to do:
-
Pick an ETF tracking the S&P 500: compare them on fee, size, whether they accumulate or distribute the dividends, and how they replicate the index.
-
Open an account and deposit money into Interactive Brokers: After deciding which trading platform to use, you must go through the account opening process and deposit money.
-
Send a buy order for the picked ETF: That’s the easiest part (the process is intuitive)! After having your brokerage account and the name of the ETF that you want to buy, you just have to place a trade!
-
Check two settings before you trade: whether your account is on the Tiered or the Fixed commission plan, and how your euros will be turned into the ETF’s currency. Use a limit order so you know the most you will pay.
We hope that this post addressed some of your concerns. Make sure to do your own research to find out the best investing strategy for you!
Other resources
- Check our Youtube channel! You will find step-by-step guides of how to invest in the S&P 500 on different brokers, as well as other educational videos about investing and investment platforms.
- Explore our tools: Check our comparison tool, reviews, BrokerMatch, and others.
- Check other trading platforms: compare this platform with others and decide which one suits best your investment needs. You can check, on our website, how to invest in the S&P 500 on Trading 212, on eToro or on Trade Republic
FAQs
What is the S&P 500?
The S&P 500 is an index tracking the leading 500 companies in the United States. It is weighted by each company’s free-float market value, so the largest companies move the index most. The index includes large well known companies such as Apple, Amazon, and Microsoft.
What is an Exchange Traded Fund (ETF)?
An ETF is a publicly traded fund that holds assets like stocks. When you invest in an ETF, you indirectly buy a large portfolio of assets. In the case of an S&P 500 ETF that means it will track the performance of underlying holdings used in the index. That would mean you can easily gain exposure to over 500 different companies with just a single investment!
Is it possible to invest directly in the S&P 500?
No, an index is a measure of the performance of a theoretical portfolio, meaning that it is just a representation. It thus is impossible to directly buy an index.
What are CFDs? Should I invest in S&P 500 CFDs?
CFD stands for contract for difference and allows investors to bet on price movements (either up or down), oftentimes with ample leverage. It is not recommended for novice investors to trade complex financial products. More about it here.
Can Europeans invest in SPY or VOO?
No. US-domiciled ETFs such as SPY and VOO do not publish the key information document that the Packaged Retail and Insurance-based Investment Products (PRIIPs) rules require, so European brokers cannot offer them to retail investors. The UCITS ETFs listed in this article are the European equivalents, and several of them track exactly the same index.
Is now a good time to invest in the S&P 500 in Europe?
Nobody can predict short-term market movements. Over long periods the S&P 500 has risen, but past performance is not a guide to future returns, and the index has had multi-year falls along the way.
Why should I invest in the S&P 500 index from Europe?
The S&P 500 has historically performed significantly better than the main European indices. An investor who expects that gap to persist may prefer it to a local index, though past performance is not a guide to future returns.