




Investing in the S&P 500, one of the world’s most widely tracked stock market indices, has long been a cornerstone strategy for investors seeking exposure to the US equity market. If you’re based in Canada, you may be wondering how to gain access to this investment and what the most efficient way is to do so from a Canadian account.
In this guide, we walk you through how to buy the S&P 500 from Canada step by step. We cover the key things to consider when choosing a suitable S&P 500 ETF (including the choice between Canadian-listed and US-listed options), tips for picking the right broker, currency hedging considerations, and how tax-advantaged accounts like TFSAs, RRSPs, FHSAs, and RESPs interact with US equity exposure.
How to buy the S&P 500 from Canada (Step-by-step guide)
1. Pick an ETF tracking the S&P 500
The S&P 500 tracks the performance of 500 of the largest US-listed companies, spanning a wide range of sectors and representing the bulk of the US equity market by capitalisation. Investing in it gives you broad exposure to the US economy and can serve as a cornerstone of a well-diversified long-term portfolio.
Investing in each of the 500 underlying stocks individually from Canada would be costly and impractical. Exchange-Traded Funds (ETFs) solve this by giving you a single, low-cost investment vehicle that tracks the index as a whole. By investing in S&P 500 ETFs, Canadian investors can participate in the long-term growth of the index, benefit from instant diversification, and, crucially, do so within tax-advantaged accounts like a TFSA, RRSP, FHSA, or RESP where allowed.
Canadian investors can choose between two main routes:
- Canadian-listed S&P 500 ETFs: trade in CAD on the Toronto Stock Exchange (TSX). No CAD-to-USD conversion is required, and some offer CAD-hedged versions to remove USD/CAD currency risk.
- US-listed S&P 500 ETFs: trade in USD on US exchanges (NYSE Arca, NASDAQ). Very low total expense ratios (TERs), but they require CAD-to-USD conversion, and the tax treatment of their dividends depends on the account you hold them in.
The table below shows some of the largest S&P 500 ETFs available to Canadian investors, with both TSX-listed (CAD) and US-listed (USD) options. Data is filtered using TMX Money for TSX-listed funds and ETF issuer pages for US-listed options.
Largest S&P 500 ETFs available to Canadian investors
| Name | ISIN | Ticker* | Annual fee (MER) | Replication method | Distribution policy | Fund size (CAD $B, approx) |
| Vanguard S&P 500 Index ETF | CA92205Y1051 | VFV | 0.08% | Physical | Distributing (quarterly) | ~36.2 |
| BMO S&P 500 Index ETF | CA05575T1003 | ZSP | 0.09% | Physical | Distributing (quarterly) | ~24.5 |
| iShares Core S&P 500 Index ETF (CAD-Hedged) | CA46428J1057 | XSP | 0.09% | Physical | Distributing (semi-annual) | ~16.6 |
| iShares Core S&P 500 Index ETF | CA46434R1091 | XUS | 0.09% | Physical | Distributing (semi-annual) | ~14.1 |
| Global X S&P 500 Index Corporate Class ETF | CA37964P1009 | HXS | 0.11% (plus a swap fee of up to 0.50%) | Synthetic (swap-based) | Accumulating (distributions at the manager’s discretion) | ~7.3 |
*Tickers refer to TSX listings. Fund sizes as of 7 October 2026 (ZSP as of 30 November 2025), from each issuer’s website, and they change continuously. MER = Management Expense Ratio (Canadian equivalent of TER). All ETFs above are CAD-denominated and listed on the Toronto Stock Exchange. Each fund provider offers a variety of ETFs that track the S&P 500, we’ve chosen one representative ETF per provider to simplify the comparison. To explore the full range, visit TMX Money’s ETF screener.
Don’t worry if you’re not familiar with what “replication method” and “distribution policy” mean, we’ll explain them later in this guide. For now, let’s move on to the second step of how to buy the S&P 500 from Canada.
2. Choose a good ETF broker
Once you’ve identified the ETF that suits your strategy, the next step is to pick a broker that lets you buy it efficiently. The right broker depends on your priorities: cost, tax-account support (TFSA, RRSP, FHSA, RESP), platform usability, and whether you also want access to US-listed S&P 500 ETFs (which require USD account capability and a strong FX cost structure). Below is a brief summary of what each broker offers for Canadian S&P 500 investors.
| Broker / ETF Ticker | ZSP (BMO) | VFV (Vanguard) | XSP (iShares Hedged) | XUS (iShares Unhedged) | HXS (Global X Swap) |
| Interactive Brokers | ✔ | ✔ | ✔ | ✔ | ✔ |
| Qtrade | ✔ | ✔ | ✔ | ✔ | ✔ |
| Wealthsimple | ✔ | ✔ | ✔ | ✔ | ✔ |
| Questrade | ✔ | ✔ | ✔ | ✔ | ✔ |
Beyond ETF availability, other factors matter when selecting a Canadian ETF broker: transaction fees, minimum deposit, range of available ETFs, tax-advantaged account support (TFSA, RRSP, FHSA, RESP), USD account capability (essential if you also want US-listed ETFs like SPY, VOO, or IVV), and FX conversion costs when moving between CAD and USD. Here’s how the major Canadian brokers compare:
| Broker | ETF transaction fees | Min. deposit | Total ETFs available | Tax-advantaged accounts |
| Interactive Brokers Canada | Tiered: CAD $0.003 to $0.008 per share, or fixed: CAD $0.01 per share (min CAD $1.00, max 0.5% of trade value) | CAD $0 | Canadian, US and global listings | TFSA, RRSP, FHSA, RESP, RRIF, LIRA |
| Qtrade | $0 on online ETF trades | CAD $0 | Canadian and US listings | TFSA, RRSP, FHSA, RESP, RRIF, LIRA, RDSP |
| Wealthsimple | CAD $0 on ETF trades (1.5% FX fee on US trades from a CAD account) | CAD $0 | Canadian and US listings | TFSA, RRSP, FHSA, RESP, RRIF, LIRA |
| Questrade | $0 to buy and sell Canadian and US ETFs online | CAD $1,000 | Canadian and US listings | TFSA, RRSP, FHSA, RESP, RRIF, LIRA |
Fees as of 9 October 2026, taken from each broker’s website. Wealthsimple’s USD account costs $10 a month on the Core tier and is included on Premium (from $100,000 in assets).
3. Place a “buy order”
Once you’ve chosen a broker and funded your account, you’re ready to place a “buy order” for your chosen S&P 500 ETF. In this example, we’ll use Interactive Brokers, but the same general steps apply to any major Canadian broker (Qtrade, Wealthsimple, Questrade):
a) Search for the desired S&P 500 ETF
Use the search function or browse the available ETFs to find your chosen S&P 500 ETF. Search by ticker symbol to locate it accurately. In our example, we’ll search for ZSP (BMO S&P 500 Index ETF, TSX-listed in CAD).
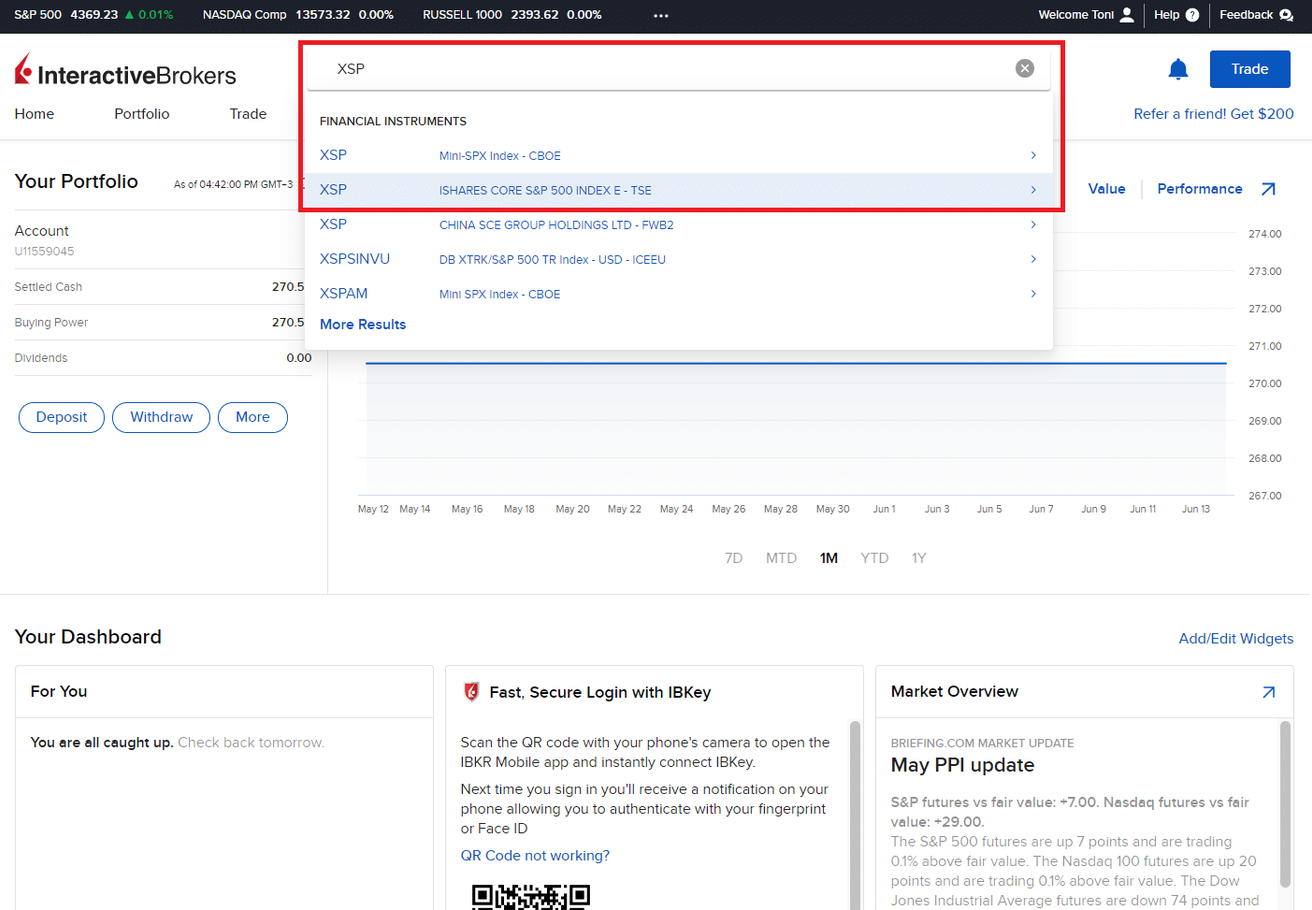
You may notice that brokers sometimes offer multiple versions of the same ETF, listed in different currencies (USD, CAD, EUR) or on different exchanges. Pick the listing that matches your account currency. As a Canadian investor with a CAD account, choosing a CAD-listed version (e.g., ZSP on TSX) avoids CAD-to-USD conversion fees on every trade.
Worth noting: if you specifically want US-listed S&P 500 ETFs like VOO or IVV, some Canadian brokers let you convert CAD to USD cheaply with a technique known as “Norbert’s Gambit”. This is particularly useful inside an RRSP, where US-listed ETFs avoid the 15% US dividend withholding tax under the Canada-US tax treaty. This is a more advanced strategy worth researching separately if you’re going down that path.
b) Click on “Buy” or “Invest”
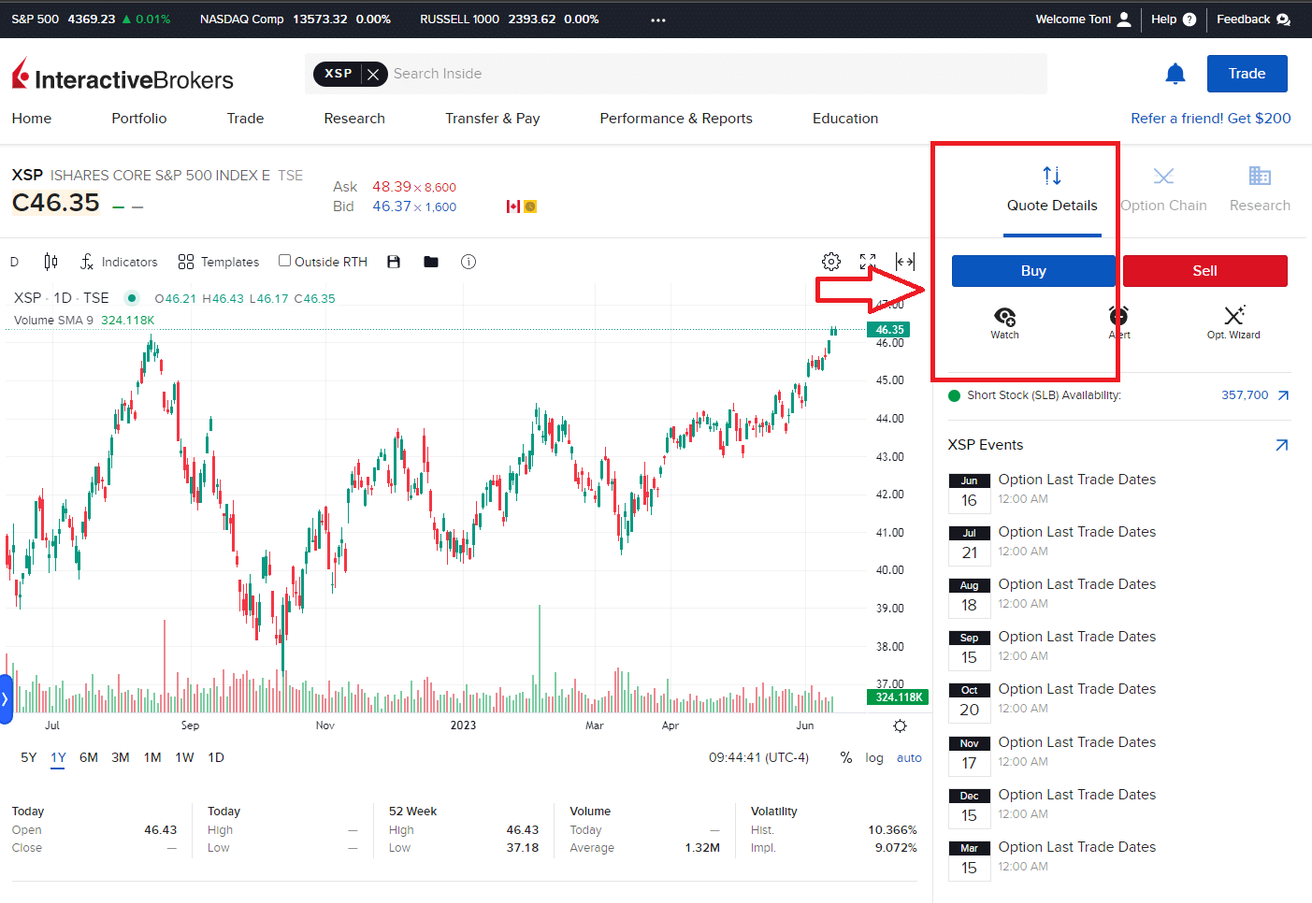
Once you’re on the ETF’s page, you’ll see a chart and key information about the fund, and the option to place an order is clearly displayed.
c) Choose the order details
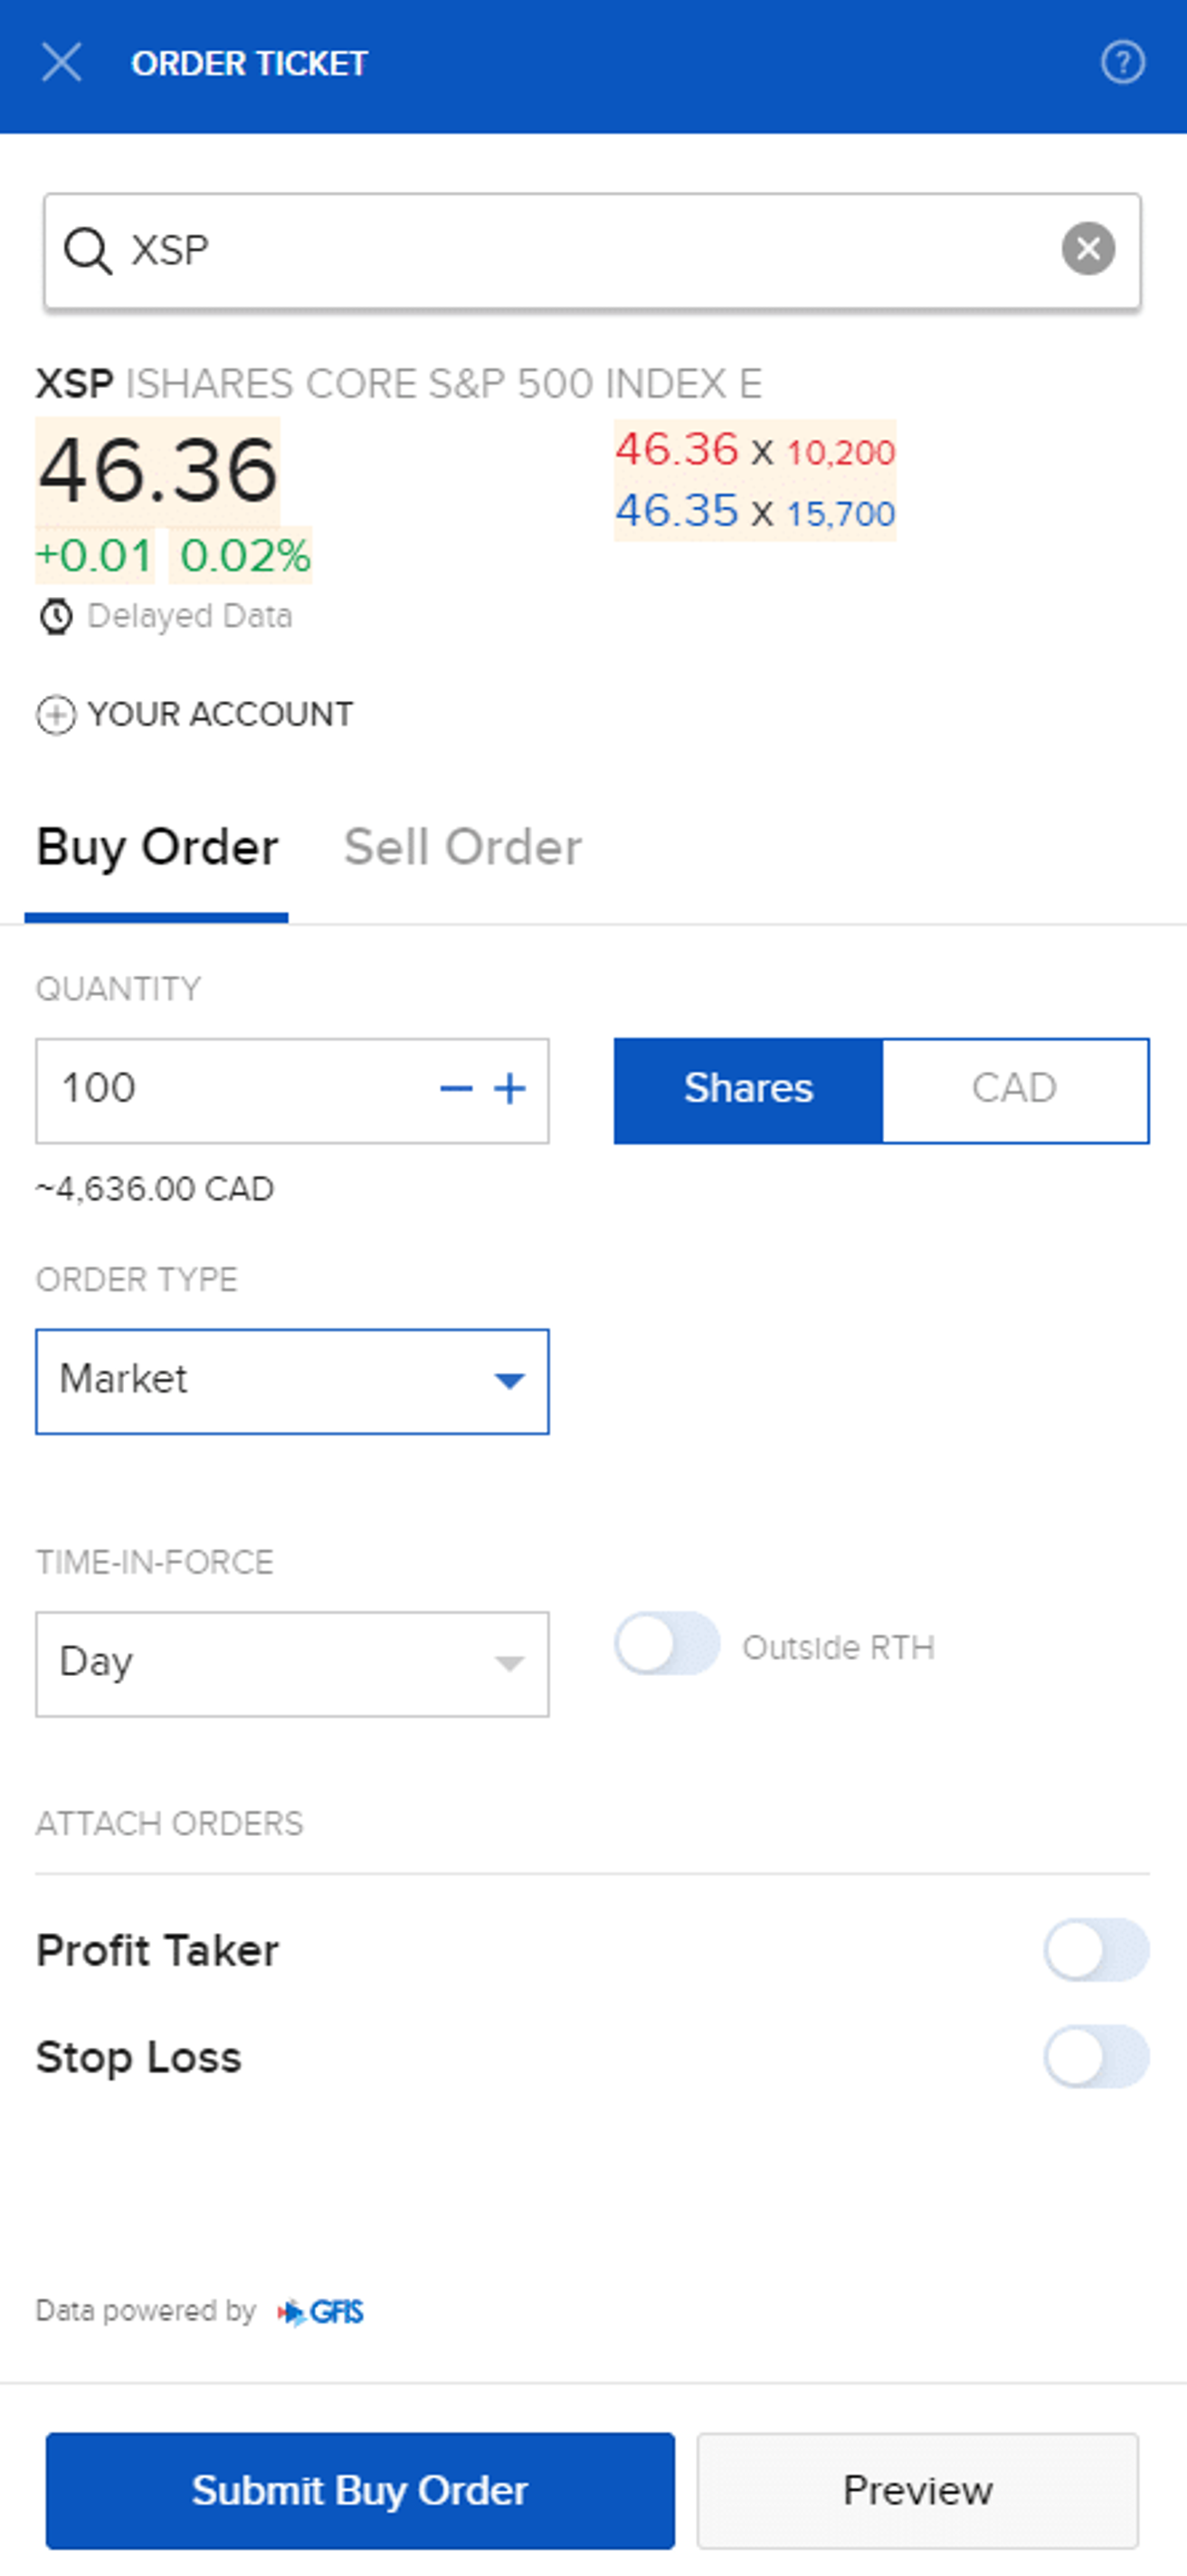
Now choose the order type that fits your strategy:
- Limit order: set by default on IBKR. You specify the maximum price you’re willing to pay, and the trade only executes if the market reaches or falls below your limit. Useful when you want price control rather than speed.
- Market order: executes at the prevailing market price, providing immediate execution. Best for most retail ETF buyers making long-term contributions, since timing precision matters less than the cost of missing the trade.
- Amount or units: specify either a fixed dollar amount to invest (if your broker supports fractional shares) or a specific number of shares. Several Canadian brokers, including Wealthsimple and IBKR, support fractional ETF shares, letting you invest specific dollar amounts without buying whole units.
d) Place the order
Finally, click “Submit Buy Order”. The broker will process the transaction and attempt to execute the trade at your specified parameters. Take a moment to review the order confirmation (ticker, quantity, price, total cost including any commissions and FX fees) before submitting.
What to look for in any ETF?
Not all ETFs are the same, and several factors are worth weighing up before deciding. Here are the most important:
1. Fees (MER)
Different asset managers charge different fees for their ETFs. Providers like BMO, Vanguard, BlackRock (iShares), and Global X charge a small annual fee that’s deducted directly from the fund’s assets, so it doesn’t show up as a separate line on your account, but it quietly reduces your returns over time. Choosing a low-fee ETF can make a meaningful long-term difference. This fee is known in Canada as the Management Expense Ratio (MER), and elsewhere as the Total Expense Ratio (TER) or Ongoing Charges Figure (OCF). For Canadian-listed S&P 500 ETFs, MERs range from 0.08% (VFV) to 0.11% (HXS), all very competitive. Note that the MER does not include trading costs: HXS also pays a swap fee of up to 0.50% a year, and its trading expense ratio was 0.49% at 30 June 2026.
2. Replication method
ETFs use two main replication methods:
- Physical replication: the fund actually holds the underlying assets in the index. For an S&P 500 ETF, this means owning shares in the 500 underlying US companies (ZSP, VFV, XSP, XUS).
- Synthetic replication: the fund uses derivatives (typically total return swaps) to mirror the index’s performance rather than holding the underlying stocks directly. The Canadian S&P 500 ETF using this approach is Global X’s HXS.
For S&P 500 exposure specifically, both approaches work well given the deep liquidity of the underlying companies. However, synthetic replication has one important Canadian tax advantage: because HXS doesn’t hold US stocks directly, it isn’t subject to the 15% US withholding tax on dividends, the dividend income is instead converted into capital gains via the swap structure. This can make HXS attractive in non-registered (taxable) accounts. However, weigh that benefit against its swap costs (a trading expense ratio of 0.49% at 30 June 2026, on top of the 0.11% MER) and the counterparty risk of the swap.
3. Distribution policy (accumulating vs distributing)
ETFs differ in how they handle income (mainly dividends) generated by the underlying companies:
- Accumulating ETFs automatically reinvest dividends back into the fund, increasing the share price over time rather than paying out cash. Among Canadian S&P 500 ETFs, only HXS (Global X) follows this structure via its swap-based design.
- Distributing ETFs pay dividends directly to your brokerage account on a regular schedule (typically quarterly for US equity ETFs). The major Canadian-listed S&P 500 ETFs, ZSP, VFV, XSP, XUS, are all distributing.
The right choice depends heavily on your situation and account type:
- Inside a TFSA, RRSP, FHSA, or RESP: dividend taxation isn’t an immediate concern (the TFSA, FHSA and RESP are tax-sheltered, and the RRSP defers tax until withdrawal), so the distinction matters less from a tax perspective. It’s mainly an operational preference for whether you want cash distributions or automatic reinvestment.
- In a non-registered (taxable) account: Canadian-listed S&P 500 ETF distributions are taxed in the year received, even if you reinvest them through a dividend reinvestment plan (DRIP). Dividends from the underlying US companies also incur the 15% US withholding tax, except when held in an RRSP. HXS sidesteps both the immediate distribution taxation and the US withholding via its swap structure, which can make it tax-efficient in a non-registered account, though it carries swap costs and counterparty risk.
For personalised tax advice, consult a qualified Canadian tax professional. When you eventually sell your ETF holdings, capital gains tax may also apply depending on the account type and your overall tax situation.
4. Fund size
Consider the overall fund size (AUM, Assets Under Management) when selecting an ETF. Larger funds generally carry a lower risk of liquidation than smaller ones, with tighter bid-ask spreads and better day-to-day liquidity. In the event of liquidation, a fund sells its holdings, settles obligations and returns the remaining proceeds to investors, which can trigger capital gains in non-registered accounts. For Canadian S&P 500 ETFs, sticking to options with at least CAD $1 billion+ AUM is a sensible rule of thumb, and all five ETFs above comfortably exceed this threshold.
5. Currency hedging
Some ETFs use currency hedging (typically forward contracts) to mitigate fluctuations between the ETF’s listing currency (CAD) and the underlying assets’ currency (USD for the S&P 500). Hedging has a cost that does not always show in the MER (XSP and XUS both have a 0.09% MER), but it affects returns through the hedging transactions. It can protect you against short-term currency swings, though that cost adds up over decades.
Among the Canadian S&P 500 ETFs covered above, only XSP (iShares Core S&P 500 Index ETF CAD-Hedged) is currency-hedged, the others (ZSP, VFV, XUS, HXS) leave you with unhedged USD exposure. Many long-term investors prefer unhedged exposure for holding periods of 10 years or more, as currency moves tend to matter less over long periods. CAD-hedged ETFs are typically more useful for shorter-term or income-focused investors, or for those who specifically want to remove the CAD/USD currency variable from their portfolio.
The bottom line
In conclusion, investing in the S&P 500 from Canada is one of the most popular ways to gain broad exposure to the US stock market. Here’s a summary of the steps:
- Pick an S&P 500 ETF: options like VFV (Vanguard, 0.08% MER), ZSP (BMO, 0.09% MER), XSP (iShares, CAD-hedged, 0.09% MER), XUS (iShares, unhedged, 0.09% MER) and HXS (Global X, swap-based, 0.11% MER plus swap costs) all track the same index with different structures. Sophisticated investors with an RRSP may also consider US-listed ETFs like VOO, IVV, or SPY to avoid the 15% US dividend withholding tax under the Canada-US tax treaty.
- Find a suitable broker: choosing the right broker matters. Consider available ETFs, transaction and platform fees, FX conversion costs (particularly important if buying US-listed ETFs), tax-advantaged account support (TFSA, RRSP, FHSA, RESP), and minimum deposit. See our list of brokers offering free stocks, trades, and cash bonuses in Canada for current promotions.
- Open an account and deposit funds: once you’ve picked a broker, complete the digital onboarding (typically same-day for major Canadian brokers), verify your identity, and fund the account in CAD via Interac e-Transfer, bank transfer, or other supported methods.
- Place your order: on your broker’s platform, search for the ETF by ticker (ZSP, VFV, XSP, XUS, or HXS), choose your order type (market for simplicity, limit for price control), specify the amount or quantity, and confirm. Several Canadian brokers, such as Wealthsimple and IBKR, support fractional shares if a full share is more than you want to buy.
- Hold for the long term and use tax wrappers: S&P 500 investing is most effective as a long-term strategy. Consider setting up automatic monthly contributions, and prioritise holding inside tax-advantaged accounts (TFSA for tax-free growth, RRSP for tax-deferred growth and US-listed ETF tax efficiency, FHSA for first-home savings, or RESP for children’s education) to maximise long-term after-tax returns.
We hope this guide has answered your questions. Always do your own research to determine the best strategy for your specific situation.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Investments can go down as well as up, and past performance is not a reliable indicator of future results. Canadian tax rules are complex and subject to change. Consider consulting a qualified financial advisor or tax professional regarding your specific situation, particularly around the choice between Canadian-listed and US-listed ETFs and the use of registered accounts.
FAQs
What is the S&P 500?
The S&P 500 is a widely recognized stock market index that tracks the performance of 500 large-cap U.S. companies.
Why would someone in Canada want to invest in the S&P 500?
Investing in the S&P 500 allows Canadian investors to gain exposure to the US market and potentially benefit from its long-term growth.
Which brokers in Canada offer access to S&P 500 ETFs?
Several brokers in Canada offer access to S&P 500 ETFs, including popular platforms like Interactive Brokers, Wealthsimple, Questrade, and Qtrade.
Can I hold S&P 500 ETFs in tax-efficient accounts such as TFSA, RESP, or RRSP?
Yes. All four brokers in this guide let you hold S&P 500 ETFs in a TFSA, RRSP, FHSA or RESP. Inside an RRSP, US-listed ETFs also avoid the 15% US withholding tax on dividends under the Canada-US tax treaty.
What is an Exchange Traded Fund (ETF)?
An Exchange Traded Fund (ETF) is a type of investment fund traded on stock exchanges. It is designed to track the performance of a specific index, commodity, sector, or asset class. If you invest in an S&P 500 ETF, you will gain exposure to the performance of about 500 companies without the need to invest in each individual company separately. This provides a convenient and efficient way to diversify your investment across a wide range of holdings within the index.
What are CFDs? Should I invest in S&P500 CFDs?
Contracts for Difference (CFDs) are derivative financial instruments that allow traders to speculate on the price movements of an underlying asset without actually owning the asset itself. Investing in S&P 500 CFDs involves trading based on the price fluctuations of the S&P 500 index. To learn more about it, read our article: CFDs vs Shares: Understand the Differences.






