



iBonds ETFs, introduced by iShares from BlackRock in the US in 2010 and in Europe in August 2023, offer a suite of bond ETFs with fixed maturity dates. These ETFs hold a diversified portfolio of bonds sharing similar maturity dates.
Below, we explain how they work, how they differ from individual bonds and traditional bond ETFs, which funds are the largest and where you can buy them. Fund data comes from iShares factsheets checked in October 2026.
What is an iBonds ETF?
An iBonds ETF is an ETF that holds a diversified portfolio of bonds with similar maturity dates.
They are essentially a basket of bonds from different issuers, all selected to be repaid around the same time. When the maturity date arrives, you get your money back. You also receive the interest either at maturity (accumulating ETF) or periodically over time (distributing ETF).
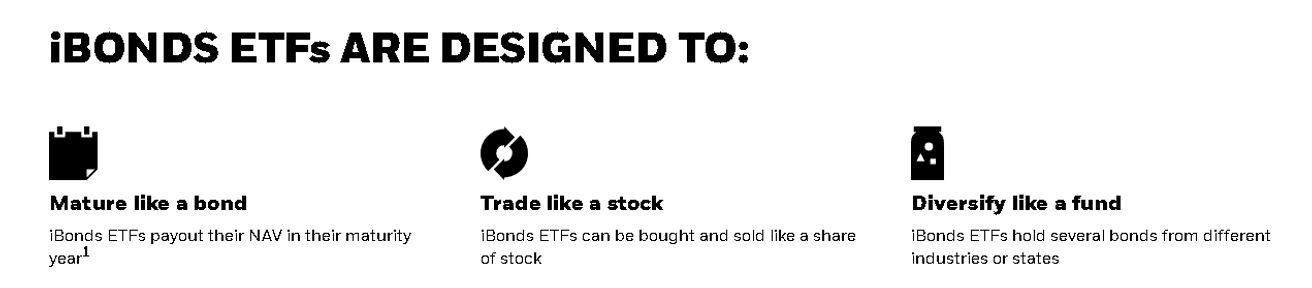
They are designed to “mature like a bond, trade like a stock, and diversify like a fund”.
Introduced by iShares from BlackRock, iBonds ETFs have been available in the US since 2010 but failed to gain much traction during the low-interest-rate decade that followed the global financial crisis. Since then, according to iShares, 4 US Treasury, 13 municipal, 17 investment-grade corporate and 4 high-yield iBonds ETFs have matured and been liquidated as planned. In Europe, the first four UCITS iBonds ETFs launched on 10 August 2023, maturing in December 2026 and December 2028. By May 2026, BlackRock said the range had captured about 90% of the defined-maturity bond ETF category in Europe, with maturities now running to 2037. These ETFs provide a diversified basket of bonds within a chosen sub-asset class, all sharing a similar maturity date. At maturity, they distribute a final payout.
What sets iBonds ETFs apart from traditional bond ETFs is the fixed maturity date. Traditional bond ETFs have no expiration date, adding new bonds as others mature, which gives continuous, rolling exposure to bond markets.
BlackRock is not alone in this segment. Invesco offers a comparable product called BulletShares. While the two are similar in structure, we focus on iBonds ETFs here, as iShares offers the larger and more widely used range.
Since launching the first iBonds ETF in the US in 2010, iShares has built out a broad range of these funds, offering an experience closely resembling that of holding a diversified portfolio of individual bonds. They span a spectrum of risk levels, with the more conservative options holding US Treasuries and risk increasing across each tier. The highest risk tier is the High Yield and Income Corporate category.
There are five distinct asset classes within iBonds ETFs:
- US Treasuries
- US TIPS (Treasury Inflation-Protected Securities)
- Municipals (US state and local government bonds)
- Investment-grade corporate bonds
- High-yield bonds
This range allows you to tailor your strategy to your risk tolerance and investment goals. In Europe, the lineup is made up of corporate bond funds in euros and US dollars, plus some government bond funds.
It is also worth knowing that iBonds ETFs can be either distributing or accumulating. An accumulating iBonds ETF retains and reinvests coupon income until the maturity date. When that point arrives, after all bonds in the portfolio have matured, the ETF is closed and shareholders receive a final distribution equal to the fund’s NAV (net asset value). A distributing iBonds ETF instead pays income to shareholders at a set frequency, which is specified in each fund’s factsheet.
Estimate the yield of your iBonds ETF investment
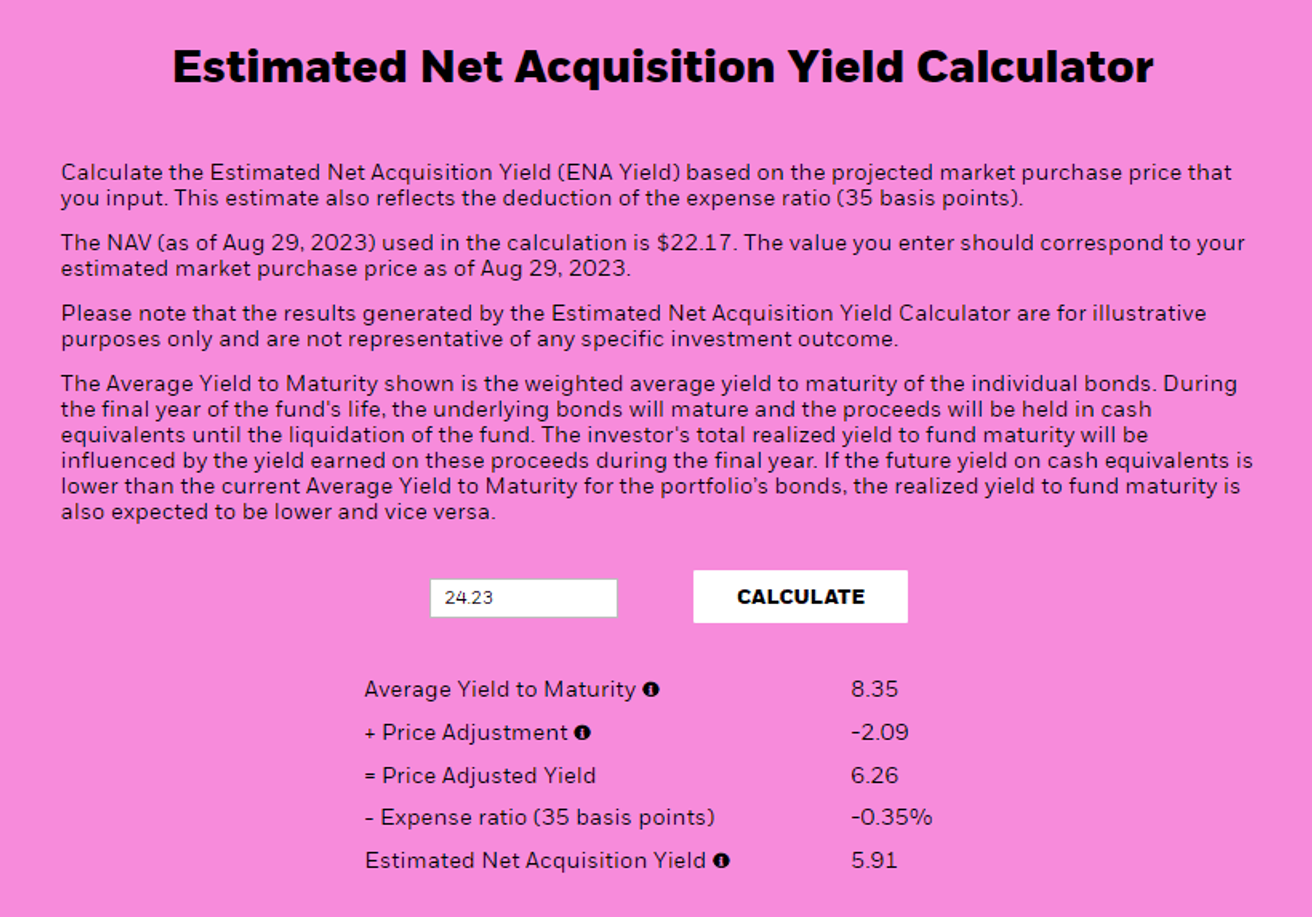
When you are ready to purchase an iBonds ETF, iShares provides a tool to help you understand the fund’s estimated net acquisition yield. If the fund is held to maturity, this figure gives a yield estimate net of fees and market price impact.
On each iBonds ETF product page, the Estimated Net Acquisition Yield Calculator generates a yield estimate once you enter a projected market price.
Here is an illustrative example of how the tool works:
Understanding fixed maturity and yield to maturity
Like individual bonds, iBonds ETFs have a fixed maturity date, so investors can anticipate a final repayment at maturity, along with regular income if the fund is a distributing share class. As noted, iBonds ETFs track an underlying index, offering exposure to hundreds of bonds across different sectors and countries with similar maturity dates. They are available across a range of maturities, letting you select the timeframe that matches your investment horizon.
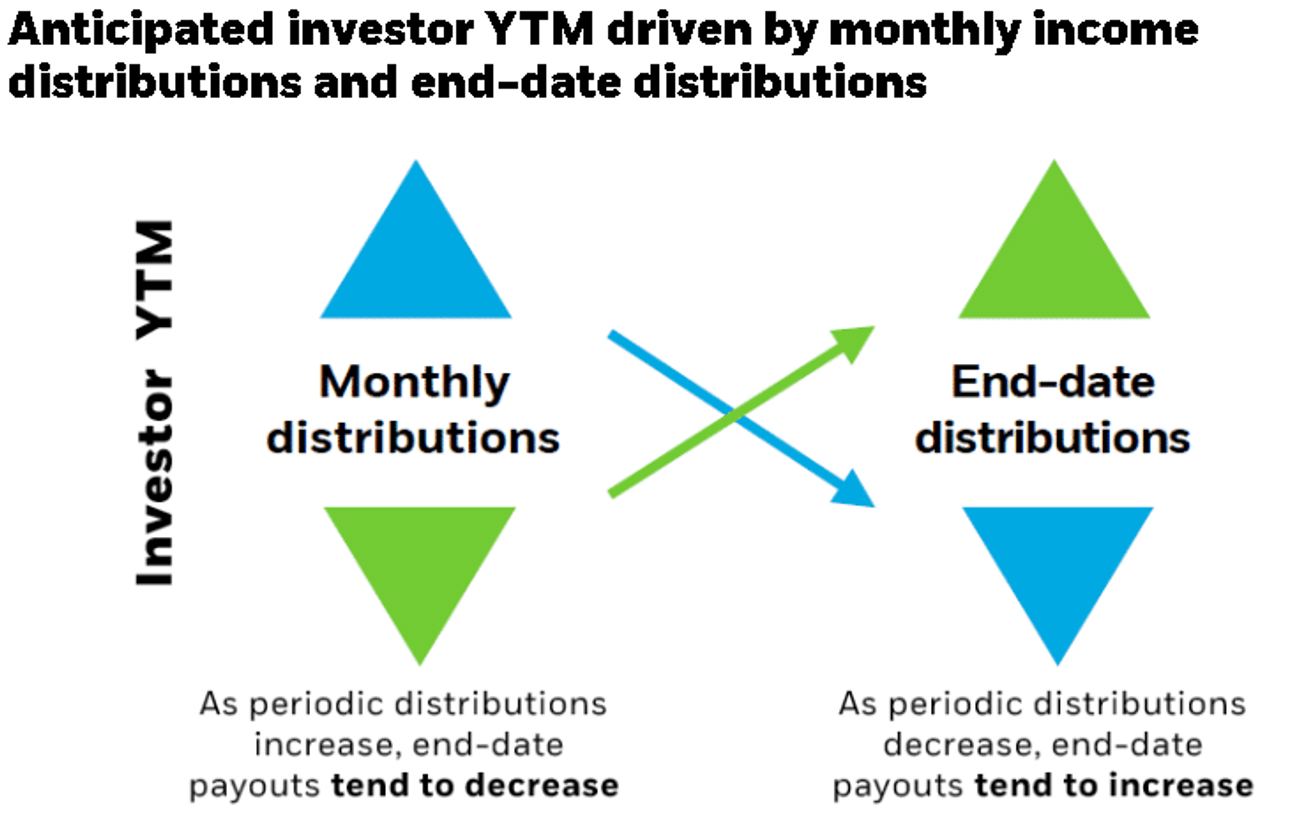
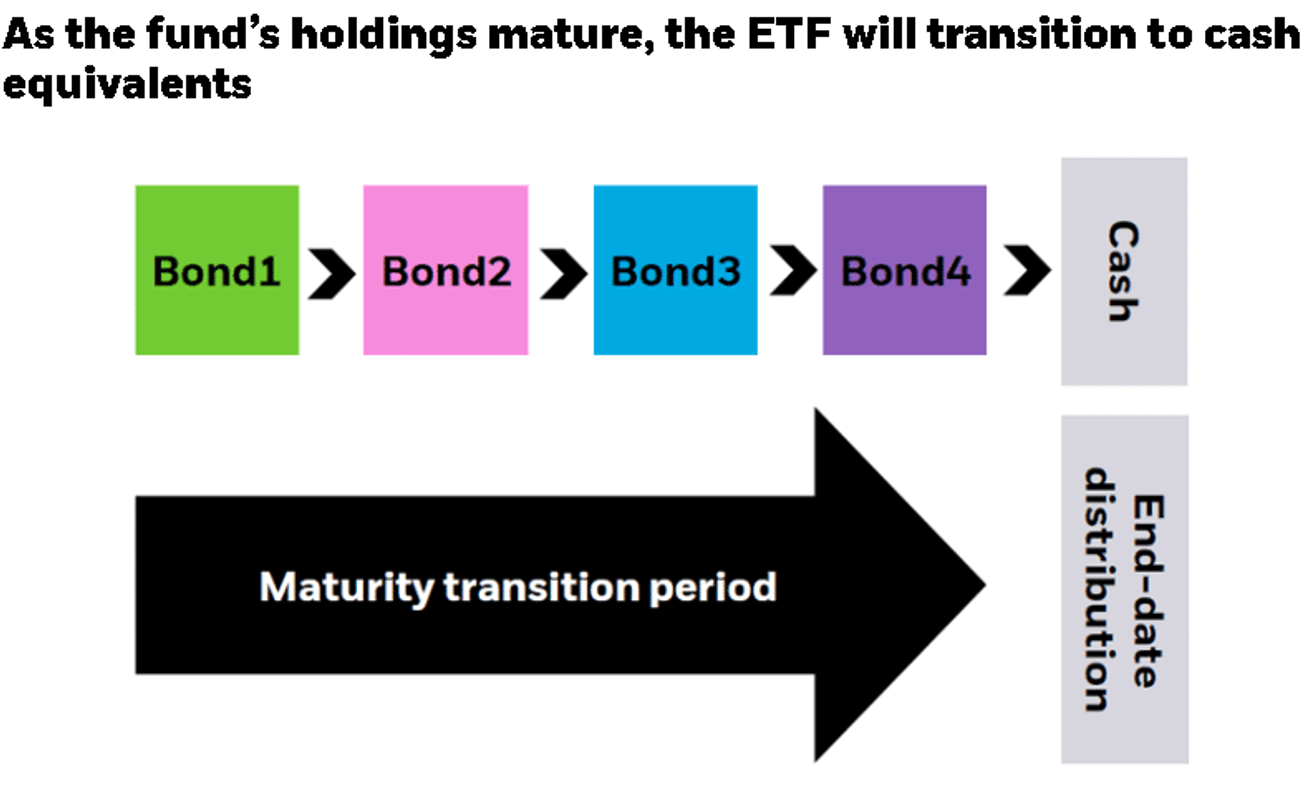
iBonds ETFs are designed to deliver a yield-to-maturity (YTM) profile that mirrors the underlying bond portfolio, using a combination of periodic distributions and a final end-date distribution. That final payout follows once all underlying bonds have matured. Worth understanding: as individual bonds within the portfolio mature ahead of the fund’s end date, the proceeds are held as cash and cash equivalents in money market funds or short-term government securities. This means that in the fund’s closing months, the effective yield tends to drift toward prevailing short-term rates rather than the original YTM.
When is the maturity date of iBonds ETFs?
iBonds ETFs terminate in October or December of the year named in the fund, which is why the maturity year appears directly in the ETF’s name. In Europe, the corporate funds are redeemed in early December. The Dec 2029 Term € Corp fund, for example, has a mandatory redemption date of 3 December 2029.
During the final months, as the bonds in the portfolio reach maturity, the fund progressively shifts its holdings into liquid assets such as cash and cash equivalents.
Once all portfolio bonds have matured, the ETF is closed and shareholders receive a final distribution equal to the fund’s NAV. If you have held an individual bond before, the experience will feel familiar. It mirrors the principal repayment of a single bond at maturity, with the difference that the repayment comes from a diversified basket rather than a single issuer.
What are the benefits of iBonds ETFs?
1. Easy access to the bond market
Trading individual bonds has traditionally been difficult for retail investors, since most bonds are not exchange-listed and typically require large minimum investments. iBonds ETFs solve this by trading like any stock on an exchange, giving straightforward access to a diversified basket of bonds from a standard brokerage account. Costs are low: the US Treasury funds charge 0.07% a year, the US corporate funds 0.10% and the euro corporate UCITS funds 0.12%.
2. Diversification
iBonds ETFs track an underlying index, offering exposure to hundreds of bonds across different sectors and issuers. The iShares iBonds Dec 2030 Term Corporate ETF (IBDV), for example, held 729 bonds in June 2026. This substantially reduces the single-issuer default risk you would carry when holding one individual bond, which is particularly relevant in the corporate and high-yield segments.
3. Fixed maturity date
iBonds ETFs let you choose your time horizon. They are available across a range of maturity years, so you can match the duration of your investment to a specific future goal. Traditional bond ETFs, with their rolling exposure, cannot offer this.
4. Lower price sensitivity if held to maturity
If you plan to hold the fund until maturity, day-to-day price movements matter less, since you can expect a final distribution based on the fund’s NAV at that point. As the maturity date approaches, the portfolio’s duration also falls, reducing sensitivity to interest rate changes.
It is worth noting the limits of this. The final payout is not guaranteed in the way a single bond’s principal repayment is: it depends on the NAV at closure, which can be affected by defaults within the portfolio, particularly in high-yield funds. Selling before maturity also exposes you to prevailing market prices, so the lower price sensitivity applies specifically to a hold-to-maturity strategy.
How does it compare to other investment options?
iBonds ETFs sit between a traditional bond ETF and an individual bond. Like a bond ETF, they hold a diversified basket traded on an exchange. Like an individual bond, they have a fixed maturity date, so their sensitivity to interest rates falls as that date approaches.
| Feature | iBonds ETF | Traditional bond ETF | Individual bond |
| Maturity date | Yes, fixed | No, rolling exposure | Yes, fixed |
| Diversification | Hundreds of bonds | Hundreds of bonds | One issuer |
| Minimum investment | One share (a few euros or dollars) | One share | Often €1,000 or more per bond |
| Interest rate sensitivity | Falls as maturity approaches | Stays roughly constant | Falls as maturity approaches |
| Final payout | NAV at closure (not guaranteed) | None, you sell at market price | Face value, unless the issuer defaults |
| Trading | On an exchange, like a stock | On an exchange, like a stock | Mostly over the counter |
Largest iBonds ETFs by assets
For US investors
| iBonds ETF | Ticker | AUM (USD millions) |
| iShares iBonds Dec 2028 Term Corporate ETF | IBDT | 3,990 |
| iShares iBonds Dec 2029 Term Corporate ETF | IBDU | 3,963 |
| iShares iBonds Dec 2027 Term Corporate ETF | IBDS | 3,792 |
| iShares iBonds Dec 2026 Term Corporate ETF | IBDR | 3,505 |
| iShares iBonds Dec 2030 Term Corporate ETF | IBDV | 3,198 |
| iShares iBonds Dec 2031 Term Corporate ETF | IBDW | 2,467 |
| iShares iBonds Dec 2026 Term Treasury ETF | IBTG | 2,308 |
| iShares iBonds Dec 2027 Term Treasury ETF | IBTH | 2,204 |
| iShares iBonds Dec 2028 Term Treasury ETF | IBTI | 1,778 |
| iShares iBonds Dec 2032 Term Corporate ETF | IBDX | 1,700 |
Source: iShares fund factsheets, net assets as of 30 June 2026.
The Dec 2025 funds (IBTF and IBDQ) matured and closed in December 2025, and the Dec 2026 funds will close at the end of 2026. Fund sizes change continuously, so check the current figures on the iShares website. You can find the full list of US iBonds ETFs here.
For European investors
| iBonds ETF | Ticker | Share class size (millions) |
| iShares iBonds Dec 2028 Term € Corp UCITS ETF EUR (Dist) | IB28 | €1,451 |
| iShares iBonds Dec 2028 Term € Corp UCITS ETF EUR (Acc) | IVOA | €1,044 |
| iShares iBonds Dec 2027 Term € Corp UCITS ETF EUR (Acc) | IB27 | €880 |
| iShares iBonds Dec 2026 Term € Corp UCITS ETF EUR (Dist) | IB26 | €610 |
| iShares iBonds Dec 2026 Term € Corp UCITS ETF EUR (Acc) | CEBE | €600 |
| iShares iBonds Dec 2029 Term € Corp UCITS ETF EUR (Acc) | 29GA | €509 |
| iShares iBonds Dec 2027 Term $ Corp UCITS ETF USD (Acc) | ID27* | $459 |
| iShares iBonds Dec 2029 Term € Corp UCITS ETF EUR (Dist) | 29GI | €433 |
| iShares iBonds Dec 2027 Term € Corp UCITS ETF EUR (Dist) | IBE7 | €408 |
| iShares iBonds Dec 2026 Term $ Corp UCITS ETF USD (Acc) | D26A* | $385 |
Source: iShares fund factsheets, share class net assets as of 31 August 2026. *USD-denominated share classes.
European investors buying USD share classes are exposed to EUR/USD currency movements on top of bond market risk. The Dec 2028 Term € Corp fund is the largest in Europe, with about €2.5 billion across its two share classes. You can find the full list of European iBonds ETFs here.
Where to buy an iBonds ETF?
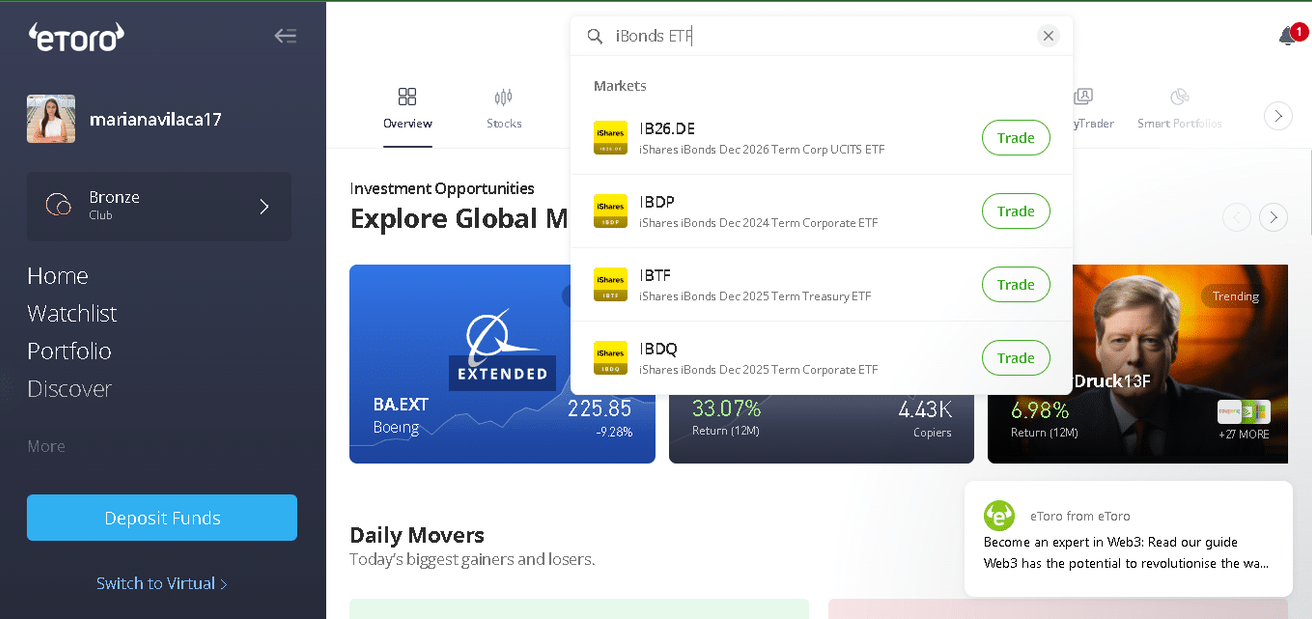
To invest in iBonds ETFs, you must find a broker offering them. Below, we present some options for you to consider. All are supervised by top-tier regulators and offer low trading costs. European retail investors can only buy the UCITS iBonds ETFs, so check that the specific fund and share class you want is available before opening an account.
55% of retail CFD accounts lose money.
eToro dashboard
Capital at Risk. Sponsored Link. To get free fractional shares worth up to 100 EUR/GBP, you can open an account with Trading 212 through this link. Terms apply.
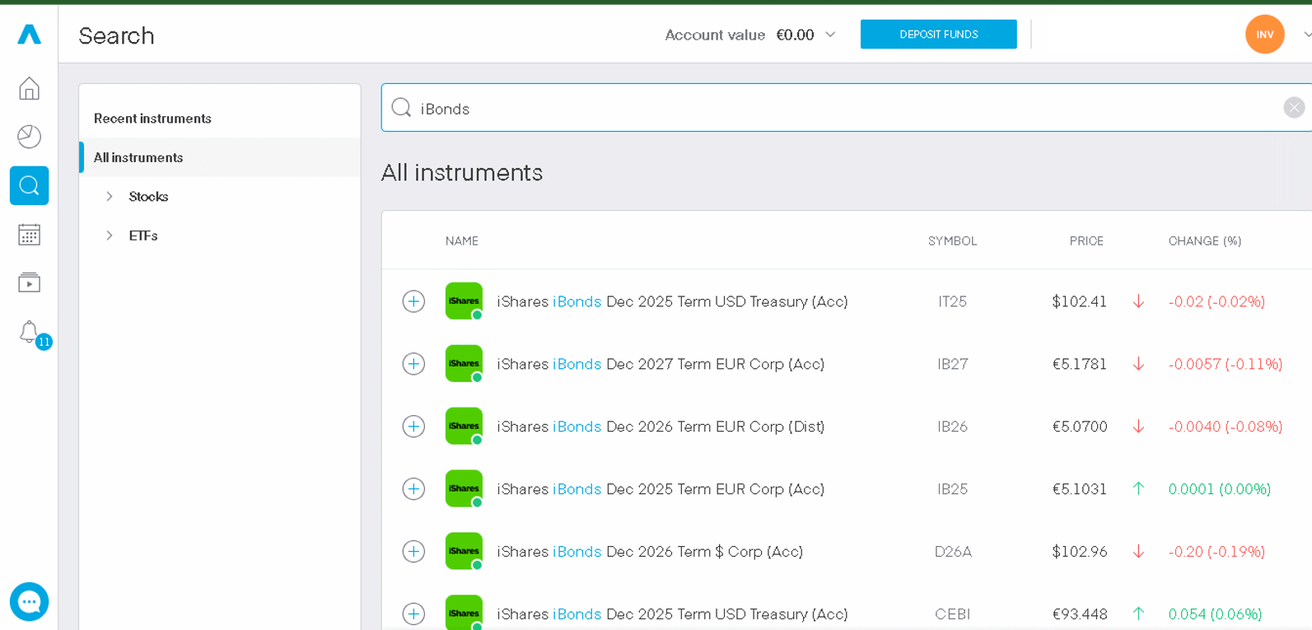
Trading 212 dashboard
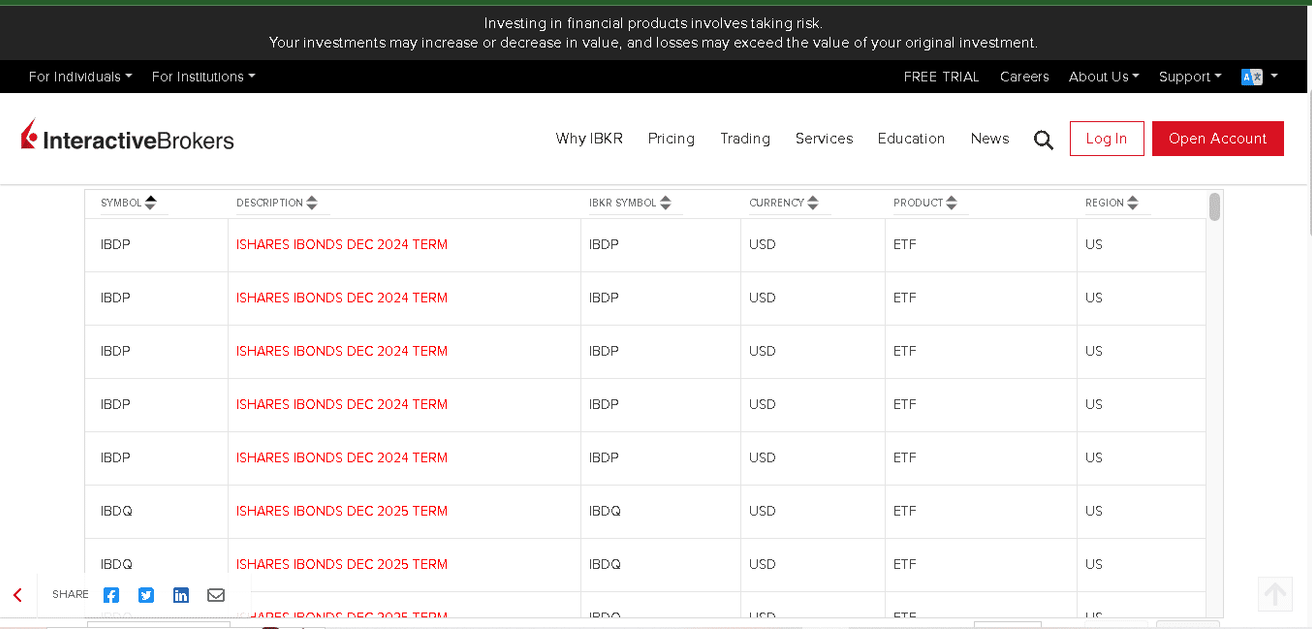
Interactive Brokers dashboard
62% of retail CFD accounts lose money.
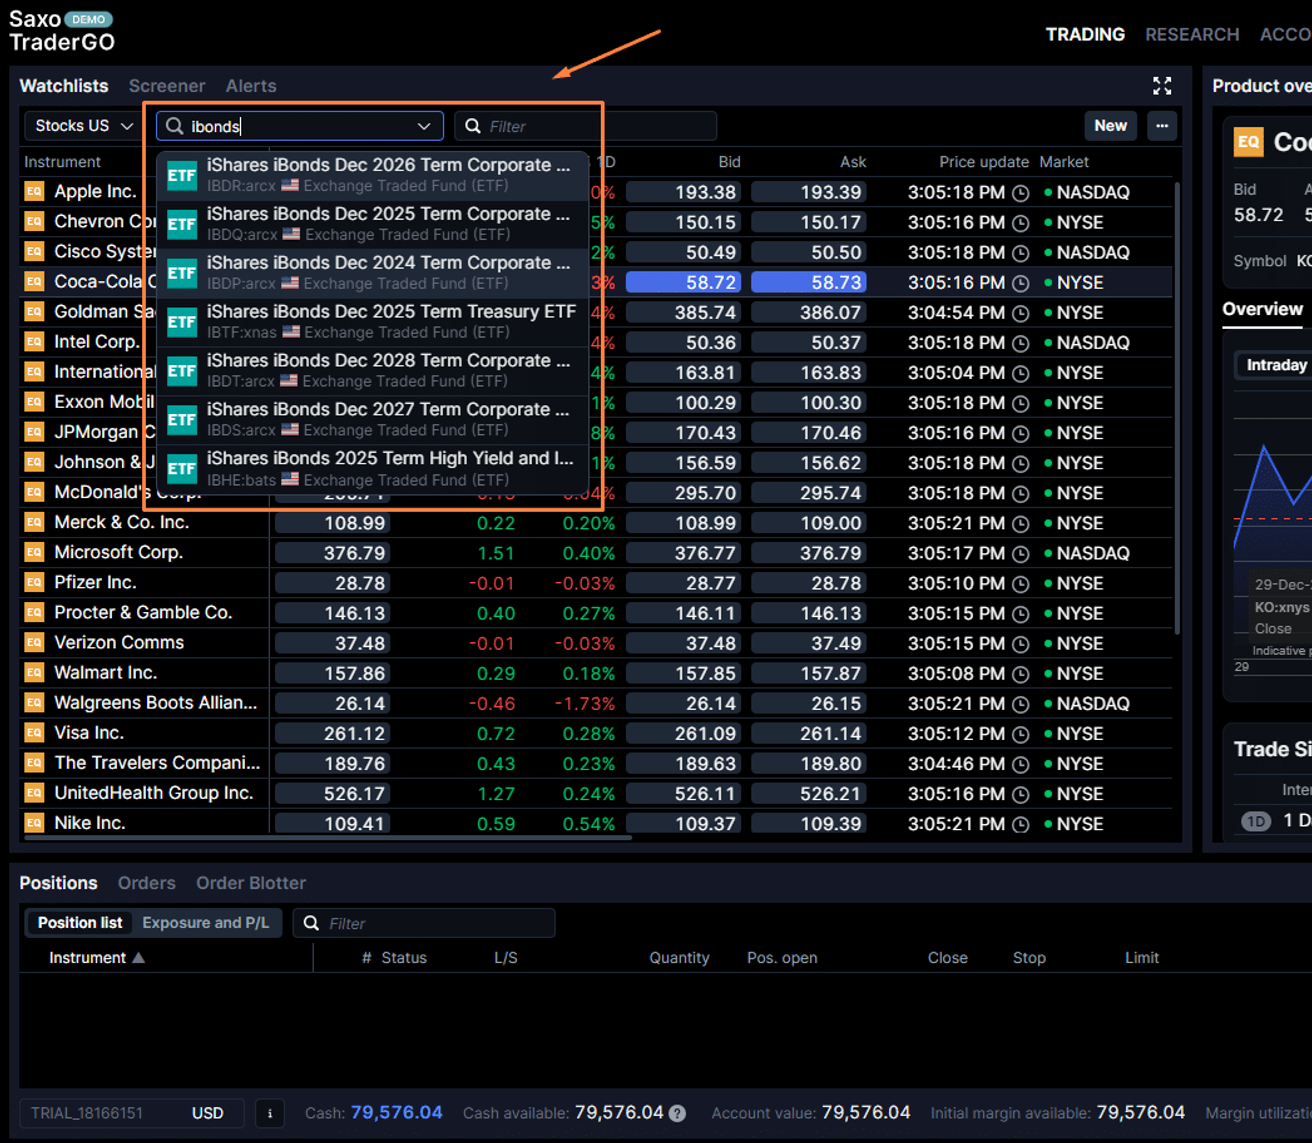
SaxoPro dashboard
69-80% of retail CFD accounts lose money.
Bottom line
iBonds ETFs combine the strengths of traditional bond ETFs (diversification and straightforward exchange-traded access) with the defining feature of an individual bond: a fixed maturity date. This lets you select a fund based on your own time horizon rather than accepting the rolling, open-ended exposure of a conventional bond ETF.
The product was introduced by iShares in the US in 2010 and reached Europe in August 2023. Interest picked up considerably once interest rates rose from their historic lows, since higher yields made fixed-maturity bond exposure far more attractive to retail investors than it had been during the preceding low-rate decade.
A few points worth carrying away before investing:
- Check the domicile: European investors need UCITS share classes, since US-domiciled iBonds ETFs are not available to EU retail clients under the PRIIPs (Packaged Retail and Insurance-based Investment Products) regulation.
- Check the currency: USD-denominated share classes carry EUR/USD exposure that can outweigh the yield on a short-dated bond fund.
- Check accumulating versus distributing: the right choice depends on your income needs and local tax treatment.
- Understand the final payout: the closing distribution reflects the fund’s NAV at maturity, so it is not equivalent to the guaranteed principal repayment of a single government bond.
Earlier in this article we outlined where you can buy these instruments. If you are a European investor, eToro and XTB list several UCITS iBonds ETFs as real ETFs, while Trading 212 and Saxo each have their own product range, so verify that the specific UCITS iBonds ETF you want is available before opening an account. Interactive Brokers offers the broadest fixed income access and is generally the most reliable route to the full iBonds range.
eToro is a multi-asset investment platform. The value of your investments may go up or down. Your capital is at risk.
FAQ
Is the final payout of an iBonds ETF guaranteed?
No. At maturity you receive the fund’s NAV, which depends on whether all bonds in the portfolio repaid in full. A default within the fund lowers the final payout.
What happens if I keep holding the ETF until the end?
The fund is closed, your shares are redeemed automatically and the final distribution is paid in cash to your brokerage account. You don’t need to sell.
Can European investors buy US iBonds ETFs such as IBDS?
Generally no. EU retail investors can’t buy US-domiciled ETFs because they don’t publish the KID (Key Information Document) required under PRIIPs. They can buy the UCITS iBonds ETFs listed in Europe instead.
Can I build a bond ladder with iBonds ETFs?
Yes. Buying several funds with different maturity years gives you money back at regular intervals, which you can spend or reinvest. iShares offers an iBonds ladder tool on its US website.
Disclaimer: When investing, your capital is at risk and you may get back less than invested. Past performance doesn’t guarantee future results.
CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 55% of retail investor accounts lose money when trading CFDs with this provider. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. Between 69-80% of retail investor accounts lose money when trading CFDs. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.






