Even though inequality on a global level has been declining for decades, there are still large differences between countries in most areas of life, including personal finance.
In this article, we cover 24 statistics across six areas:
- Psychological, emotional and societal factors
- Financial literacy and education
- Net worth
- Income
- Inflation
- Real estate
All figures were checked against the latest available data in October 2026. Let’s look at the current state of the world in each area and how it has changed over time.
Psychological, emotional and societal factors
Psychology and emotions play a big role in personal finance and investing. Humans are not 100% rational and don’t always act the way economic theory expects.
Let’s look at some of these factors:
1. Most people think extreme poverty is rising, even though it has fallen by more than three quarters since 1990
According to Our World in Data, people tend to think about their own future optimistically but about society’s collective future pessimistically. The first probably stems from our evolutionary wiring (the will for self-preservation), and the second from the influence of modern societal structures and media.

Extreme poverty is a good example. In a survey by Ipsos for Gapminder of 10,024 adults in 12 countries, 61% said the share of people living in extreme poverty had almost doubled over the previous 20 years and 32% said it had stayed about the same. Only 7% gave the correct answer: it had almost halved.
The World Bank Poverty and Inequality Platform shows how far off that perception is. Using the current international poverty line of $3.00 a day (in 2021 purchasing power parity, or PPP, dollars), 43.4% of the world lived in extreme poverty in 1990. By 2024, the share was 10.1%, or about 824 million people, and the World Bank’s nowcast puts it at 9.8% in 2026.
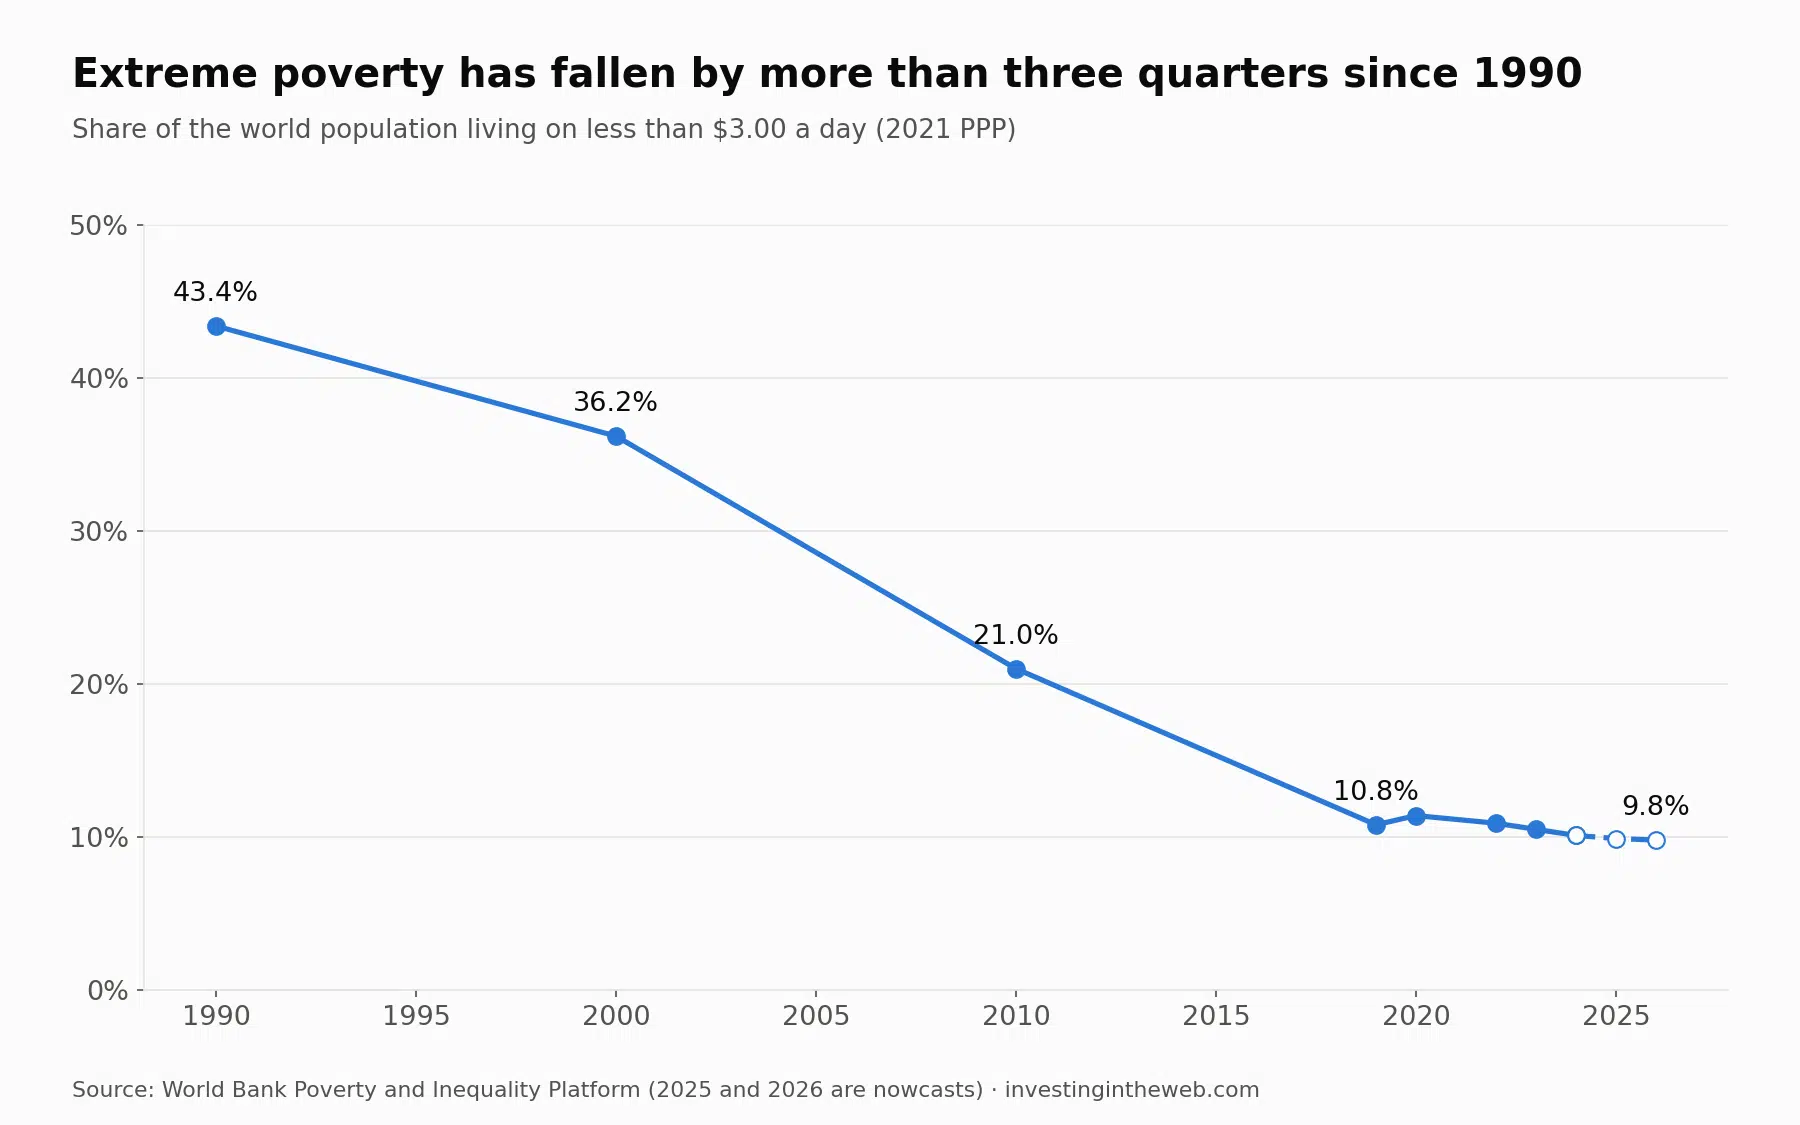
Progress has slowed since 2019, as the pandemic and the following price shocks hit the poorest countries hardest. Still, looking at the trend over decades, the world is a much better place financially than it was a generation ago, and countries that have recently experienced a rising standard of living tend to be more optimistic about the future.
2. More than a third of Americans say they are struggling with money, up from 22% in 2021
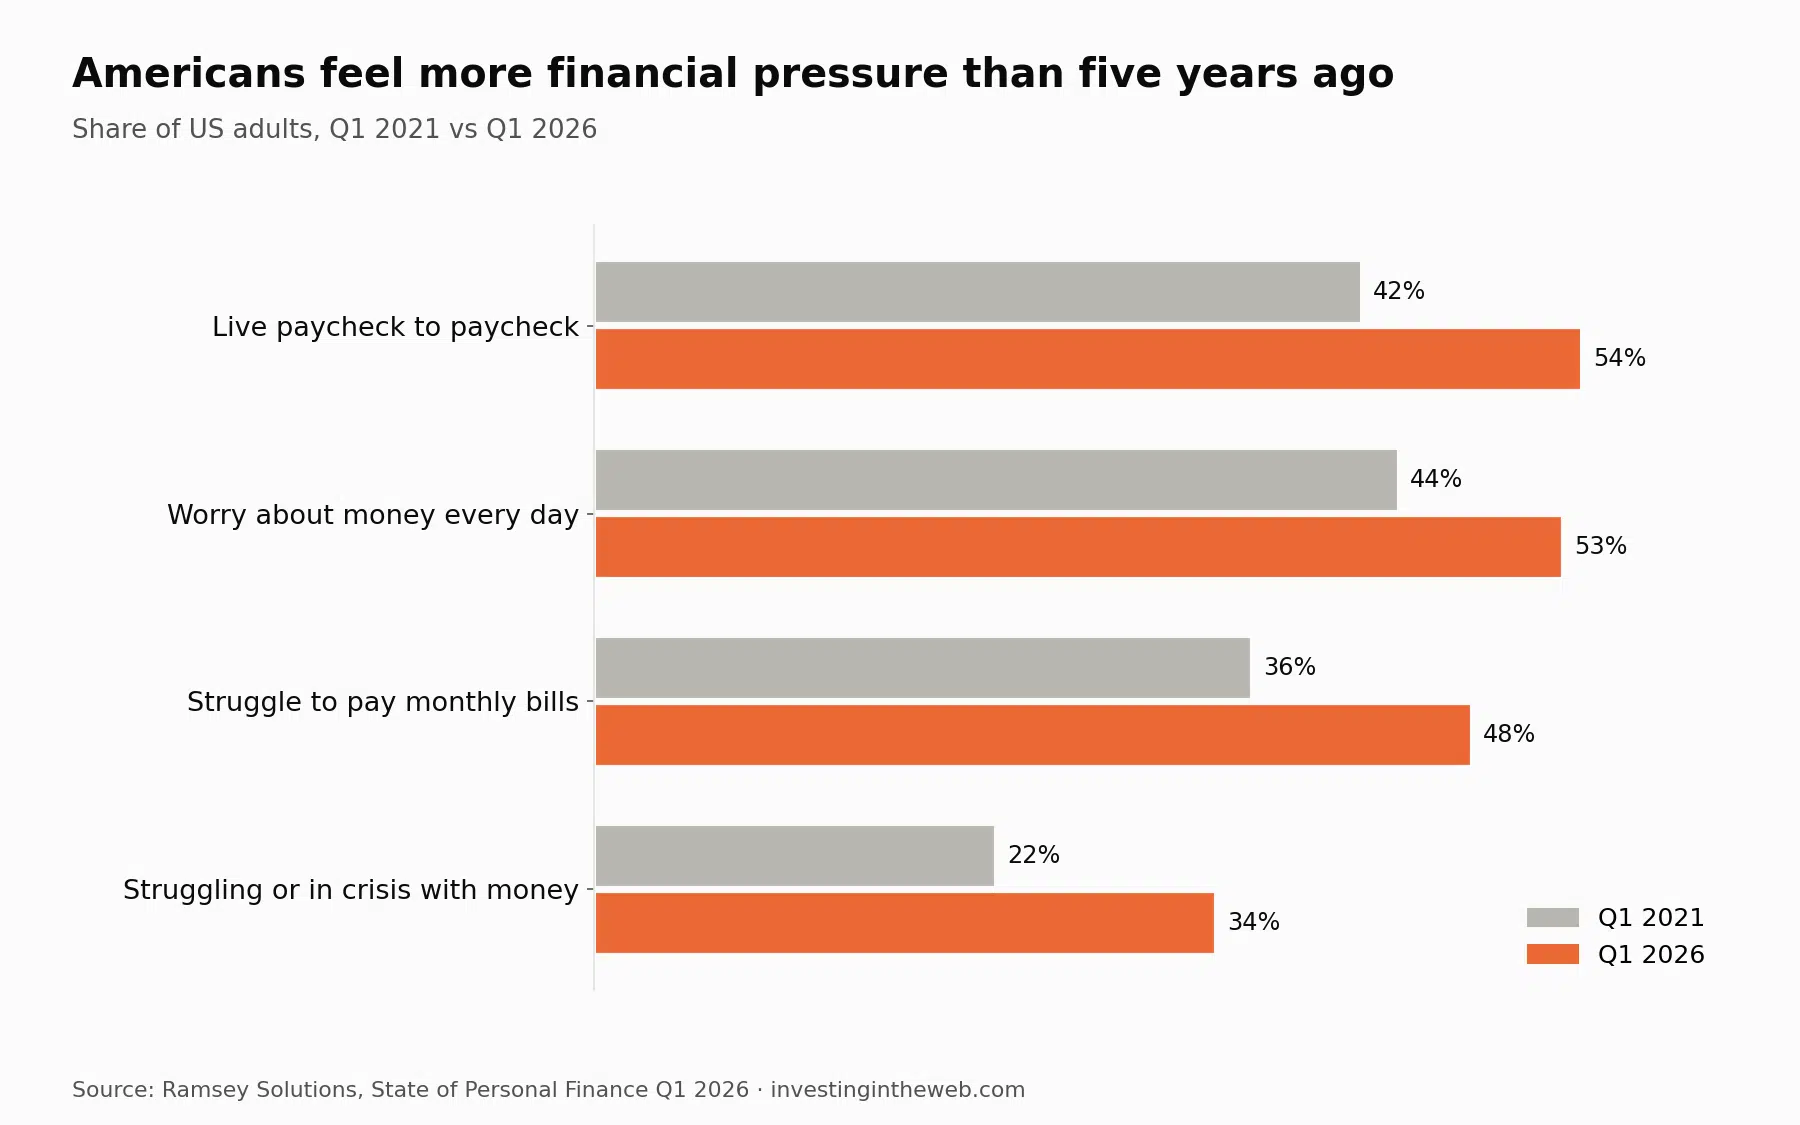
According to The State of Personal Finance by Ramsey Solutions, 34% of Americans said they were struggling or in crisis with their finances in Q1 2026, compared with 22% in Q1 2021.
Other measures of financial pressure have moved the same way over those five years:
- Living paycheck to paycheck: 54%, up from 42%.
- Worrying about money every day: 53%, up from 44%.
- Struggling to pay monthly bills: 48%, up from 36%.
Housing is a big part of the problem. 54% of renters say they struggle to pay rent, and 38% of homeowners say their mortgage payment causes them stress.
3. US women and single adults are the most financially vulnerable groups
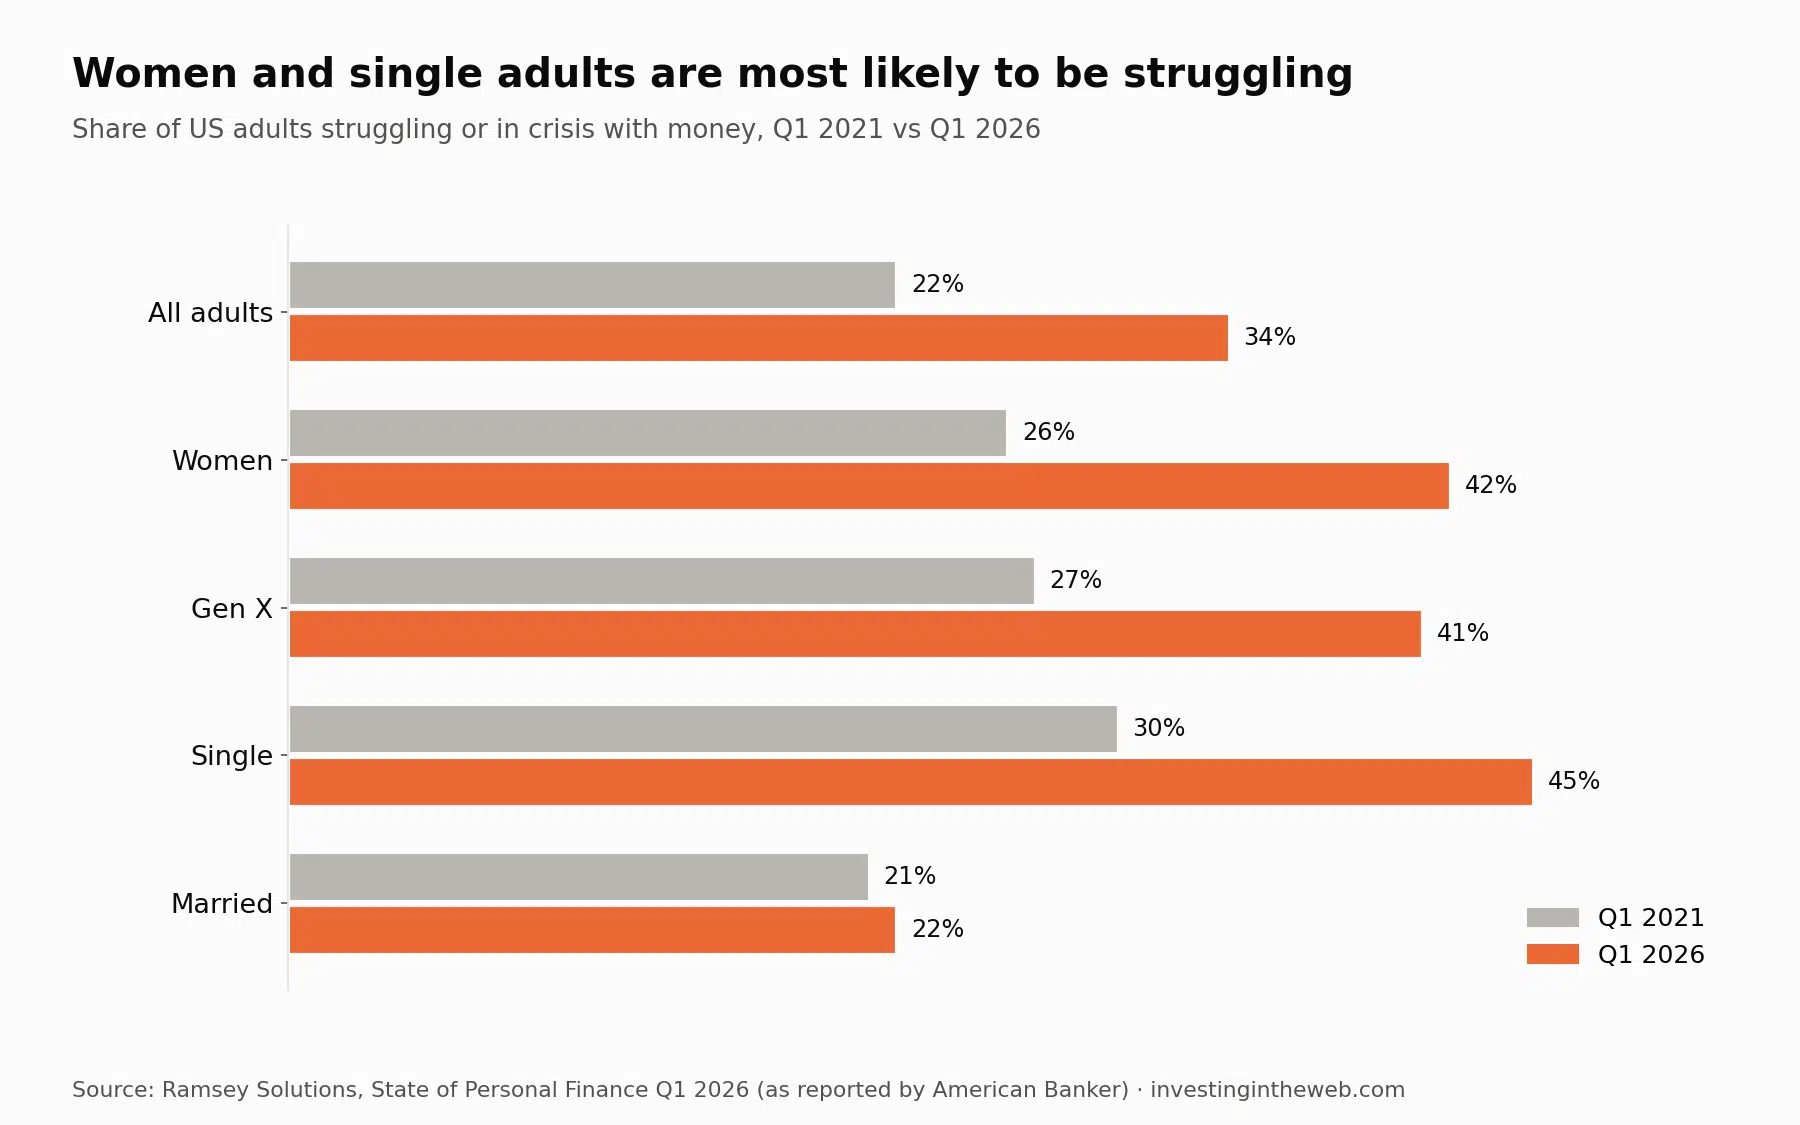
The same Ramsey Solutions survey, as reported by American Banker, shows that 42% of US women said they were struggling or in crisis with money in Q1 2026, up from 26% in 2021. We can only speculate on the factors behind this, such as the gender pay gap, financial abuse and differences in access to financial knowledge and services.
Single adults (45%, up from 30%) and Gen X (41%, up from 27%) also report high levels of financial struggle. Married adults are the most stable group, with 22% struggling compared with 21% in 2021.
Financial literacy and education
The road to better finances starts with financial education. It is probably the most effective and low-cost way each of us can improve our finances. As the following statistics show, the state of financial literacy in the world is worse than many of us would assume.
4. Only one in three adults worldwide is financially literate, with men slightly ahead of women
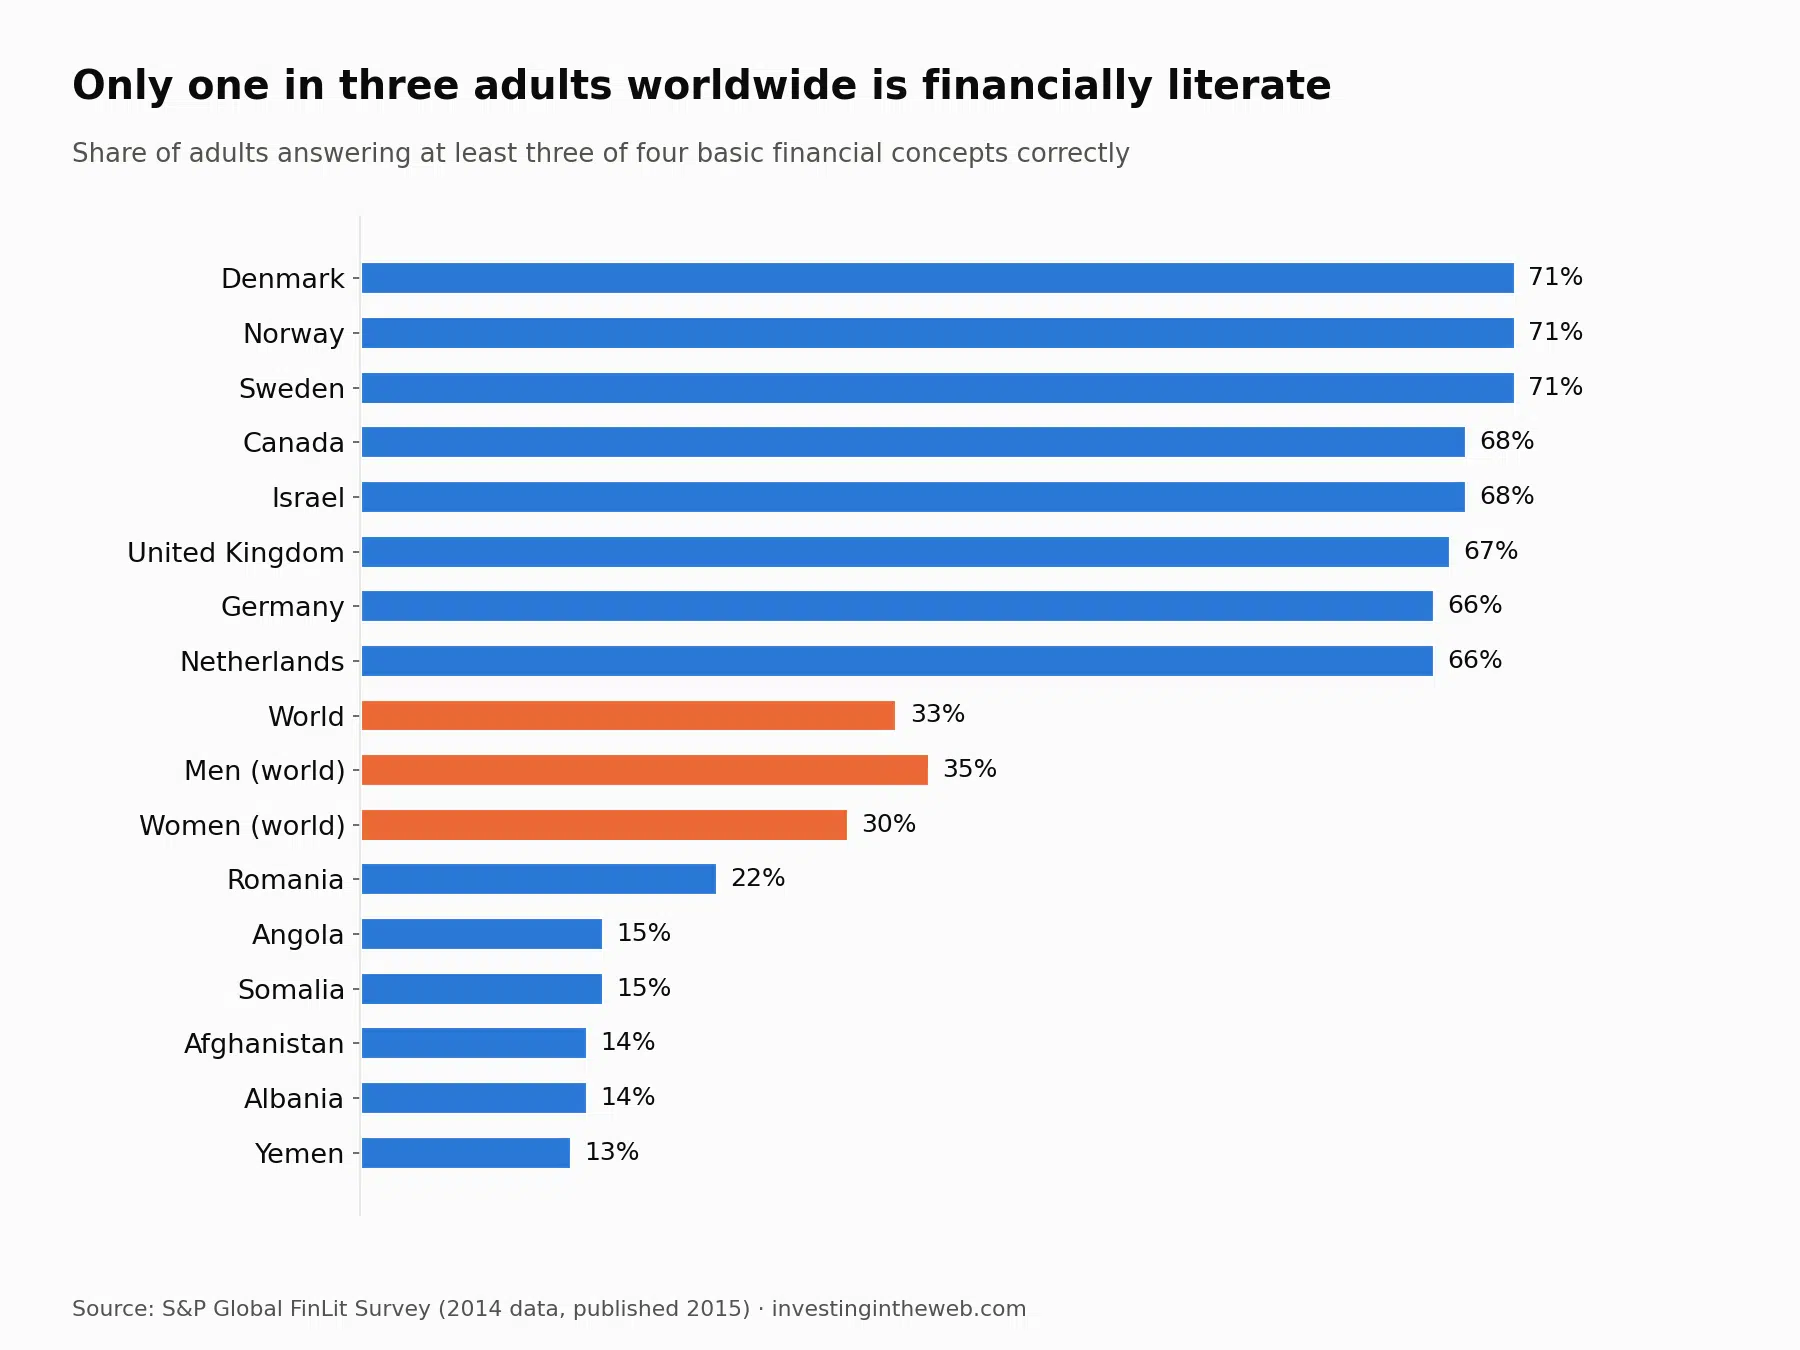
According to the S&P Global FinLit Survey, the most comprehensive global study of financial literacy (more than 150,000 adults in over 140 countries), only 33% of adults are financially literate. To count as financially literate, respondents had to correctly answer questions on at least three of four basic concepts: numeracy, risk diversification, compound interest and inflation.
Men were slightly more financially literate (35%) than women (30%).
More recent data points the same way. In the OECD/INFE 2023 survey of adult financial literacy (OECD stands for Organisation for Economic Co-operation and Development, and INFE for its International Network on Financial Education), the average score across 39 economies was 60 out of 100 (63 in OECD members), and only 34% of adults reached the minimum target score (39% in OECD members).
5. Denmark, Norway and Sweden are the most financially literate countries
With 71% of adults financially literate, Denmark, Norway and Sweden share the top spot in the S&P survey. Canada and Israel follow with 68%, then the UK with 67%, and Germany and the Netherlands with 66%.
At the other end, only 13% of adults in Yemen, 14% in Afghanistan and Albania, and 15% in Angola and Somalia are financially literate. Within the EU, Romania has the lowest rate (22%).
Income is one of the best predictors of financial literacy, both between countries and between groups of people within the same country.
6. Financial literacy peaks in middle age, and young Americans now score lowest
In advanced economies, the S&P survey found that 56% of adults aged 35 or younger were financially literate, rising to 63% of those aged 36 to 50, before declining in older age groups.
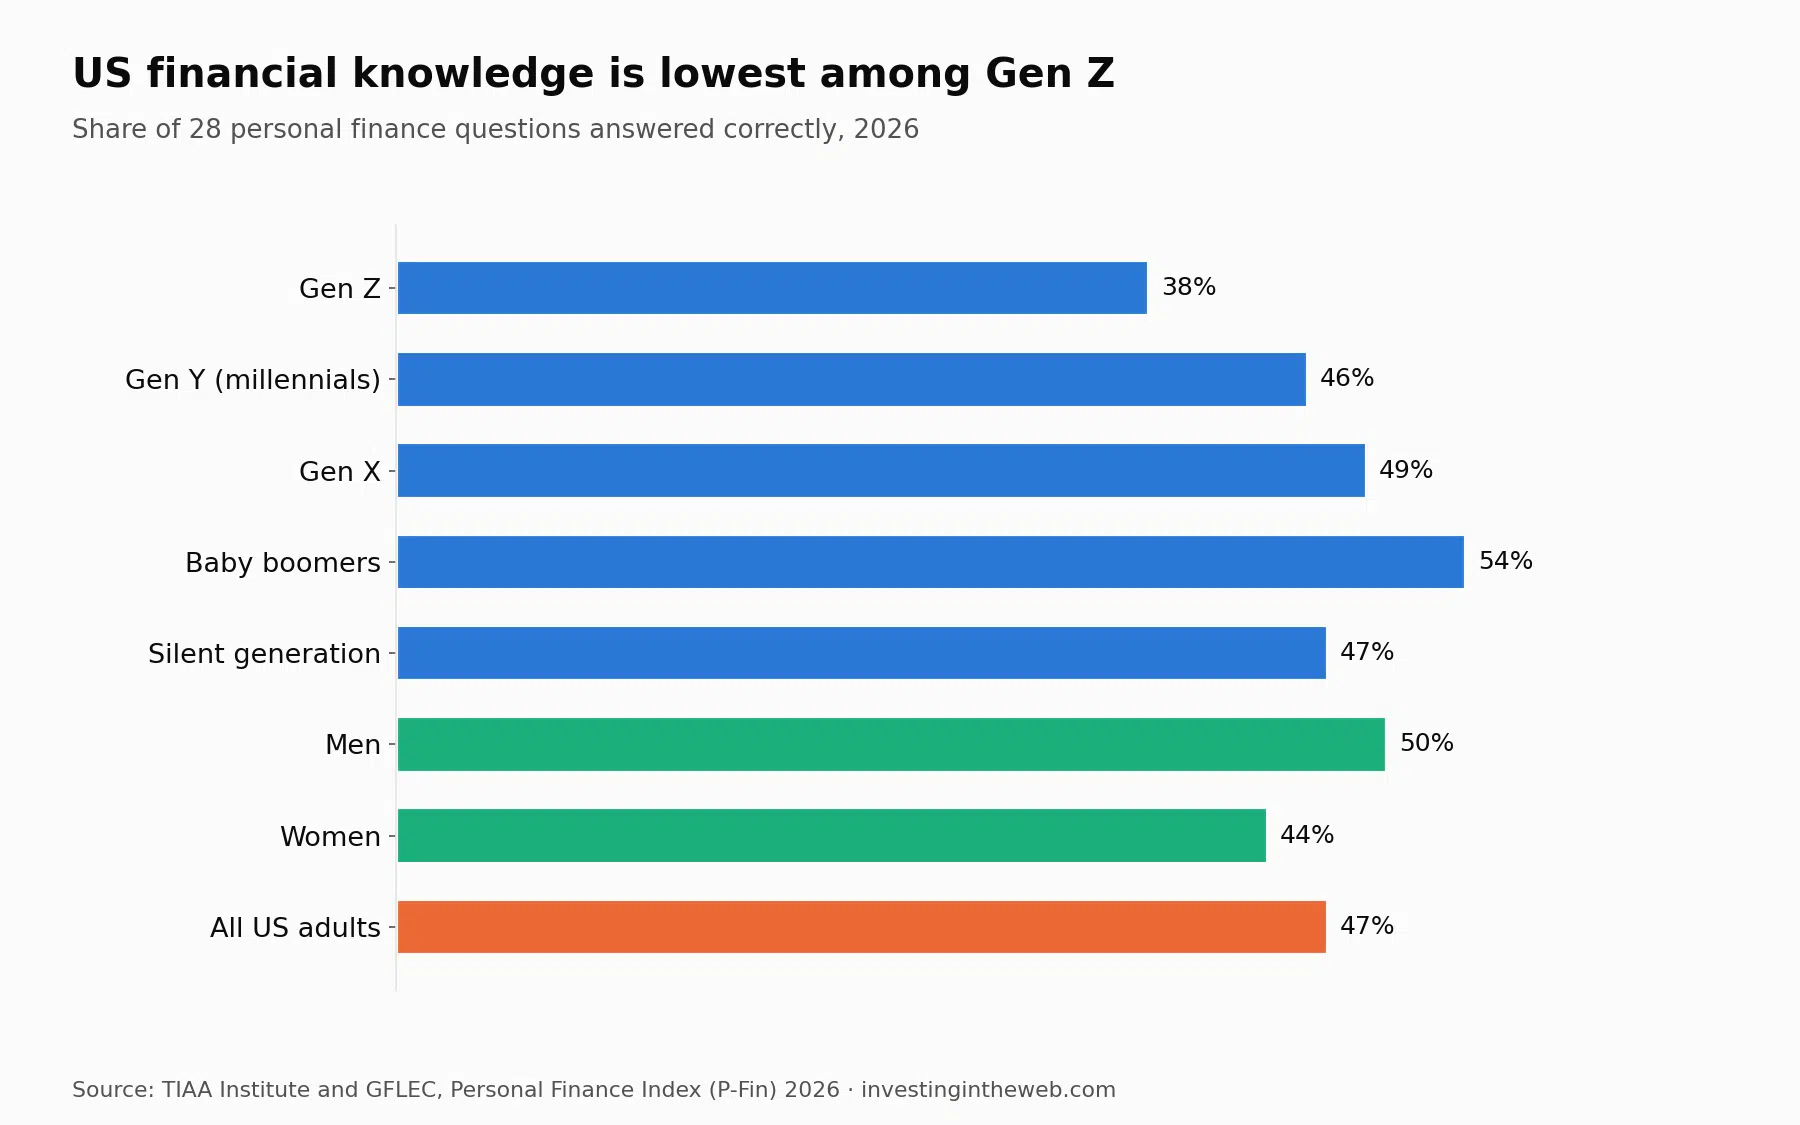
In the US, the 2026 Personal Finance Index (P-Fin) from the TIAA Institute and the Global Financial Literacy Excellence Center (GFLEC) shows a similar pattern. Americans answered only 47% of its questions correctly on average, the lowest score since the index began. Gen Z scored 38%, millennials 46%, Gen X 49%, baby boomers 54% and the Silent Generation 47%. Men (50%) again scored higher than women (44%).
7. Apart from age and income, direct experience predicts higher financial literacy
The S&P survey shows that, regardless of country, people who have a bank account, use credit or have lived through high inflation are more financially literate than others.
Experience, and especially negative experience, turns out to be a good teacher.
8. Only 30% of Americans would pay a $1,000 emergency expense from their savings
Low financial literacy often shows up as low financial resilience. According to a Bankrate survey published in January 2026, only 30% of US adults would cover an unexpected $1,000 expense with money from their savings. The rest would use a credit card, cut back on other spending, borrow or use other means.
A separate Bankrate survey from May 2025 found that 46% of Americans have at least three months of expenses saved, and only 27% have six months or more, the amount often recommended for an emergency fund.
Net worth
Income differences get most of the attention, but net worth is probably the best measure of financial wealth. As a reminder, net worth is the value of everything you own (real estate, cash, investments and so on) minus everything you owe (mortgage, loans and other debt).
9. Average wealth per adult ranges from about $660,000 in North America to far less in most other regions
The UBS Global Wealth Report 2026, which covers 56 markets, no longer publishes a single global average. Instead, it shows how much average wealth per adult varies by region at the end of 2025:
- North America: about $660,000.
- Australia and New Zealand: about $590,000.
- Western Europe: over $330,000.
Countries with high incomes, measured at purchasing power parity, usually have the highest net worth. However, taxes, access to financial markets, home prices and financial literacy also play a big role.
10. 42% of adults have less than $10,000, while about 57.5 million are US dollar millionaires
If we divide the world’s adults by net worth, 42.1% have less than $10,000 and another 41.1% have between $10,000 and $100,000, according to the same UBS report. At the top, about 57.5 million people are US dollar millionaires, or 1.5% of adults.
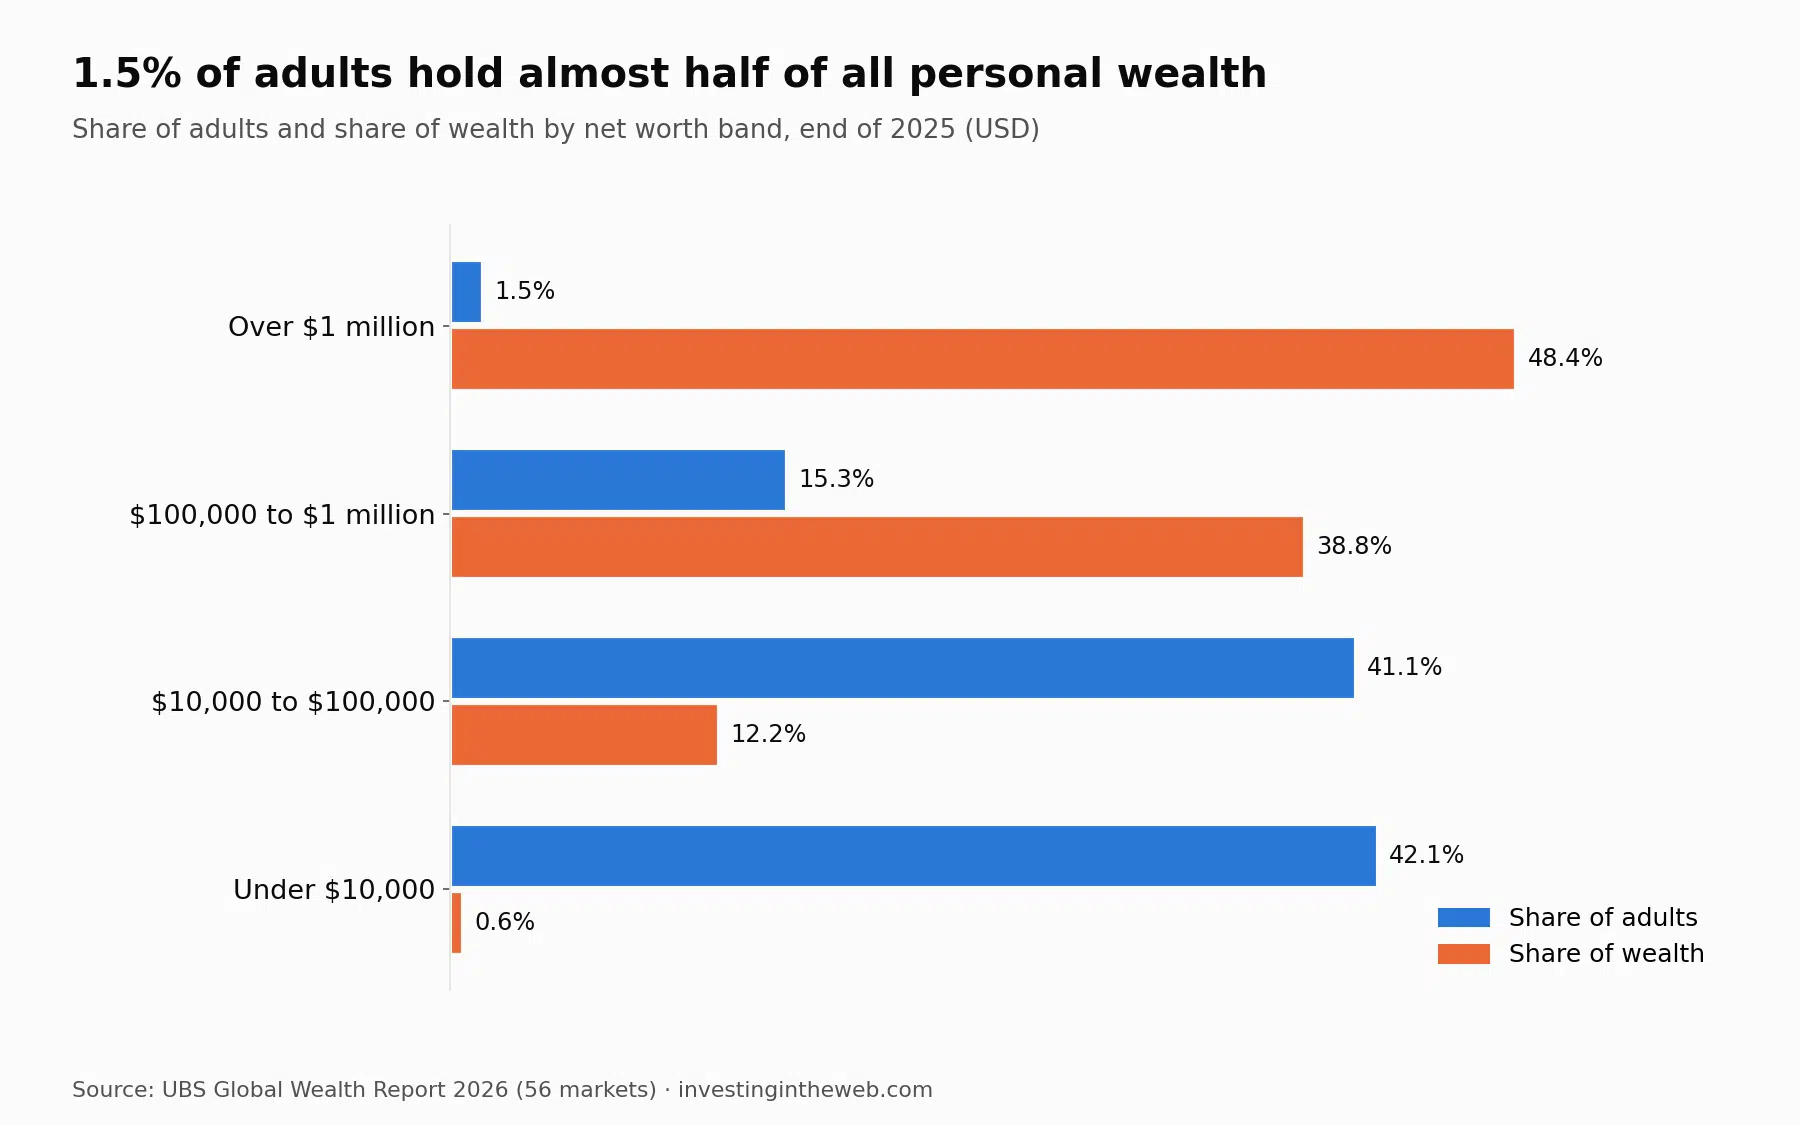
This means that if your net worth is over $100,000, you are among the wealthiest 17% of adults on the planet.
11. Fewer people are at the bottom of the wealth pyramid, but 1.5% of adults hold 48.4% of all wealth
The share of adults with less than $10,000 has fallen from about three quarters in 2000 to around 42% at the end of 2025, largely thanks to rapid wealth growth in China and other emerging markets. UBS expects the $10,000 to $100,000 group to overtake the under $10,000 group before the end of the decade.
Despite that, wealth remains very concentrated. The 1.5% of adults with more than $1 million hold 48.4% of all personal wealth, while the 42.1% with less than $10,000 hold just 0.6%.
12. Switzerland has the highest average wealth per adult, but Luxembourg has the highest median
According to the UBS report, Switzerland has the highest mean (average) wealth per adult in the world, at about $910,000. The US follows at about $696,000.
The median, the wealth of the adult in the exact middle, gives a better picture of the typical person because a few very wealthy people do not pull it up. Here, countries with a more even distribution of wealth lead, with Luxembourg first at about $394,000. The US median is only about $69,000, roughly a tenth of its mean.
| Rank | Country | Mean wealth per adult |
| 1. | Switzerland | $910,382 |
| 2. | United States | $696,277 |
| 3. | Luxembourg | $654,732 |
| 4. | Hong Kong | $648,267 |
| 5. | Australia | $616,306 |
Highest mean wealth per adult, end of 2025. Source: UBS Global Wealth Report 2026
| Rank | Country | Median wealth per adult |
| 1. | Luxembourg | $394,005 |
| 2. | Belgium | $277,166 |
| 3. | Australia | $210,783 |
| 4. | New Zealand | $206,617 |
| 5. | Denmark | $203,771 |
Highest median wealth per adult, end of 2025. Source: UBS Global Wealth Report 2026
13. The US is home to more than 40% of the world’s millionaires
About 23.6 million of the world’s US dollar millionaires live in the United States, more than 40% of the global total. China is a distant second with about 5.3 million, followed by Japan (2.9 million), Germany (2.6 million), the UK and France (2.4 million each).
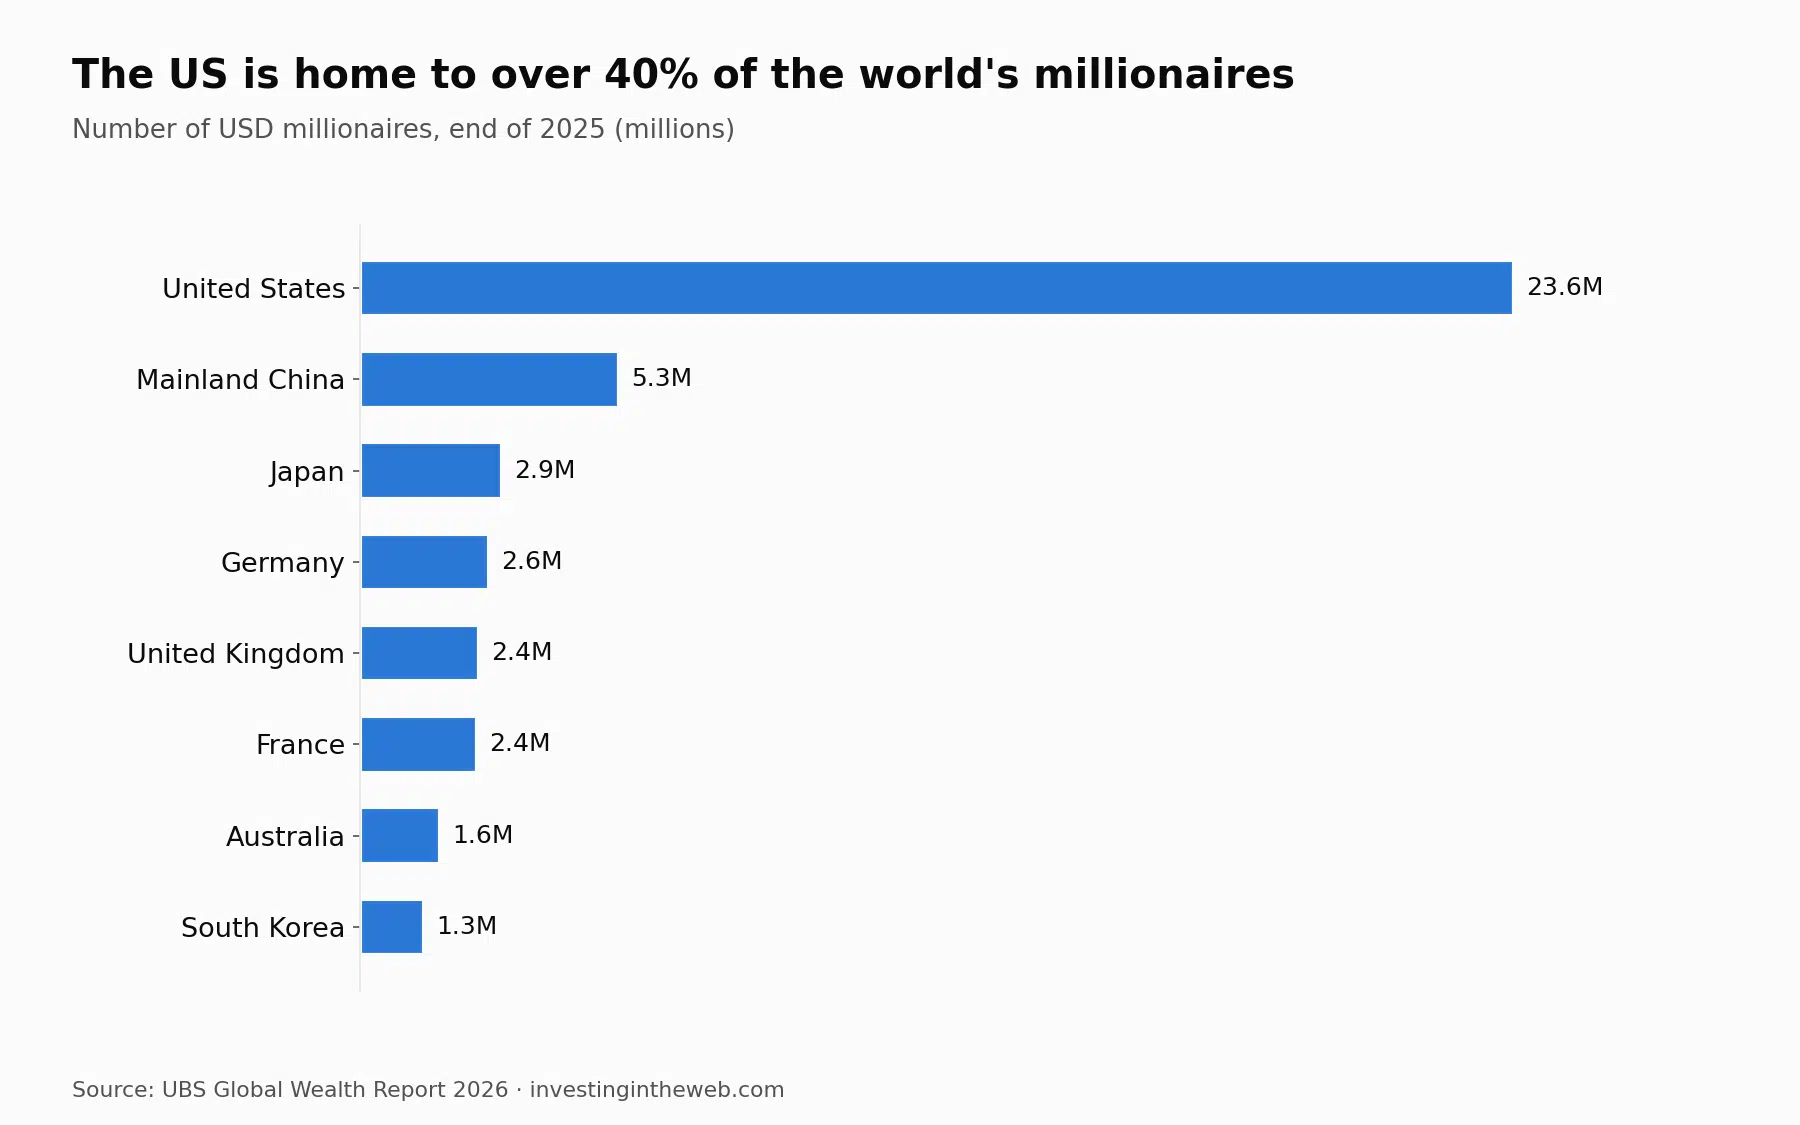
The US lead is partly a result of its large population and deep financial markets, which allowed stock market gains to lift household wealth over the past decade.
14. US net worth rises with age, and the median keeps climbing into the 75+ age group
According to the latest Survey of Consumer Finances (SCF) from the Federal Reserve, published in October 2026 with 2025 data, net worth rises steadily with age. More time means more total income and more years for compound growth to work.
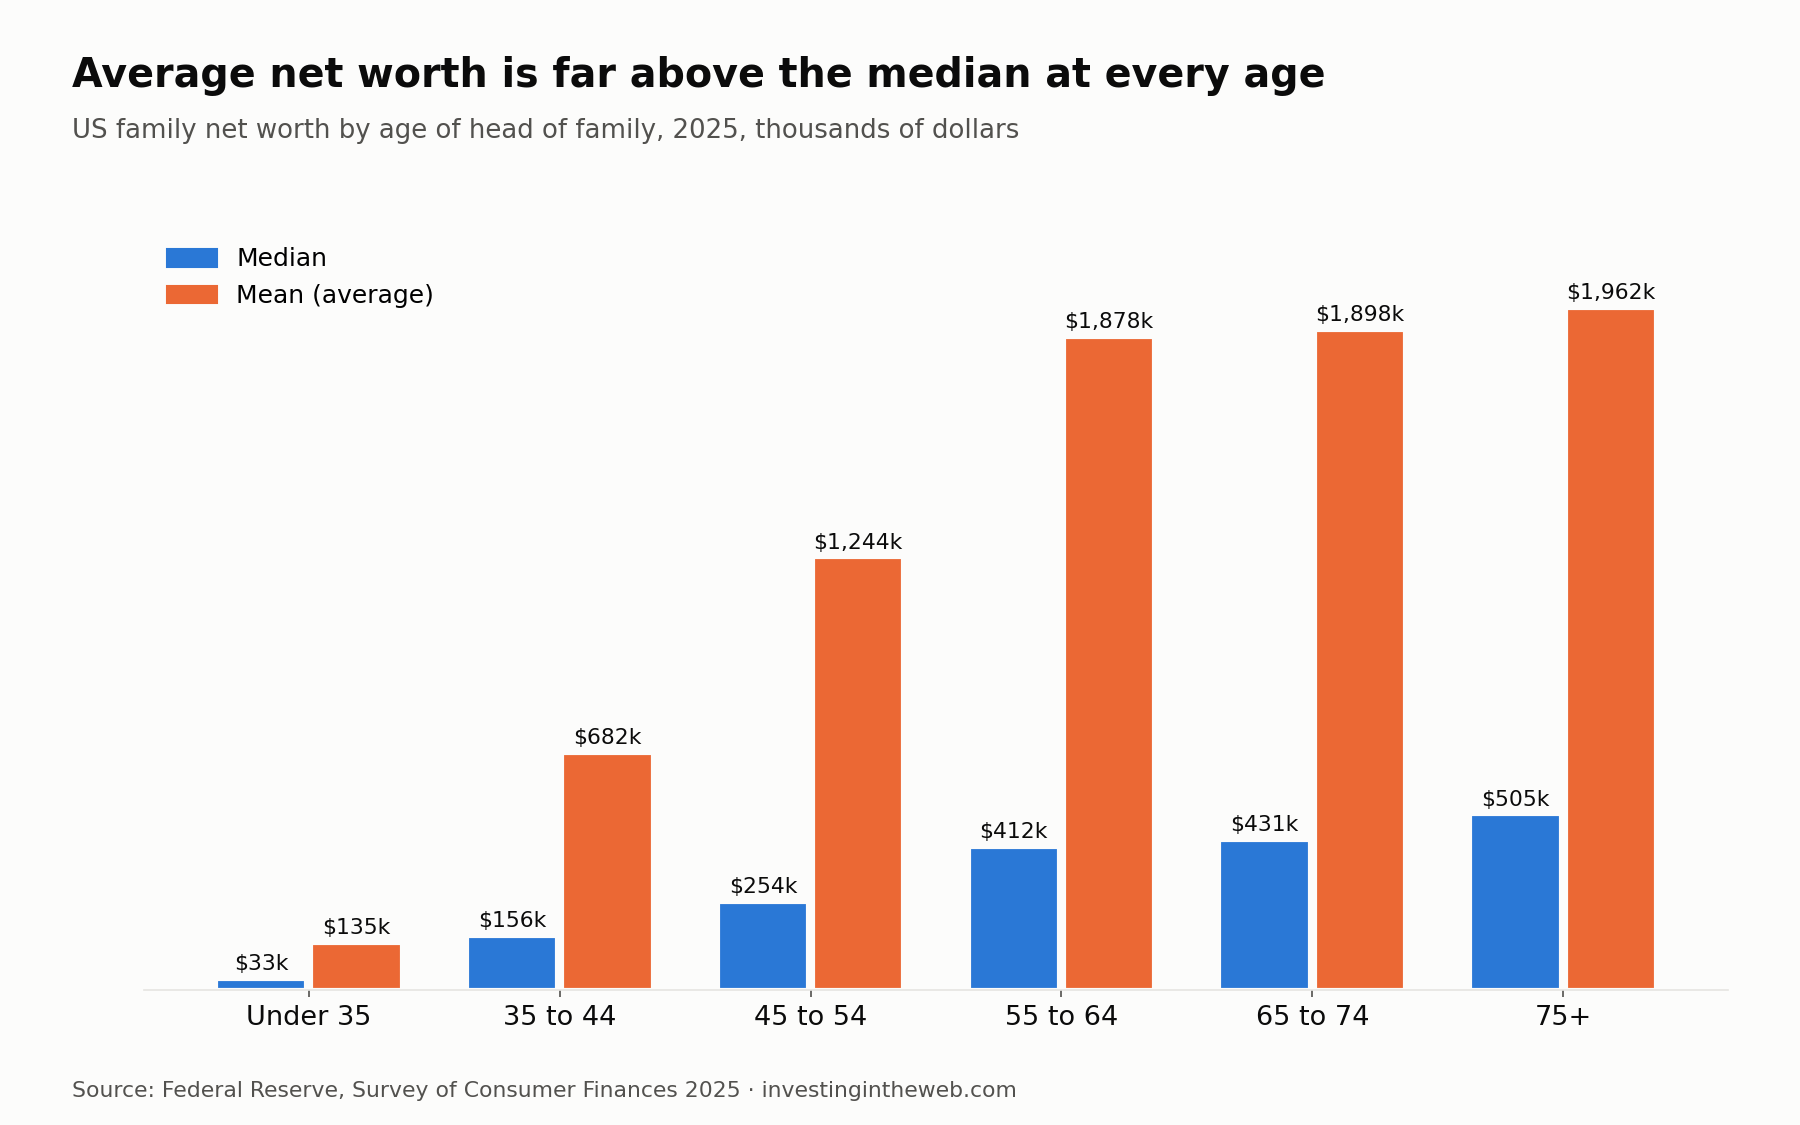
The median US family headed by someone under 35 has a net worth of about $33,000. That rises to about $412,000 for ages 55 to 64 and about $505,000 for those aged 75 and over. Across all families, the median is about $216,000 and the mean about $1.24 million.
The gap between the mean and the median is large at every age, as a relatively small number of very wealthy families pull the average up.
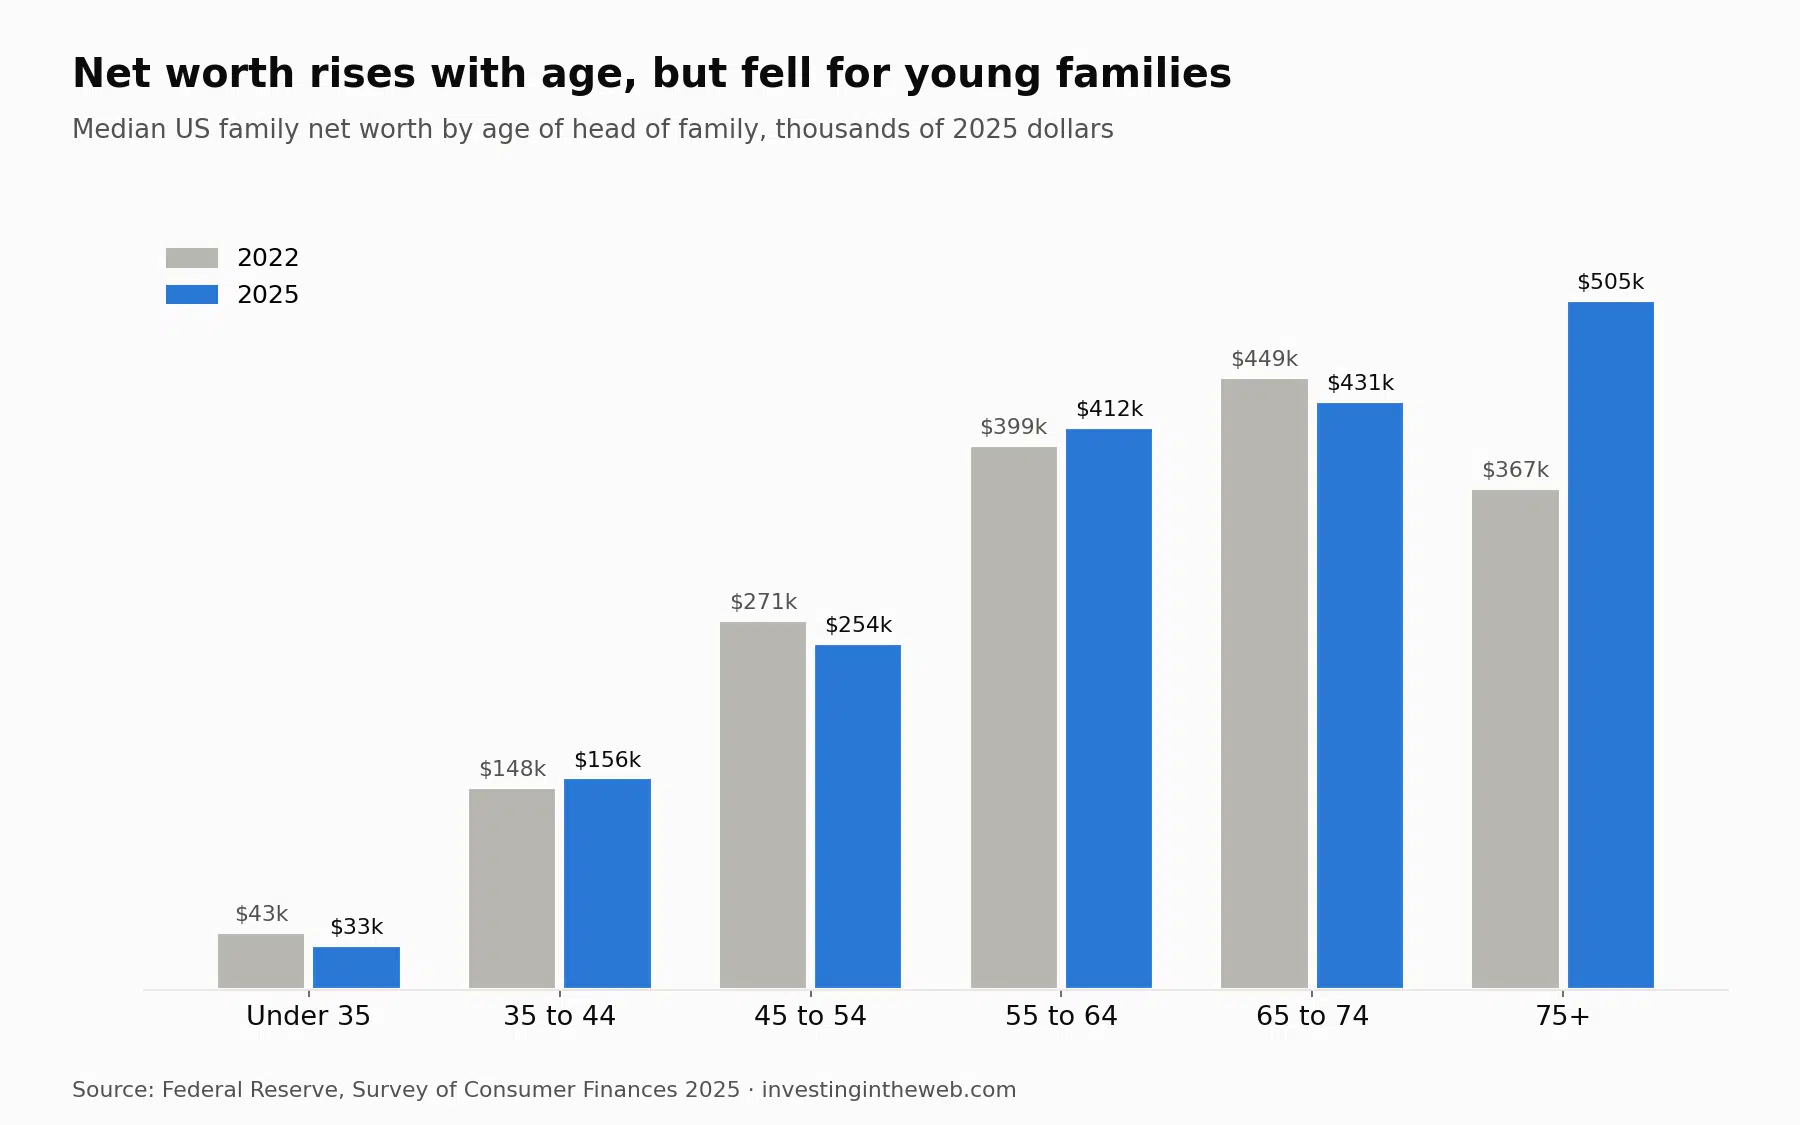
15. The median net worth of young US families fell 23% between 2022 and 2025
The same SCF report shows that not every age group gained over the last three years. After adjusting for inflation, the median net worth of families headed by someone under 35 fell from about $42,700 in 2022 to $33,000 in 2025, a drop of 23%.
Older families moved the other way. The median for families aged 75 and over rose by about 37%, from about $367,000 to $505,000, helped by higher stock and home values that younger families are less likely to own.
16. Global wealth grew 10.8% in 2025, and emerging markets now hold about a quarter of it
According to the UBS Global Wealth Report 2026, global wealth grew 10.8% in 2025 in US dollar terms, helped by strong stock markets and a weaker dollar.
Emerging markets held only about 8% of global wealth in 2000. Their share peaked at about 29% in 2022 and stood at about 26% at the end of 2025. Over the long term, this shift is one of the main reasons global wealth inequality between countries has declined.
Income
17. Small, wealthy economies have the highest GDP per capita at purchasing power parity
As we saw in the previous statistics, income is one of the most reliable predictors of financial literacy and wealth. Let’s look at how income is distributed across and within countries.
According to the International Monetary Fund (IMF) World Economic Outlook from April 2026, small economies lead the world in gross domestic product (GDP) per capita adjusted for purchasing power parity:
| Rank | Country | GDP per capita, PPP (2026, international dollars) |
| 1. | Liechtenstein | 195,372 |
| 2. | Singapore | 173,708 |
| 3. | Ireland | 159,129 |
| 4. | Luxembourg | 156,719 |
| 5. | Macao SAR | 140,423 |
IMF estimates for 2026. Source: IMF World Economic Outlook, April 2026
Keep in mind that these figures may overstate what residents actually earn. Small countries with favourable tax rules attract large companies and wealthy individuals, and in places like Ireland and Luxembourg, profits of multinationals and cross-border workers push GDP well above household income.
If we look past small countries, the top of the list is filled with the usual names, such as Western European countries and the US.
18. Income inequality is lowest in Central and Eastern Europe and highest in southern Africa
The Gini index measures income inequality on a scale from 0 (everyone has the same income) to 100 (one person has all the income). Here is how selected countries compare, using the latest World Bank data:
| Country | Gini index (income inequality) | Year of data |
| South Africa | 54.1 | 2022 |
| United States | 41.8 | 2024 |
| Germany | 33.7 | 2022 |
| United Kingdom | 32.4 | 2021 |
| Czechia | 25.7 | 2023 |
| Slovenia | 24.7 | 2023 |
| Belarus | 24.4 | 2020 |
| Slovakia | 23.8 | 2023 |
Countries sorted from highest to lowest income inequality. Source: World Bank, Gini index (SI.POV.GINI)
Low inequality in Nordic countries may not surprise many, but Slovakia, Slovenia, Czechia and Belarus have even lower Gini scores. Their more compressed wage structures are partly a legacy of their economic history.
The US, on the other hand, has one of the highest levels of income inequality among developed countries. At the very top of the list are southern African countries, with South Africa the most unequal country in the World Bank data.
19. US household income hit a record in 2025, but the middle class keeps shrinking
According to the US Census Bureau, the median US household income was $87,460 in 2025, up 2.6% from 2024 after adjusting for inflation and the highest on record. The Census Bureau’s own Gini index for household income stood at 0.490 (on a 0 to 1 scale), which is high for a developed country.
At the same time, the share of Americans in the middle class has been falling for decades. According to the Pew Research Center, 61% of US adults lived in middle-income households in 1971, compared with 51% in 2023. The share in upper-income households rose from 11% to 19%, and the share in lower-income households from 27% to 30%.
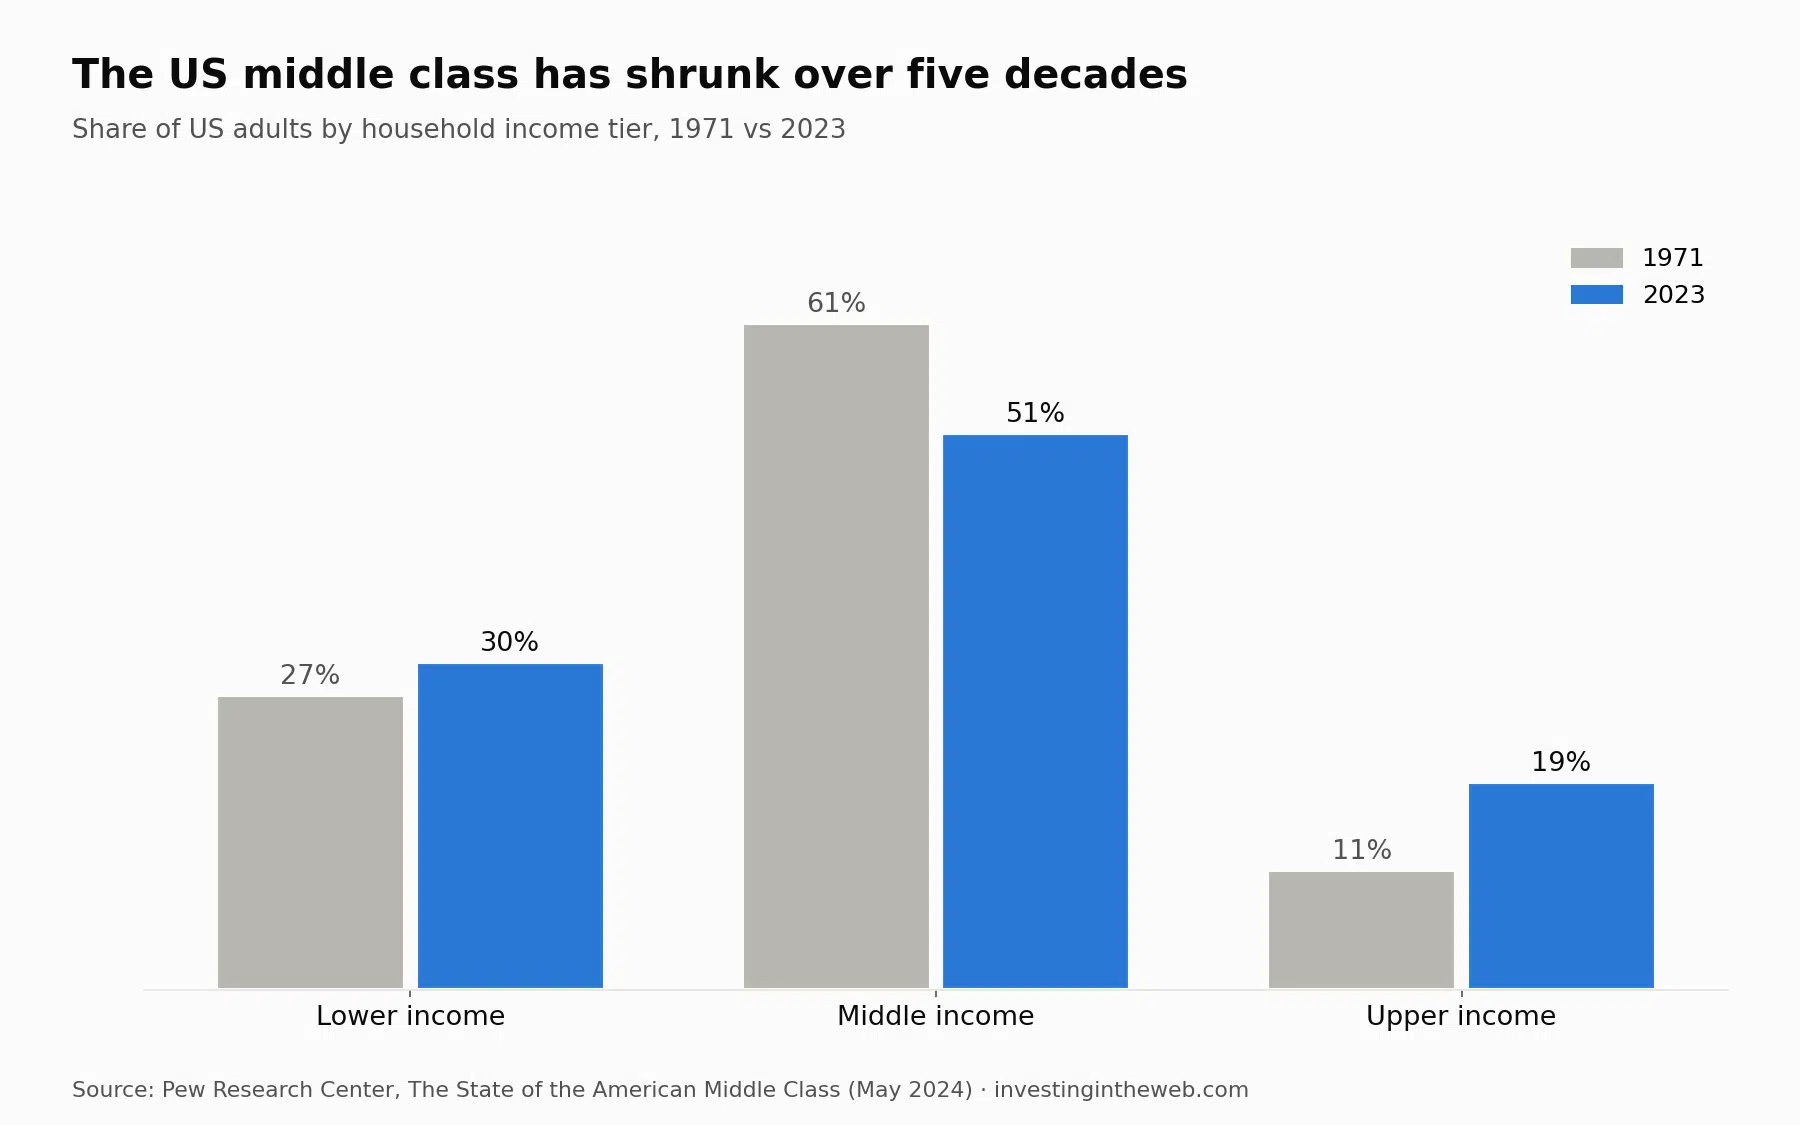
In other words, more people moved up than down, but the gap between the top and the rest has widened.
Inflation
It is always better to focus on what we can control, such as budgeting, saving and managing debt. Some factors, however, are completely outside our control.
The biggest of these is inflation. After reaching its highest levels since the 1970s and 1980s in 2022, inflation fell sharply in most of the world in 2023 and 2024 before picking up again in 2026.
20. Inflation has picked up again in 2026 after falling close to central bank targets
According to the latest official data, annual inflation measured by the consumer price index (CPI) was 3.1% in the UK (August 2026), 3.8% in the euro area (September 2026 flash estimate), 3.4% in the US (August 2026) and 0.8% in China (August 2026). You can track these figures in tools such as Koyfin.
| Year | UK | Euro area | US | China |
| 2022 | 9.1% | 8.4% | 8.0% | 2.0% |
| 2023 | 7.3% | 5.4% | 4.1% | 0.2% |
| 2024 | 2.5% | 2.4% | 2.9% | 0.2% |
| 2025 | 3.4% | 2.1% | 2.6% | 0.0% |
| Latest (2026) | 3.1% | 3.8% | 3.4% | 0.8% |
Annual average consumer price inflation. Sources: ONS (UK CPI), Eurostat (euro area HICP), BLS (US CPI), National Bureau of Statistics of China
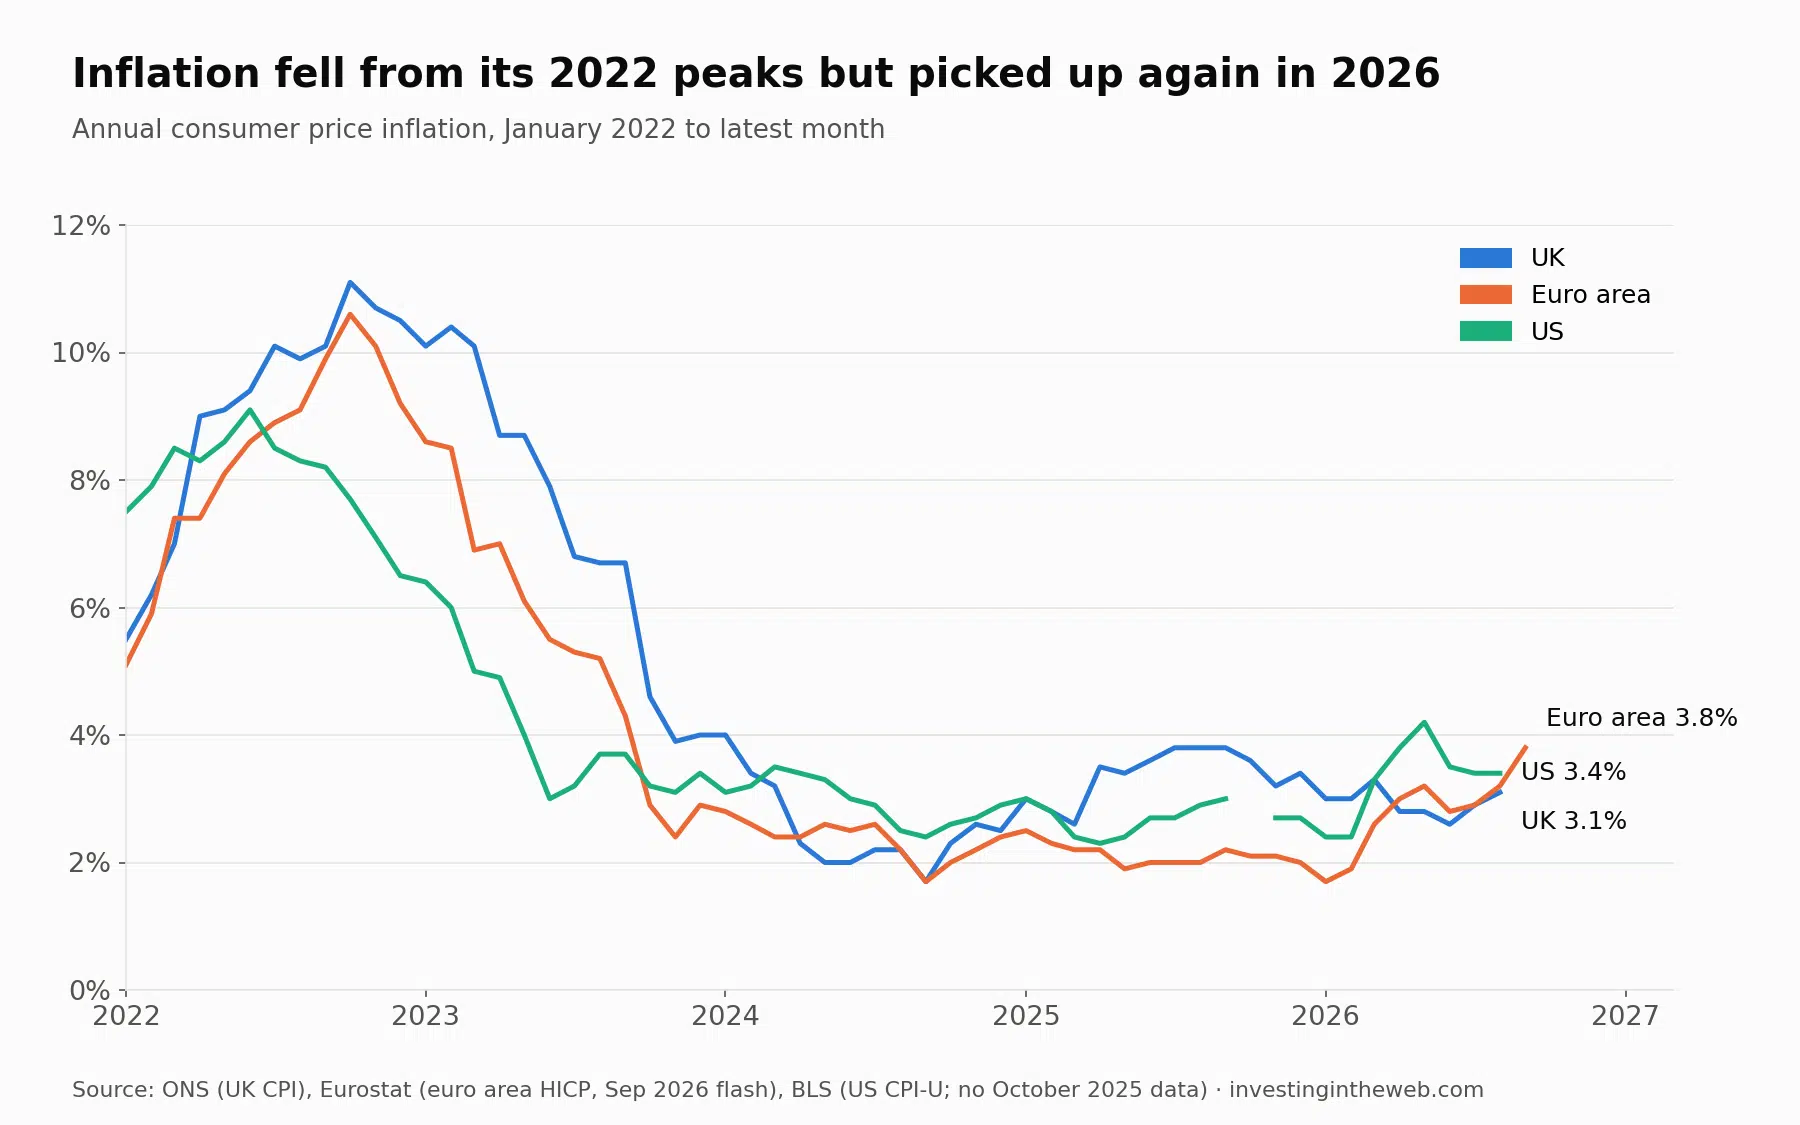
Inflation has also proved more persistent than many expected. In its July 2026 update, the IMF projected global inflation of 4.7% for 2026.
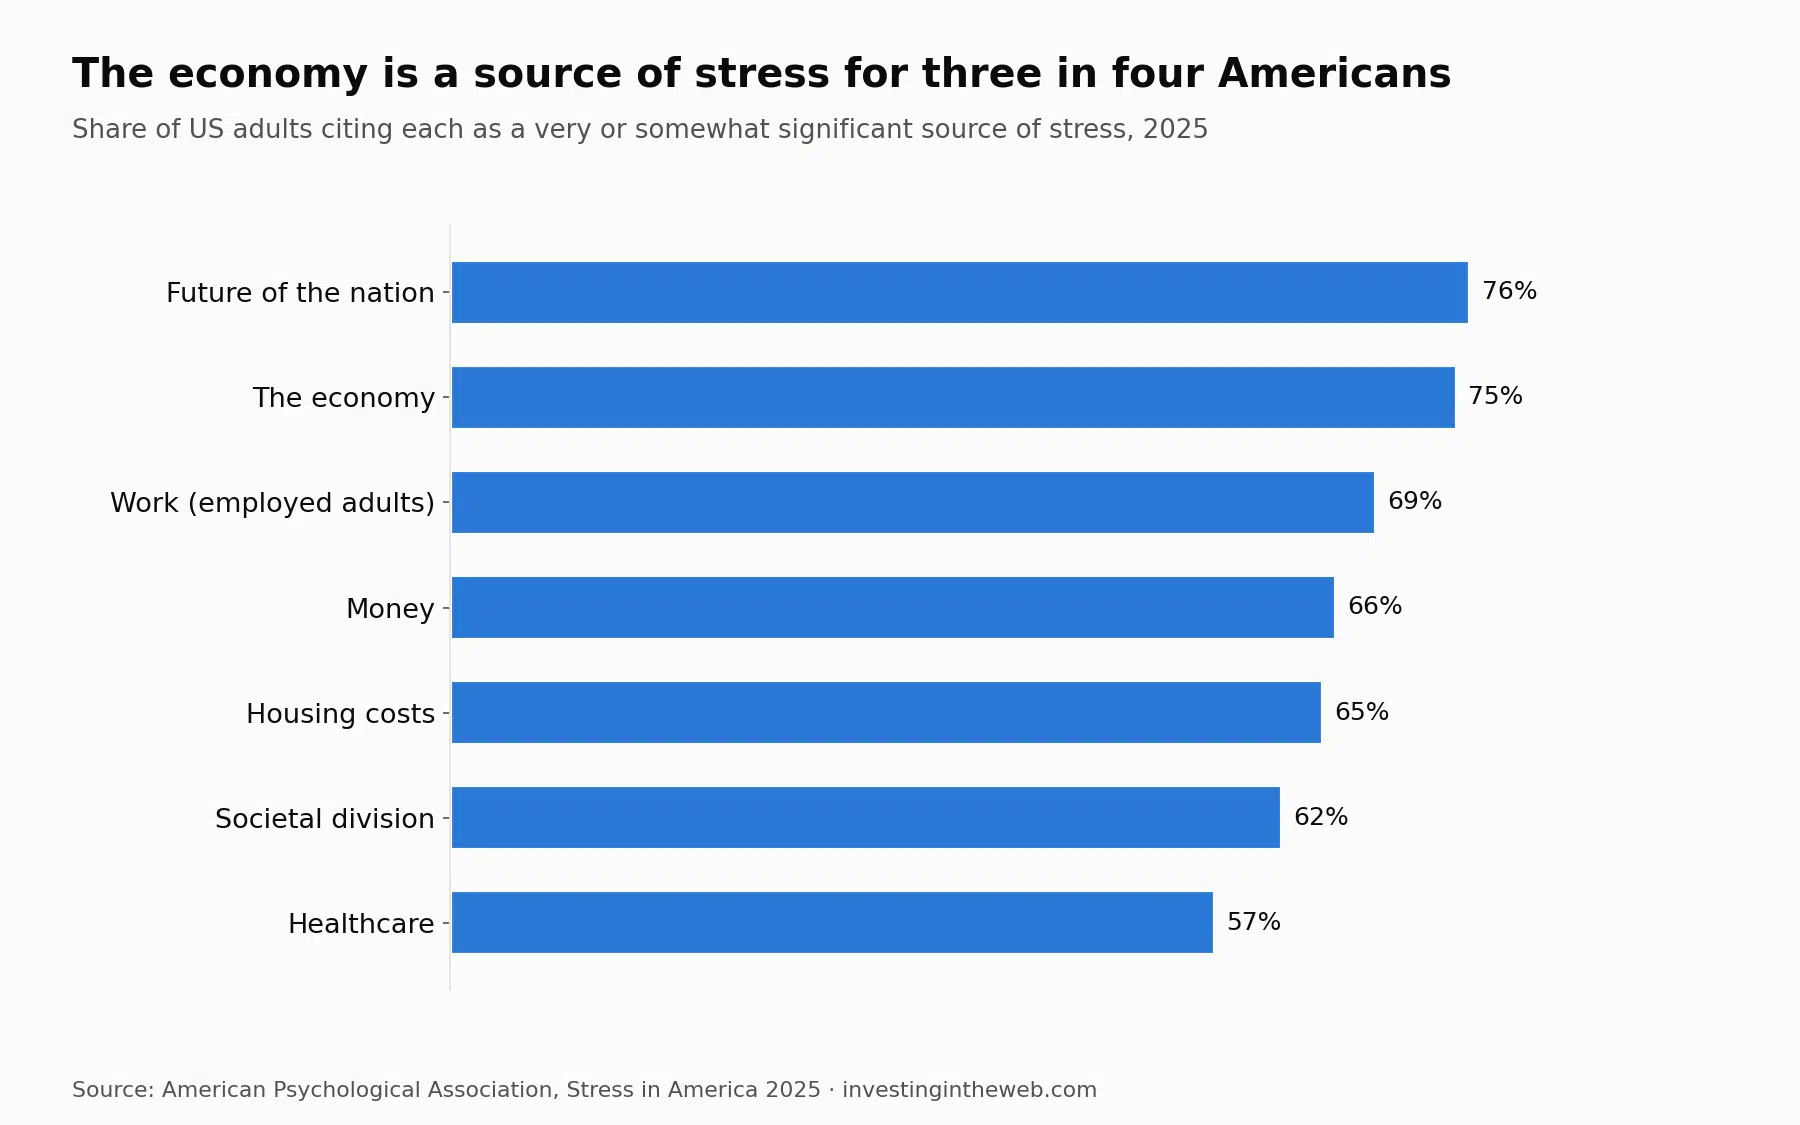
21. Three in four American adults cite the economy as a source of stress
According to the American Psychological Association’s Stress in America 2025 survey, 75% of US adults say the economy is a significant source of stress. Money (66%) and housing costs (65%) are close behind, while the future of the nation tops the list at 76%.
Financial worries are closely tied to the cost of living, so these numbers are unlikely to fall much while inflation stays above target.
Real estate
Real estate is one of the oldest asset classes and wealth-building tools in human history. Culture, regulation and taxes seem to play as large a role as income in how many people own their home.
22. Homeownership is higher in the EU than in the US or England, but varies widely between countries
According to Eurostat, 68.5% of people in the EU lived in a home owned by their household in 2025. That compares with 65.0% of US households in Q2 2026 according to the US Census Bureau and 65% of households in England according to the English Housing Survey for 2024 to 2025.
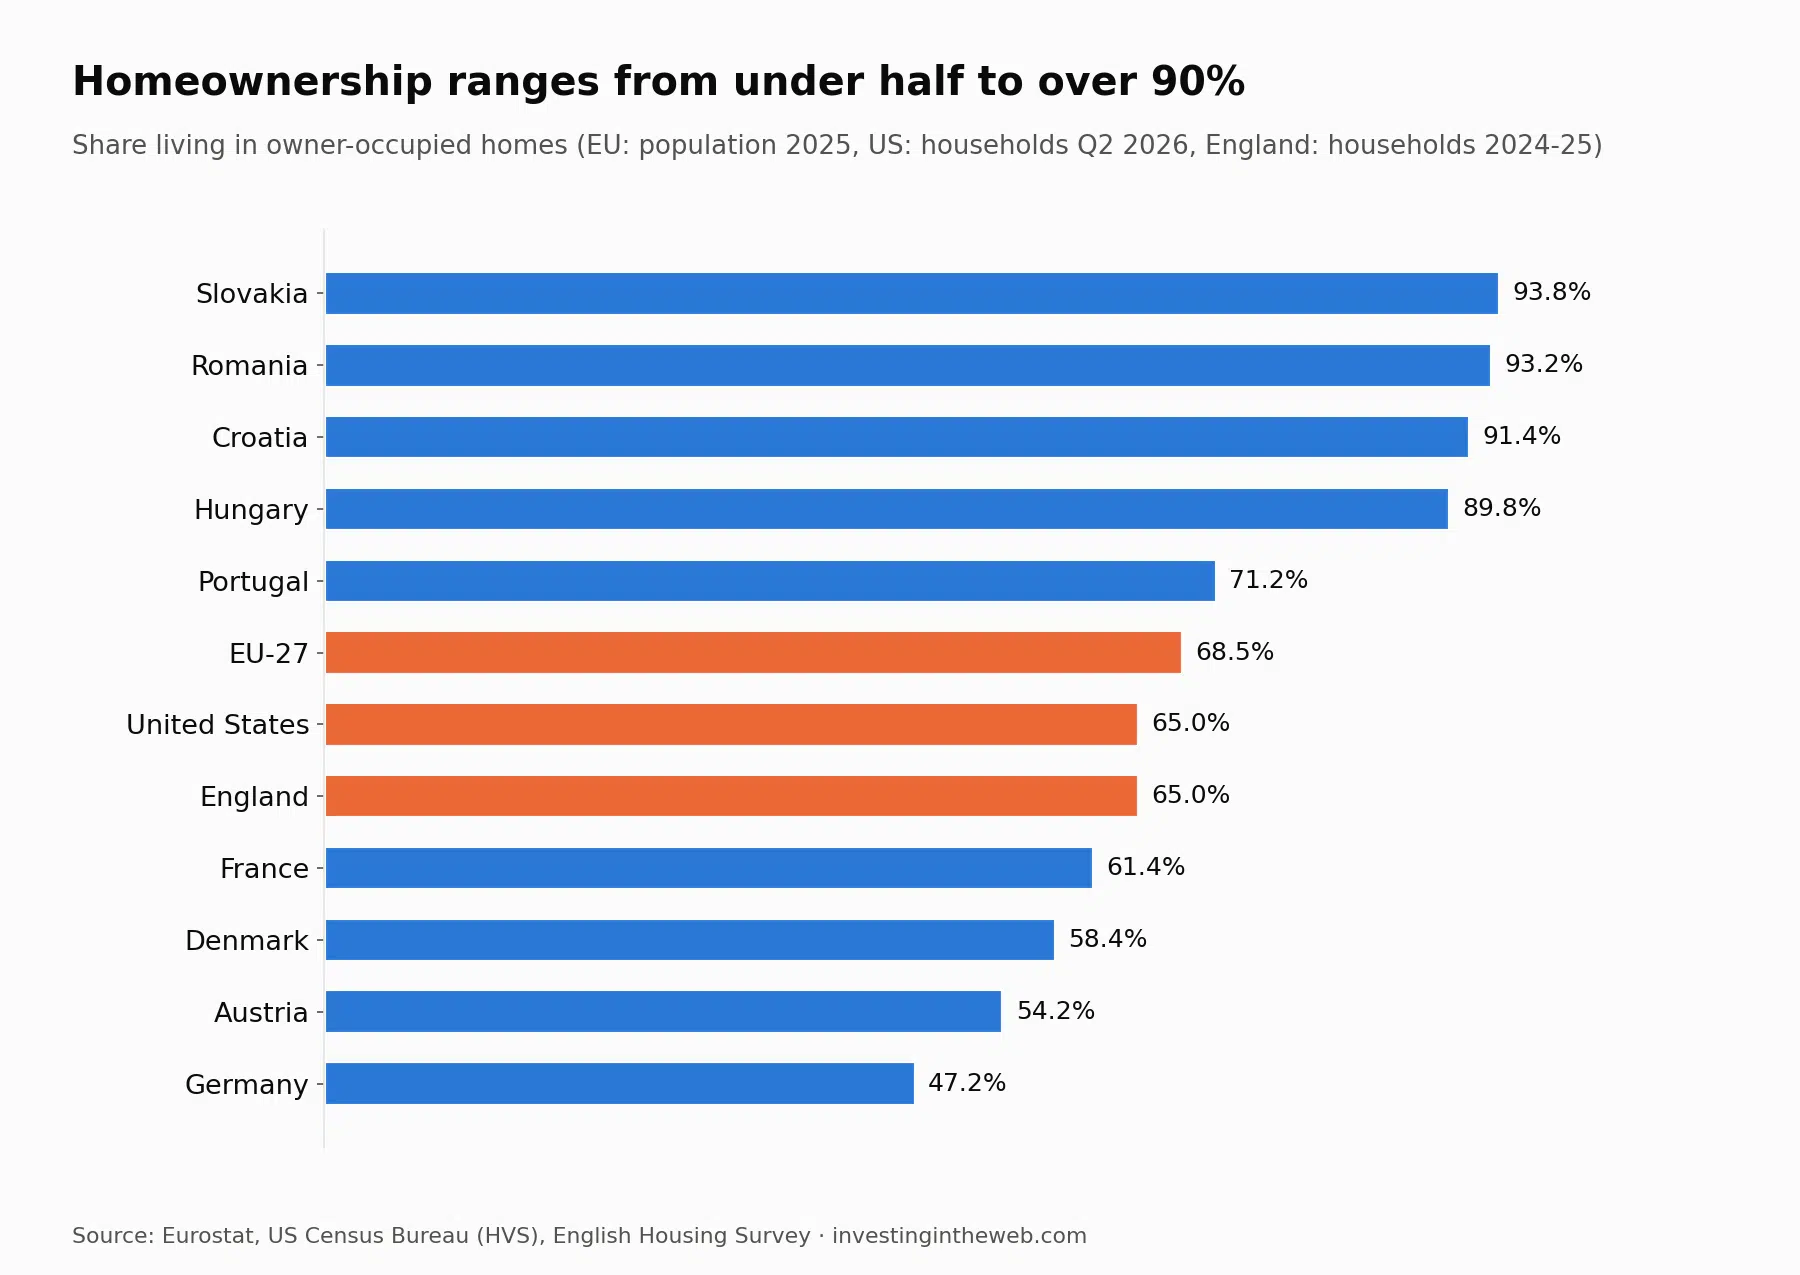
The differences within the EU are huge. Southern and Eastern European countries tend to have very high ownership rates, led by Slovakia (93.8%), Romania (93.2%), Croatia (91.4%) and Hungary (89.8%). In Western and Northern Europe, renting is much more common: France is at 61.4%, Denmark at 58.4%, Austria at 54.2% and Germany has the lowest rate in the EU at 47.2%. Portugal is close to the EU average at 71.2%.
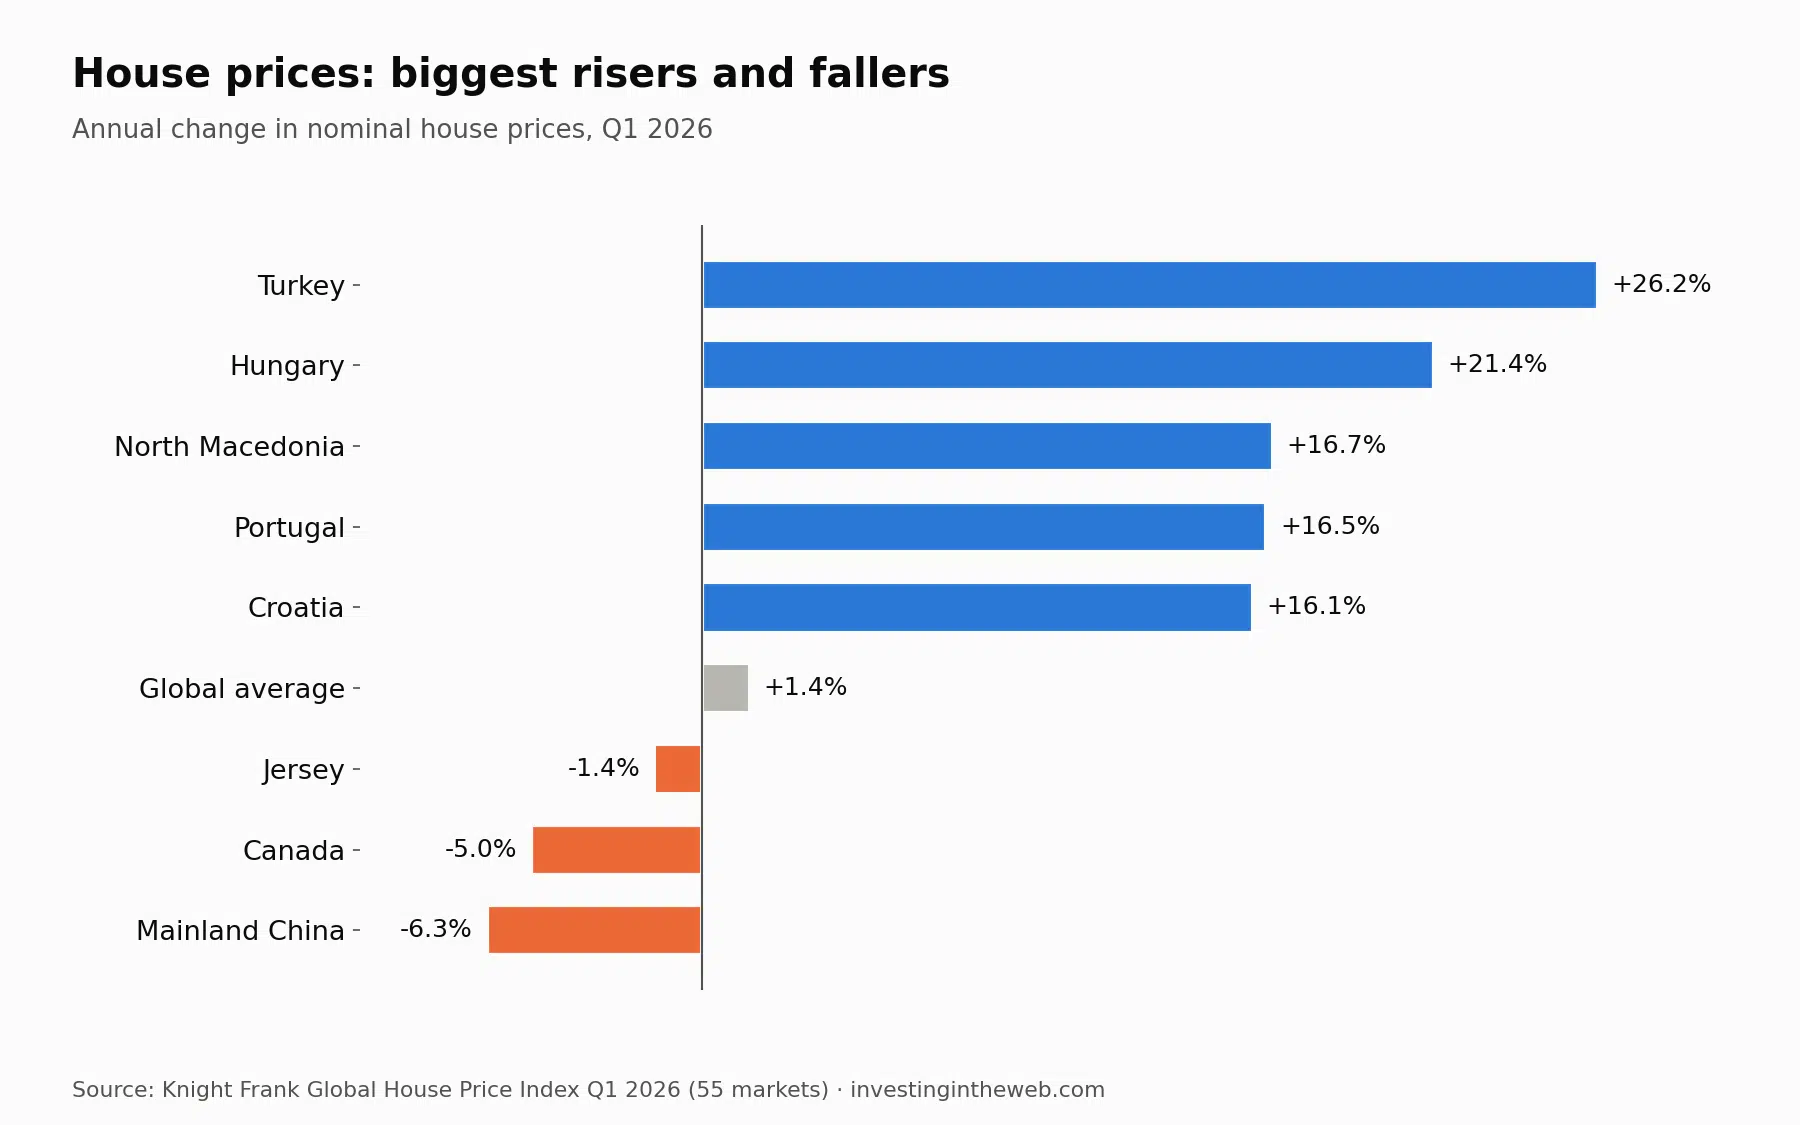
23. House prices rose the most in Turkey and Central Europe and fell the most in China in early 2026
According to the Knight Frank Global House Price Index, average house prices across 55 markets rose 1.4% in the year to Q1 2026.
Turkey led with nominal growth of 26.2%, although high inflation means real prices grew far less. Hungary (21.4%), North Macedonia (16.7%), Portugal (16.5%) and Croatia (16.1%) followed.
Only a few markets saw prices fall. Mainland China had the biggest decline (6.3%), followed by Canada (5.0%) and Jersey (1.4%).
24. US home prices have more than tripled since 2000
According to the S&P Cotality Case-Shiller US National Home Price Index, US home prices in July 2026 were about 3.4 times their level in January 2000. Together with higher mortgage rates, this has made housing much less affordable for the average American.
Price growth has slowed considerably, though. In the year to July 2026, the index rose only 1.9%, below the rate of inflation.
Conclusion
Personal finance trends have gone through many ups and downs in recent years. Inflation, higher interest rates and housing costs have put pressure on households in most countries, and many people feel worse off than a few years ago.
However, if we step back and look at the bigger picture, the world is on average much better off financially than a few decades ago. Extreme poverty has fallen by more than three quarters since 1990, and the share of adults with very little wealth has dropped sharply since 2000.
Future growth and a fair distribution of wealth and income are not guaranteed, though. The first step each of us can take is to improve our own financial literacy and habits.
Raising your income, budgeting, building an emergency fund, managing debt, planning for retirement and investing for the long term go a long way in improving your finances over time.