



Bonds have regained their appeal as an income-generating asset after several years of interest rate rises. A 6-month US Treasury bill yielded just 0.22% at the start of 2022. In early October 2026, the same bill yields about 4.3% and the 10-year Treasury about 5.3%, a meaningful shift for fixed-income investors.
While US residents can buy Treasuries directly through TreasuryDirect, the route is less straightforward for Canadian investors. The good news is that it remains entirely possible to invest in US Treasury bonds from Canada, through the secondary market or through ETFs.
In this article, we provide a step-by-step guide on how Canadian investors can invest in US Treasury bonds, including T-bills and T-notes. We also cover the currency and tax considerations that apply, which matter more than most guides acknowledge.
What are US Treasury bonds?
US Treasury bonds are debt securities issued by the United States Department of the Treasury to finance government operations and public spending. Backed by the full faith and credit of the US government, they are widely regarded as among the safest investments available.
Treasuries carry a fixed interest rate with maturities ranging from a few weeks to thirty years. They are sold at auction and can be bought by individuals, corporations, and foreign governments. Interest is exempt from US state and local taxes, though this is of no relevance to Canadian investors, who are taxed under Canadian rules rather than US state law.
Treasury bonds vs Treasury notes vs Treasury bills
All three are issued by the US Treasury, differing principally in maturity:
- Treasury bills (T-bills): maturities of one year or less, sold at a discount to face value rather than paying periodic interest. Your return is the difference between purchase price and face value at maturity.
- Treasury notes (T-notes): maturities of 2 to 10 years, paying interest every six months.
- Treasury bonds (T-bonds): maturities of 20 to 30 years, also paying interest every six months.
Here is what each type of Treasury yielded in early October 2026, compared with the start of 2022:
| Maturity | Yield (2 Oct 2026) | Yield (3 Jan 2022) |
| 3-month bill | 4.19% | 0.08% |
| 6-month bill | 4.27% | 0.22% |
| 2-year note | 4.83% | 0.78% |
| 10-year note | 5.28% | 1.63% |
| 30-year bond | 5.63% | 2.01% |
US Treasury par yields. Source: US Department of the Treasury.
One point worth understanding before choosing: longer maturities carry greater interest rate risk. If rates rise after you buy, the market value of a 30-year bond falls far more than that of a 6-month bill. Investors holding long-dated Treasuries through the 2022 rate-hiking cycle experienced double-digit losses despite holding what is often described as a risk-free asset. You avoid that price risk only if you hold an individual bond to maturity.
How to buy US Treasury bonds from Canada
US residents can invest directly through TreasuryDirect.gov. Canadian residents are not eligible to open an account there, since it requires a US Social Security number, a US address and a US bank account, so the practical options are buying on the secondary market or investing through bond ETFs.
Two considerations specific to Canadian investors before covering the mechanics:
- Currency risk: Treasuries are denominated in US dollars. Your actual return combines the bond yield with the CAD/USD movement over your holding period. A 4% yield can be entirely offset by a 5% move in the exchange rate, so consider whether you want that exposure or would prefer a CAD-hedged ETF, several of which are listed in Canada.
- Tax treatment: interest from Treasuries held directly is not subject to US withholding tax for non-resident investors under the portfolio interest exemption, provided a valid W-8BEN is on file, and the Canada-US tax treaty also sets a 0% rate on interest. The income remains fully taxable in Canada as interest income (including the discount on T-bills), at your marginal rate rather than at the more favourable capital gains rate.
A further point on account type. Because Treasury interest is taxed at your full marginal rate, it is usually best held inside a registered account such as an RRSP or TFSA. If you use US-listed ETFs rather than individual bonds, an RRSP is generally more efficient than a TFSA, since the Canada-US tax treaty exempts RRSPs from US withholding on fund distributions but does not extend the same treatment to TFSAs.
Foreign reporting: if the total cost of your specified foreign property, which includes US Treasuries and US-listed ETFs held outside registered accounts, exceeds CAD 100,000 at any time in the year, you must file Form T1135 with the CRA. Canadian-listed ETFs are not included.
Note that many Canadian brokers do not support individual US Treasuries. Wealthsimple, for example, only offers bond ETFs, while bank brokerages such as RBC Direct Investing and TD Direct Investing offer some US-dollar bonds through their fixed income desks, with the cost built into the quoted price. We therefore focus on Interactive Brokers below.
Option 1: buy US Treasury bonds on the secondary market
Interactive Brokers allows you to invest in T-bills and Treasury bonds on the secondary market. Treasury markets are highly liquid with tight spreads, and IBKR charges a commission of 0.002% of face value on the first $1 million (minimum $5) per trade, and Treasuries can be traded almost around the clock on weekdays.
Interactive Brokers offers access to over 1 million bonds, spanning US government securities, corporate bonds, and municipals. The Bond Scanner tool lets you filter by maturity, yield and credit quality.
Since bonds are classified as complex instruments, you will need to request bond trading permission (“Bonds, United States”) in your IBKR account settings before placing a trade. This is straightforward but must be done in advance.
Interactive Brokers Canada is a member of the Canadian Investment Regulatory Organization (CIRO) and the Canadian Investor Protection Fund (CIPF), offers RRSP, TFSA and FHSA accounts, and supports CAD as a base currency. Converting CAD to USD costs just 0.002% of the amount (minimum USD 2), which matters since you will need US dollars to buy Treasuries.
Here is an example of a US Treasury listing on IBKR’s web platform:
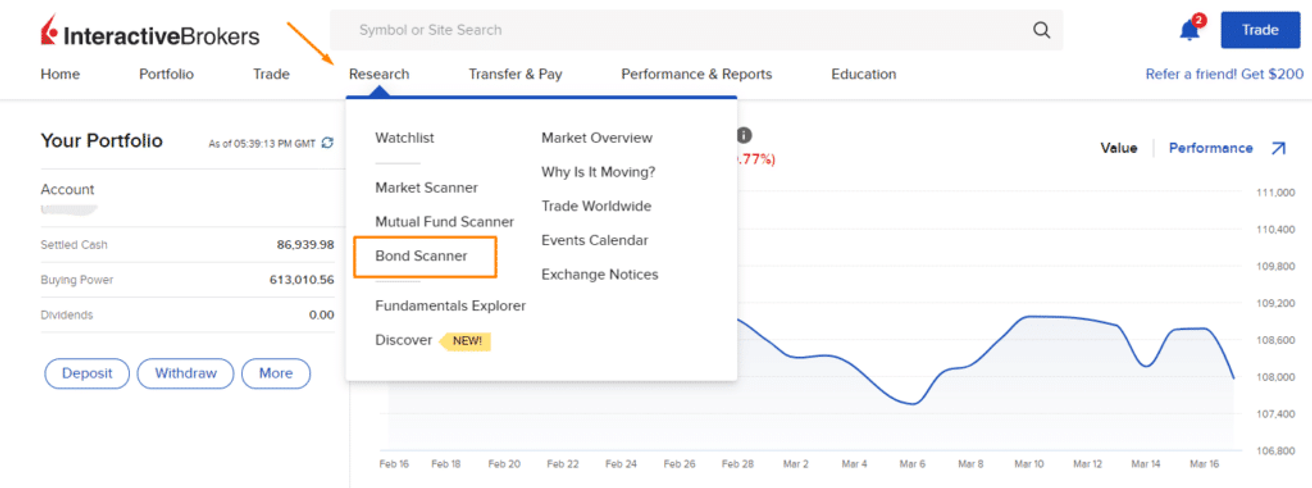
IBKR bond scanner
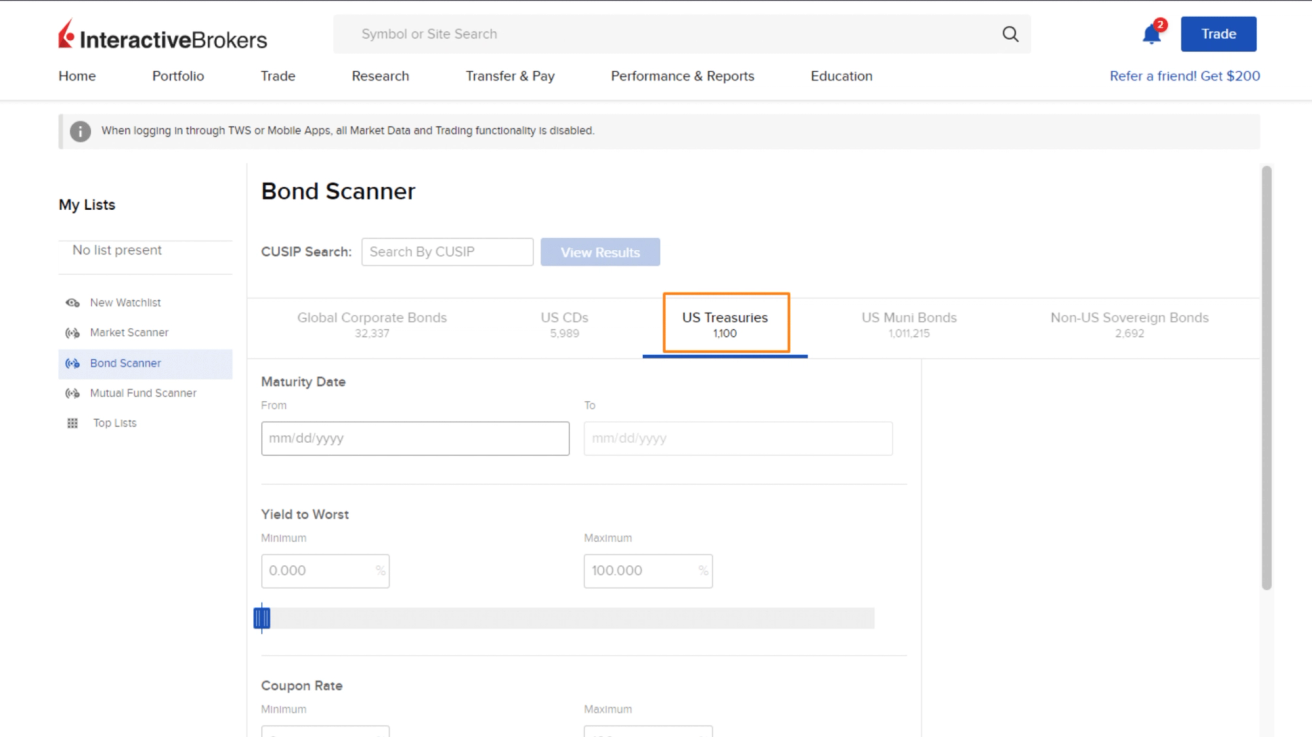
IBKR web app options
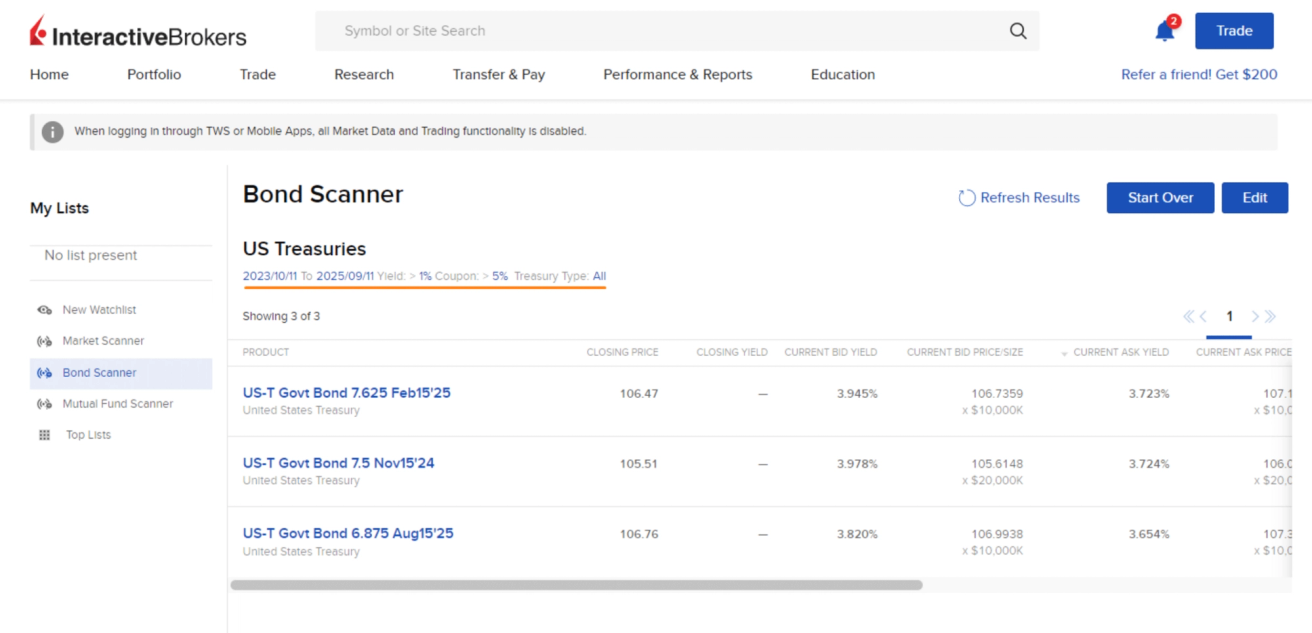
US Treasuries on IBKR
Option 2: buy US Treasury bond ETFs
When selecting a government bond ETF, look at two numbers. The yield to maturity estimates the return the fund’s bonds will deliver if held to maturity, and the duration shows how sensitive the fund’s price is to interest rate changes (a duration of 15 means the price falls about 15% if rates rise by one percentage point).
Canadian investors can choose between ETFs listed in Canada, which trade in CAD (some with CAD-hedged versions), and ETFs listed in the US, which trade in USD. Here are some of the main options:
| ETF | Exposure | Fee (MER) | Currency |
| BMO Short-Term US Treasury Bond Index ETF (ZTS) | 1 to 5 years | 0.23% | CAD, unhedged (ZTS.U in USD) |
| BMO Mid-Term US Treasury Bond Index ETF (ZTM) | 5 to 10 years | 0.22% | CAD, unhedged (ZTM.U in USD) |
| BMO Long-Term US Treasury Bond Index ETF (ZTL / ZTL.F) | Over 20 years | 0.22% / 0.23% | ZTL unhedged, ZTL.F CAD-hedged |
| iShares 20+ Year U.S. Treasury Bond Index ETF (XTLT / XTLH) | Over 20 years | 0.18% | XTLT unhedged, XTLH CAD-hedged |
| iShares 0-5 Year TIPS Bond Index ETF (XSTP / XSTH) | Inflation-linked, 0 to 5 years | 0.11% | XSTP unhedged, XSTH CAD-hedged |
| Global X 0-3 Month U.S. T-Bill ETF (UBIL.U) | T-bills | 0.13% | USD |
| iShares 0-3 Month Treasury Bond ETF (SGOV) | T-bills | 0.09% | USD (US-listed) |
| iShares 7-10 Year Treasury Bond ETF (IEF) | 7 to 10 years | 0.15% | USD (US-listed) |
| iShares 20+ Year Treasury Bond ETF (TLT) | Over 20 years | 0.15% | USD (US-listed) |
Selected US Treasury ETFs available to Canadian investors, with fees from the issuers’ websites as of October 2026. BMO ETFs trade on Cboe Canada, iShares and Global X Canadian ETFs on the TSX.
Interactive Brokers gives you access to all of them. As an example, here is the iShares 0-5 Year TIPS Bond Index ETF (XSTP), which holds short-term inflation-protected Treasuries (TIPS):
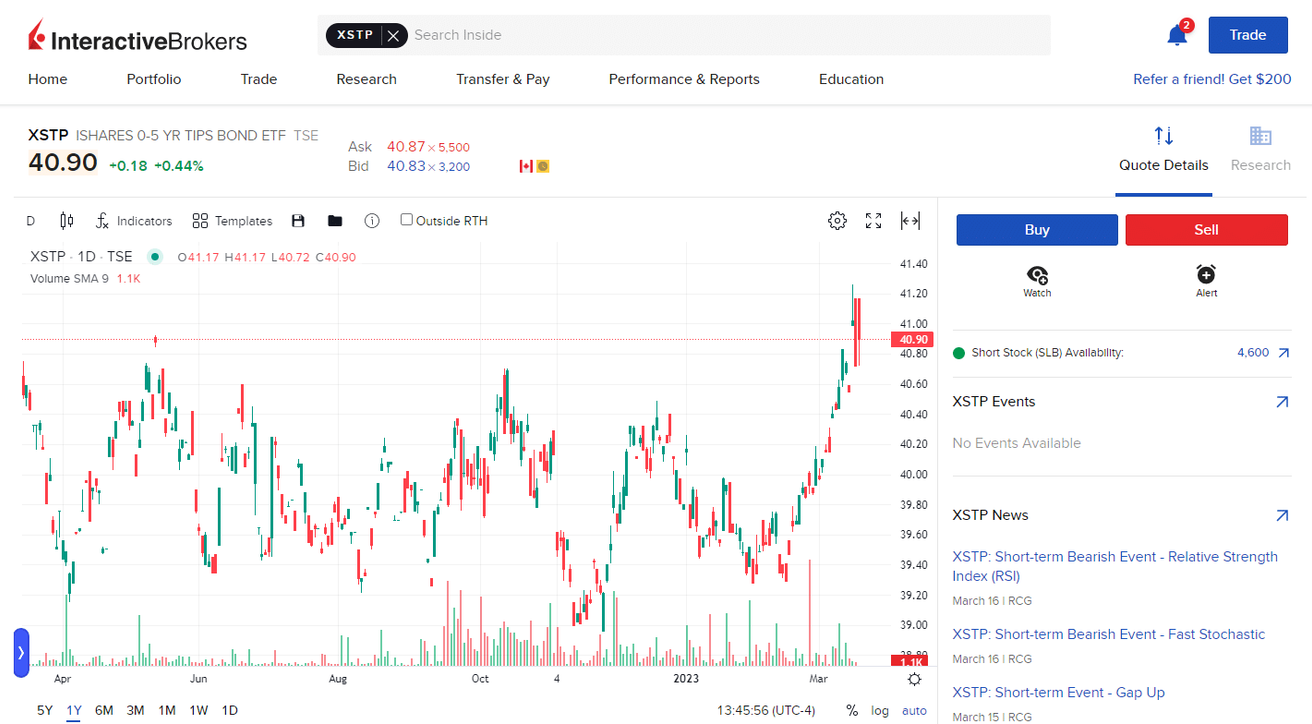
iShares 0-5 Year TIPS Bond Index ETF
XSTP is unhedged, so its returns in CAD rise and fall with the USD. If you would rather reduce currency swings, its sister fund XSTH is CAD-hedged.
If you buy US-listed ETFs such as SGOV or TLT, you will need to convert CAD to USD, and the broker will charge a currency conversion fee. Distributions from US-listed ETFs are also often subject to 15% US withholding tax outside an RRSP (bond ETF interest may qualify for an exemption, but brokers often withhold anyway), and they count towards the T1135 threshold.
The pros and cons of investing in US Treasury bonds from Canada
Pros
- High credit quality: US Treasuries are backed by the US government, which makes the possibility of default minimal.
- Liquidity: Treasuries are among the most traded securities in the world and can be bought and sold easily.
- Predictable income: if you hold an individual bond to maturity, you know in advance the interest you will receive and the amount you will get back.
Cons
- Interest rate risk: as interest rates rise, the price of your bonds falls.
- Inflation risk: the interest may not compensate for inflation (except with inflation-linked TIPS).
- Currency risk: unless you use a CAD-hedged ETF, movements in the USD/CAD exchange rate can add to or wipe out your return.
- Historically lower returns: in the long run, bonds have tended to return less than stocks.
- Complexity: bond prices move inversely to interest rates, and some brokers require you to request trading permission before you can buy individual bonds.
Conclusion
Investing in US Treasuries from Canada is straightforward once you know the routes. With a broker like Interactive Brokers, you can buy T-bills, notes and bonds directly on the secondary market for a small commission. Alternatively, Treasury ETFs listed in Canada or the US give you diversified exposure across maturities, with CAD-hedged options if you want to limit currency swings.
Before investing, consider the main risks (currency movements and interest rate changes), check the yield to maturity and duration of any ETF you buy, and think about which account to use, since interest is taxed at your full marginal rate outside an RRSP or TFSA.
With yields well above 4% across maturities in October 2026, US Treasuries can play a useful role in a diversified portfolio, alongside other assets that fit your goals and time horizon.







