We live in a time in which it is not only the risk and reward ratio of an investment that counts, but other factors come into play as well.
This has especially been obvious in the meteoric rise in ESG investing and ESG investing apps in recent times.
In this article, we uncover 18 ESG investing statistics, data and trends, updated with the latest figures for 2026.
What is ESG investing?
To put it simply, ESG stands for Environmental, Social, and Governance. Those are the three non-financial factors that investors increasingly consider before making their investing decisions. Using ESG factors, investors aim to have a positive impact on society while still earning a return on their investments.
Examples of each component of ESG may include:
- Environmental: focusing on renewable energy, reducing the carbon footprint, reducing waste, responsibly using energy and resources, etc.
- Social: focusing on human rights, data privacy, racial and gender diversity in hiring practices, treating employees fairly, involvement in the community, etc.
- Governance: focusing on the board composition, limiting corruption, aligning incentives for the executive compensation schemes, protecting whistleblowers, etc.
ESG investing statistics
1. Sustainable funds hold a record $4.24 trillion, and broader ESG assets passed $30 trillion
ESG investing has grown into a mainstream market, even after a difficult 2025. According to Morgan Stanley, assets in sustainable funds reached a record $4.24 trillion on 30 June 2026, up 4.8% in six months.
The broader universe of ESG assets, which includes mandates and portfolios that apply ESG criteria, is much larger. Bloomberg Intelligence estimates it passed $30 trillion in 2022 and expects it to exceed $40 trillion by 2030, more than a quarter of the $140 trillion in global assets under management it projects for that year.
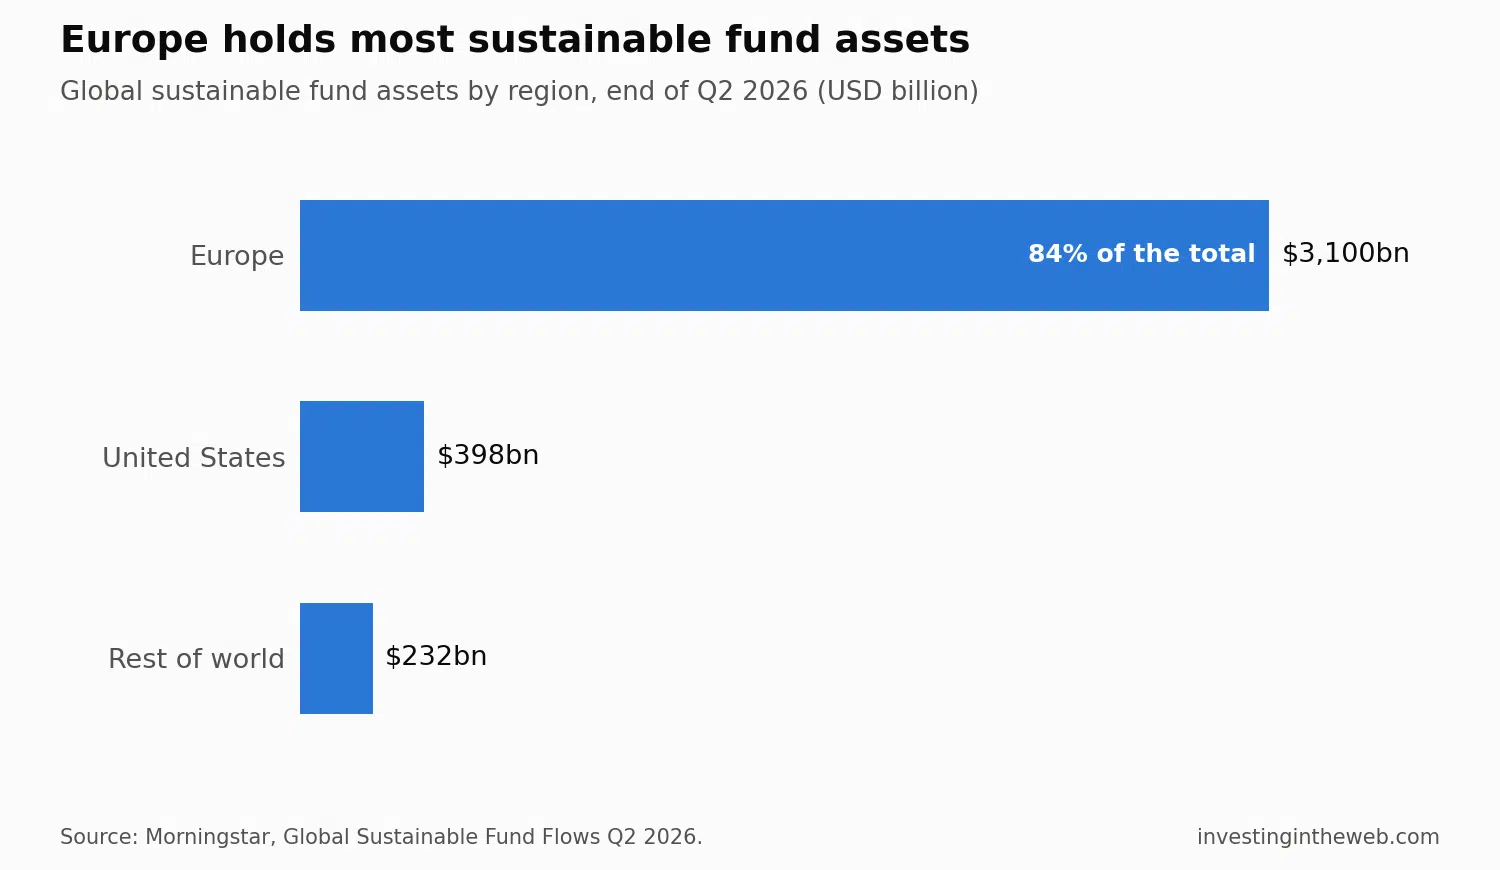
2. Europe holds 84% of global sustainable fund assets, while the US holds 11%
Europe is far ahead of other regions in ESG investing. According to Morningstar, European sustainable funds held about $3.1 trillion at the end of June 2026, around 84% of the global total of $3.7 trillion. US sustainable funds held $398 billion (11%), and the rest of the world about $230 billion.
Attitudes help explain the gap. In Capital Group’s 2022 ESG study, 31% of European investors said ESG was central to their investment approach, compared with 18% in North America, and just 6% of European investors were yet to be convinced about ESG investing, against 20% in North America. Regulation also plays a role: the EU’s disclosure and fund naming rules have pushed ESG into the mainstream of European fund distribution.
3. 2025 brought the first annual ESG outflows since 2018, but money returned in 2026
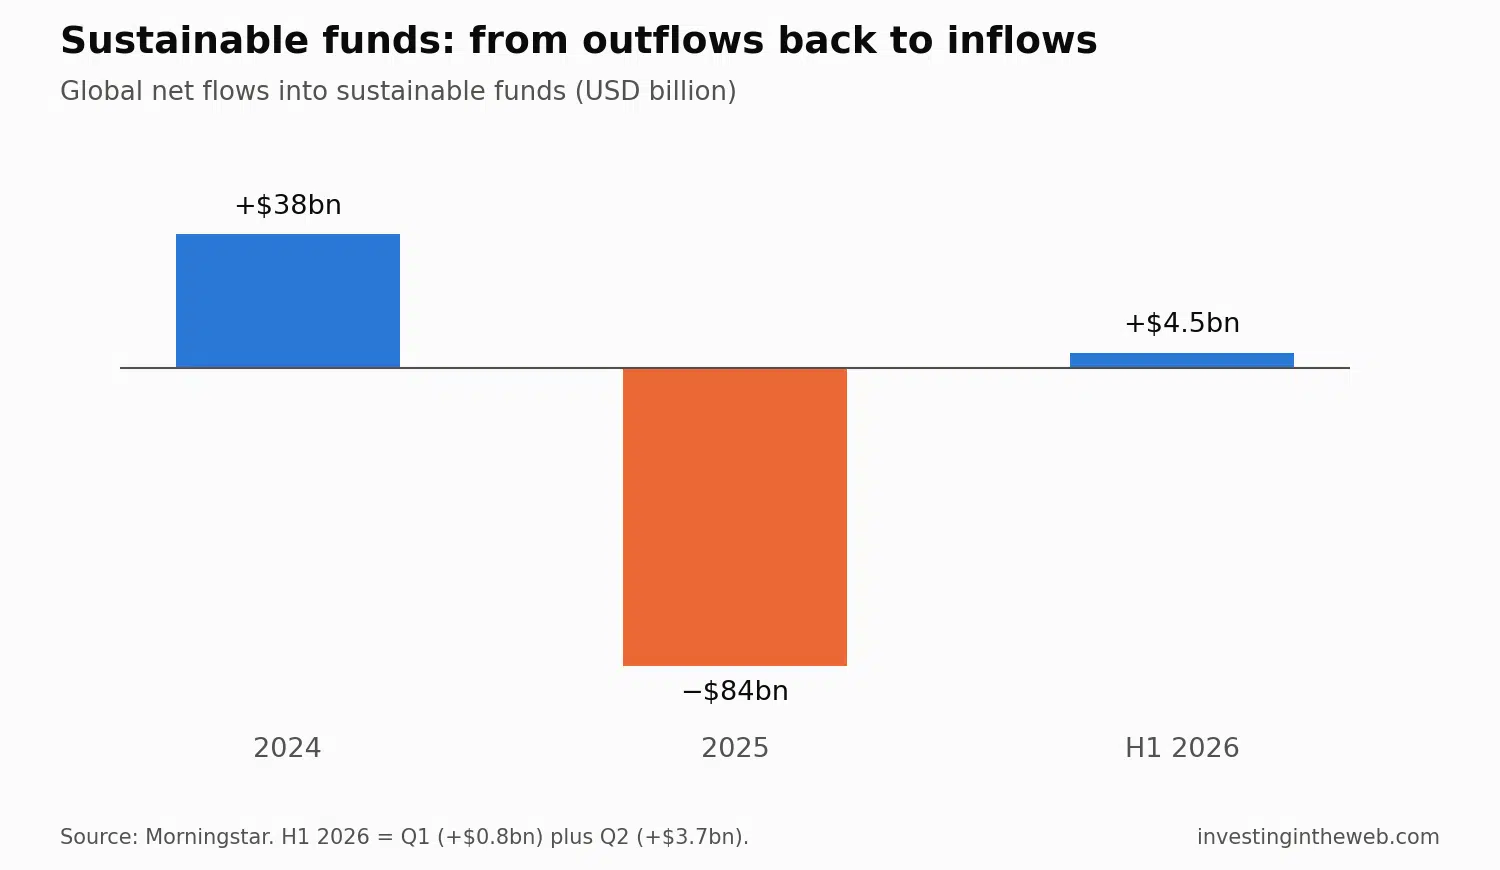
After years of growth, investors pulled a net $84 billion from sustainable funds in 2025, the first annual outflow since 2018, according to Morningstar. Both Europe and the US saw outflows, as the anti-ESG backlash in the US, weaker performance and tighter EU naming rules weighed on the market. Fewer new funds were launched, and 117 European sustainable funds closed in the fourth quarter alone.
The trend turned in 2026. Global sustainable funds attracted $0.8 billion in the first quarter and $3.7 billion in the second, and US sustainable funds posted their first inflows since 2022 after 14 consecutive quarters of outflows.
4. ESG funds have historically survived longer than non-ESG funds
Sustainable funds have historically shown greater survivorship rates than non-ESG funds. In a Morningstar analysis covering the decade to 2019, 77% of ESG funds that were available 10 years ago still exist compared to 46% for traditional funds. This can be explained by a number of factors, ranging from performance to investors’ expectations and motivations. The wave of closures and renamings since 2024 suggests that this advantage has narrowed.

5. Most investors (89%) consider ESG issues when making decisions, while only 13% see it as a passing fad
The vast majority (89%) of investors consider ESG issues in some form as part of their investment approach, according to the 2022 edition of the same Capital Group study. It found that the growth is largely driven by clients and reputational concerns rather than deeply held beliefs by the investors.

The same research shows that only 13 percent of global investors see ESG as a “passing fad that will eventually go out of fashion.” This shows us that ESG investing is already mainstream and is here to stay.
6. Sustainable funds have outperformed traditional funds since 2019
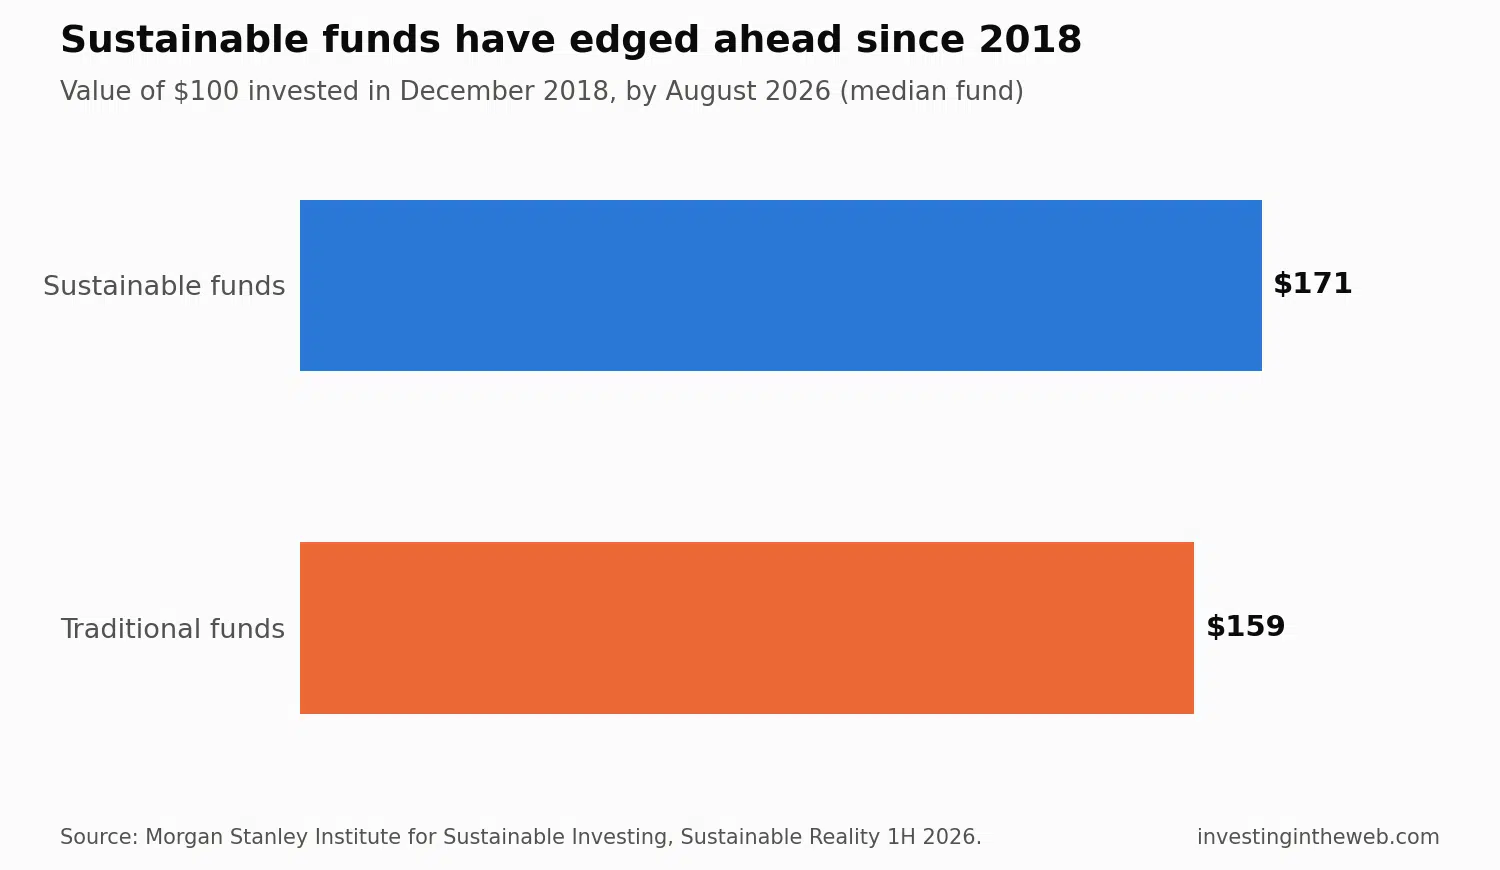
According to Morgan Stanley’s Sustainable Reality report, sustainable funds returned a median 4.9% in the first half of 2026, against 4.0% for traditional funds. Over a longer period, $100 invested in the median sustainable fund in December 2018 would have grown to $171 by August 2026, compared with $159 for traditional funds. Part of the gap comes from asset mix: sustainable funds held 56% in equities, against 41% for traditional funds.
A McKinsey survey of 2,000 companies found that ESG factors resulted in positive impacts on equity returns 63% of the time (2019). The survey found that the positive effects are due to ESG investments facilitating top-line growth, reducing costs (including regulatory and legal costs), increasing employee productivity, and streamlining capital expenditures.
In a 2022 PwC survey, 90% of asset managers surveyed believe that integrating ESG into their investment strategy may improve overall returns. Another 60% reported that ESG investing has already resulted in higher performance yields compared to non-ESG equivalents.
Keep in mind that there is some conflicting evidence on this topic (more in the next statistic).
7. But ESG indices lagged in 2025, and many investors expect ESG to underperform
Performance has not been one-way. In 2025, only 26% of ESG indices outperformed their non-ESG equivalents, down from 45% in 2024, according to Morningstar.
According to a National Bureau of Economic Research (NBER) paper based on a survey of investors, four conclusions can be made about ESG investing:
- Investors generally expected ESG investments to underperform the market (on average -1.4% a year over 10 years).
- There are substantial differences across investors in their ESG return expectations and their motives for ESG investing: 45% of survey respondents do not see any reason to invest in ESG, 25% are primarily motivated by ethical considerations, 22% are driven by climate hedging motives, and 7% are motivated by return expectations.
- The highest ESG portfolio holdings are among individuals who report ethics-driven investment motives.
- Financial considerations matter independently of other investment motives: meaningful ESG holdings are found only for investors who expect these investments to outperform the market, regardless of their reported motives.
8. The biggest challenges in ESG investing are greenwashing, data quality and performance concerns
According to the Capital Group’s 2022 ESG study, when it comes to ESG funds, investors are mainly concerned with performance, lack of data, and greenwashing. The picture is similar for individual investors: in Morgan Stanley’s 2025 Sustainable Signals survey, around 70% cited greenwashing and unreliable data as the main obstacles, and 64% had some concerns about returns.

Greenwashing is lurking in the back, especially with more and more companies pushing for ESG practices to better their public image. The lack of standardized rating systems doesn’t help in this regard. However, fewer investors in 2022 thought that asset managers mainly used ESG as a marketing and PR tool to generate sales (55% vs. 59% in 2021). The falling trend is most apparent in the Asia-Pacific region (48% vs. 59% in 2021), according to the 2022 Capital Group ESG study, as summarised by the Harvard Law School Forum on Corporate Governance.
A former director of sustainable investments at Blackrock Tariq Fancy thinks that Wall Street is greenwashing the investment world, making it mostly PR and distracting from the climate change problem.
9. Younger investors are far more interested in ESG than older investors
In Morgan Stanley’s 2025 survey of individual investors, 99% of Gen Z and 97% of Millennials said they were interested in sustainable investing, and 72% and 69% were very interested. Among Gen X, 47% were very interested, and among Baby Boomers, only 23%.
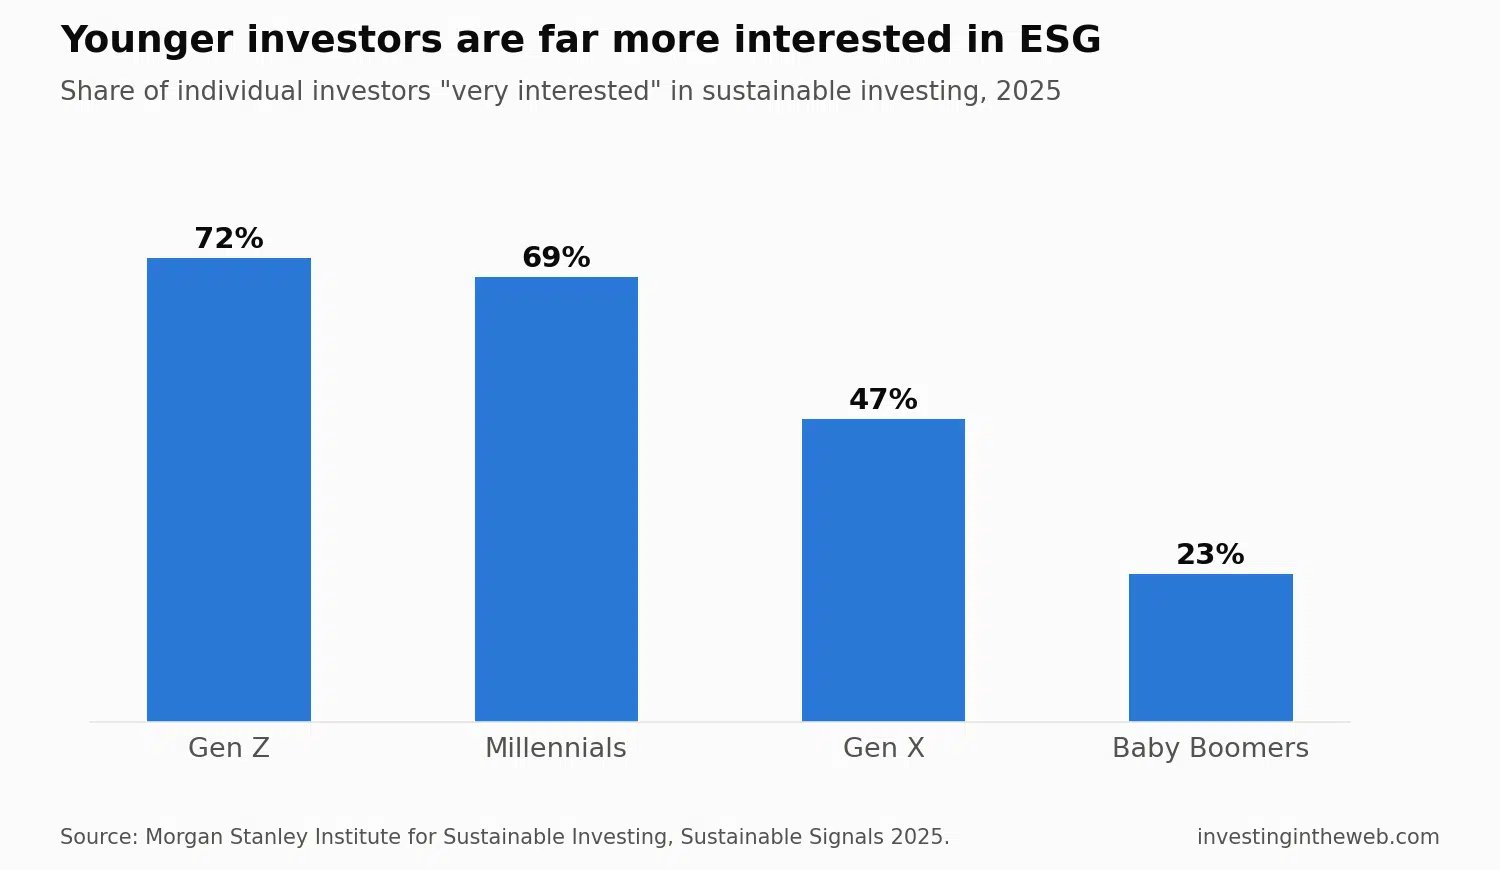
Earlier research points the same way: roughly 80% of Gen Z and Millennial investors, 60% of Gen X and just 30% of Baby Boomers said their investment firm should influence companies’ ESG policies even if doing so reduced the value of their investment, according to a Stanford University study.
In that study, an average investor in their twenties or thirties is willing to lose between 6 percent and 10 percent of their investments in the interest of companies improving their environmental practices, while the average baby boomer was unwilling to lose anything, according to the same study. The study found young wealthy investors to be the primary drivers of ESG investing.
10. More than 700 companies have signed the Climate Pledge
Companies are increasingly incorporating sustainability practices and goals. One of the best-known initiatives is the Climate Pledge, a commitment to reach net-zero carbon emissions by 2040. According to its 2026 report, it now has more than 700 signatories across 49 countries and 62 industries, 107 of which joined in the past year. Signatories cut their operational emissions by 11% on average, against 7% for comparable companies that have not signed.
11. Only 50% of companies believe they are performing well on E factors, 39% on G factors, and 37% on S factors
According to NAVEX Global, only 50% of companies surveyed believed they performed very effectively against environmental metrics. Worse yet, only 39% believe their company performs well for governance and 37% for social issues. This shows that companies have a long way to go to improve in the ESG area and are aware of their flaws.

12. ESG rankings now reward a wide range of companies, from HP to Union Pacific
Bank of America, NVIDIA and Microsoft took the top three spots in nonprofit research organization JUST Capital’s 2023 rankings. In its 2026 rankings, published with CNBC, the industry leaders include HP Inc (technology), S&P Global (financial services) and Union Pacific (industrial goods and services). Keep in mind that various systems are deployed in measuring ESG metrics, each with varying results. A more standardized reporting framework and regulation around the topic are desired by many investors.
13. Consumers are also “voting” on ESG issues with their spending, not just their investing
In a 2021 survey, 76% of consumers said they would stop buying from companies that treat the environment, employees, or the community in which they operate poorly, according to PwC. This just shows that consumers are becoming aware of their power in their financial decisions, be it spending or investing.
14. 85% of asset managers see ESG as a high priority, but 64% also show concern
In a survey by the Index Industry Association, 85% of asset managers said ESG was a high priority for their companies, but 64% were concerned about a lack of transparency and corporate disclosure on firms’ ESG activities. This shows that the era of ESG is already in full swing, but not without certain concerns.
15. The three most important elements in ESG reporting are clarity on ESG’s role in the investment process, reporting on specific E, S, and G factors, and third-party validation and review
In the aforementioned Capital Group report, the top three elements of ESG reporting cited by global investors were clarity on ESG’s role in the investment process, reporting on specific E, S, and G factors, and third-party validation and review. Some other elements, such as carbon footprints, UN Sustainable Development Goals, stewardship reports, proxy voting outcomes, and case studies, were seen as less important by global investors.

16. ESG ratings vary between different rating providers
It is also important to note that ESG classifications may vary between different companies making the classifications. As an example, Saudi Aramco is classified as “severe risk” by Sustainalytics, but as “average” by two other leading providers in this space (Refinitiv, now part of LSEG, and MSCI).
17. The demand for ESG products is outstripping supply: 30% of investors struggle to find attractive ESG products, while most asset managers prioritize converting existing products to ESG products
According to a 2022 PwC report, 30% of investors say that they struggle to find attractive and adequate ESG investment opportunities. A whopping 88% of institutional investors surveyed believe asset managers should be more proactive in developing new ESG products. However, less than half, 45%, of managers said they plan to launch new ESG funds. Instead, a majority of asset managers surveyed, 76%, said their immediate priority is converting existing products so they can be labeled as ESG-oriented.
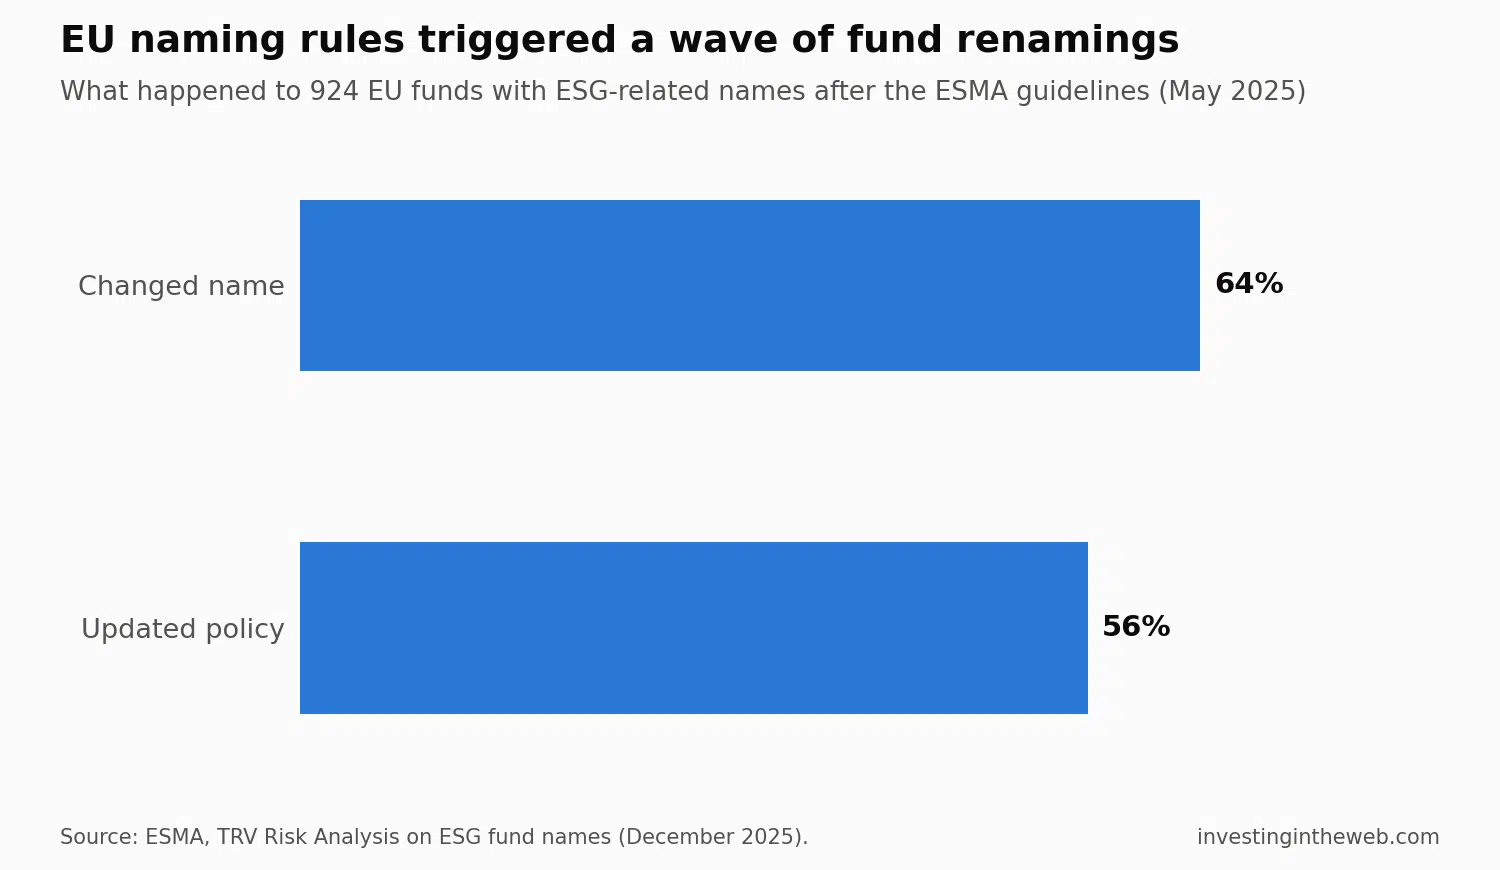
18. New EU naming rules led 64% of ESG-named funds to change their names
Since 21 May 2025, EU funds using terms such as “ESG”, “sustainable” or “green” in their names must meet the guidelines of the European Securities and Markets Authority (ESMA), including investing at least 80% of assets in line with their stated characteristics and excluding certain fossil fuel companies. In a sample of 924 funds, ESMA found that 64% changed their names, and 61% of those removed all ESG terms. Many replaced them with words such as “Screened”, “Select” or “Committed”.
The rules also changed portfolios: fossil fuel holdings in funds with sustainability or environmental names fell from €17.4 billion to €5.9 billion.
Bottom line
ESG investing is no longer a niche trend: sustainable funds hold more than $4 trillion, and interest among individual investors remains high, especially among younger generations. At the same time, 2025 showed that the market is not immune to setbacks, with record outflows, fund closures and a wave of renamings under stricter EU rules. In a society with many environmental, social, and governance issues, it is clear that many investors are looking to improve on these issues while making money at the same time, even though the latter seems to be a primary driving factor for most.
However, it is not as simple as killing two birds with one stone. Sustainable funds have edged ahead of traditional funds since 2019, but ESG indices lagged in 2025, and the jury is still out on whether investing in ESG funds has larger expected returns than their non-ESG counterparts. There are serious hurdles that ESG investing needs to overcome, starting with transparency and standardization of both ESG implementation and investing data.
Until then, it is the responsibility of each investor to do their own due diligence on this topic.