The financial industry is full of jargon, and few terms cause more confusion than CFDs and leveraged products. They are often used as if they meant the same thing, but they don’t.
The short answer: CFDs are one type of leveraged product, but not every leveraged product is a CFD. Leveraged ETFs, knock-out certificates, futures, options and buying shares on margin also give you leverage, and each one works, costs and can go wrong in a different way.
In this guide, we explain how leverage works, how CFDs work and how they are regulated in Europe, what the other leveraged products are and how they compare, with worked examples along the way.
Key takeaways:
- CFD: a contract with your broker that pays out the difference in an asset’s price. You never own the asset.
- Leveraged product: any product where a move in the underlying asset has a bigger effect on your money. CFDs are one of them.
- The real differences: who is on the other side of the trade, whether you can lose more than you put in and what it costs to keep the position open.
- Time horizon: both are short-term tools. Held for months, financing costs or volatility decay usually work against you.
What is leverage?
Leverage means controlling a position that is bigger than the money you put in. If you control €1,000 of shares with €200 of your own money, your leverage is 5:1 (often written as 5x). Every 1% move in the share price then becomes a 5% move in your own money.
Leverage does not change how much the asset moves. It changes how much each move matters to you. That is also why a product can be leveraged without any visible loan: knock-out certificates, options and leveraged ETFs build the leverage into the product itself.
What are CFDs?
A CFD (contract for difference) is an agreement between you and your broker to exchange the difference in an asset’s price between the moment you open the position and the moment you close it.
When you open a CFD on Apple, you don’t buy Apple shares. If you buy (go long) and the price rises, the broker pays you the difference. If it falls, you pay the broker. If you sell (go short), it works the other way round, which is why CFDs make it easy to profit from falling prices.
Because only the difference changes hands, the broker doesn’t ask for the full value of the position. It asks for a deposit, called margin. That is where the leverage comes from.
A worked example
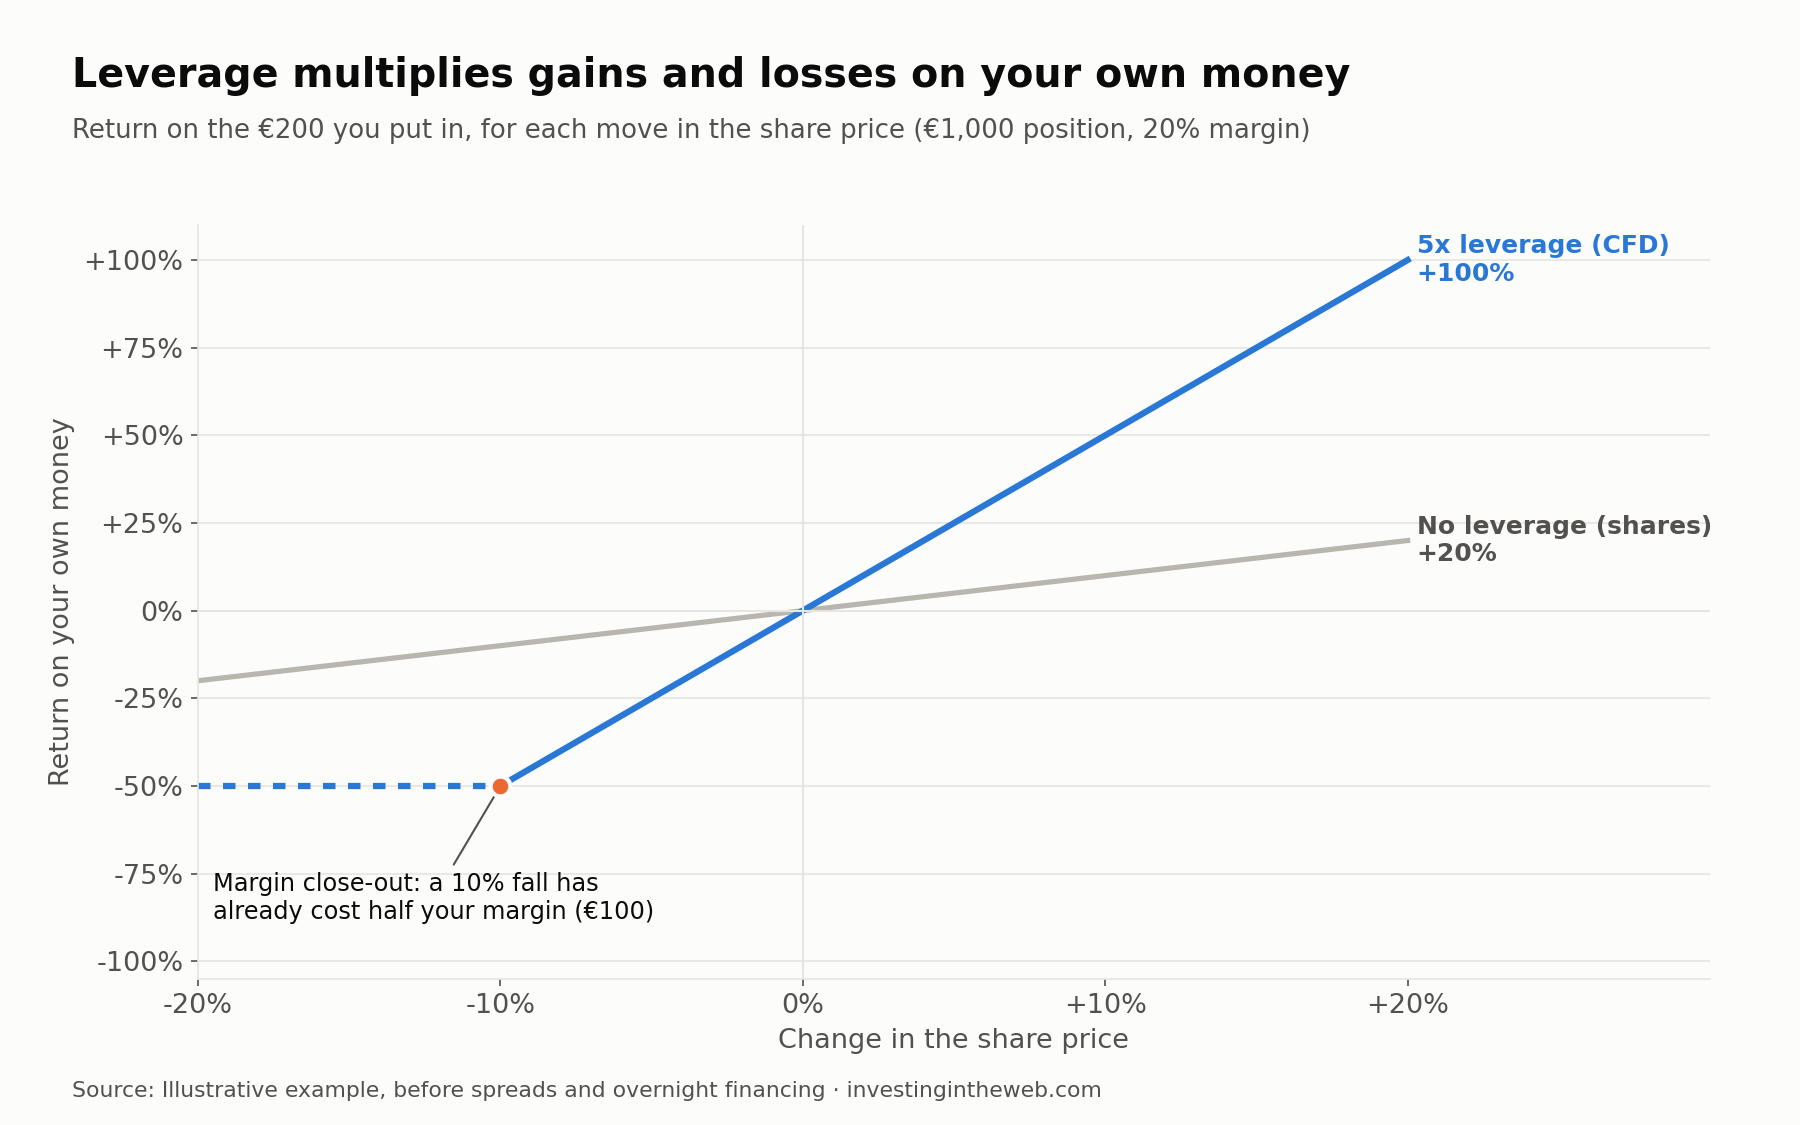
John wants exposure to 100 shares of a company trading at €10. His broker requires 20% margin for share CFDs:
- Position size: 100 × €10 = €1,000.
- Margin John puts up: €200.
- Leverage: 5:1 (€1,000 of exposure for €200 of his own money).
The other €800 is not handed to John as a loan. He simply has €1,000 of exposure, and the broker charges overnight financing on the full €1,000 for every night the position stays open.
Here is what happens with different price moves (before costs):
- The price rises 20%: John gains €200, a 100% return on his €200. Someone who bought €200 of real shares would gain €40.
- The price falls 5%: John loses €50, a quarter of his margin.
- The price falls 10%: John loses €100, half of his margin. For retail clients in the EU and the UK, the broker must close positions when the money in the account falls to 50% of the margin required, so if the €200 is all John has in his account, his position is closed here.
- The price gaps down 30% overnight: the broker can’t close the position at -10%, so the loss is €300, more than John deposited. Retail clients in the EU and the UK have negative balance protection, so the broker absorbs the €100 beyond his balance. Outside these regions, John could owe it.
This is the defining feature of leverage: a modest move in the asset becomes a large move in your capital, in either direction.
What a CFD really costs
The price move is only half the story. These are the costs that decide whether a CFD trade makes money:
- Spread: the difference between the bid price (at which you can sell) and the ask price (at which you can buy) quoted by the broker. You pay it every time you open and close a position.
- Commission: some brokers charge a commission on share CFDs instead of widening the spread.
- Overnight financing: charged every night on the full value of the position, usually a benchmark interest rate plus the broker’s markup.
- Currency conversion: applies if the asset is priced in a different currency from your account.
Overnight financing is the one that catches people out. At a financing rate of, for example, 7% a year, keeping John’s €1,000 position open for 30 days costs about €5.75 (€1,000 × 7% × 30/365). That is almost 3% of his €200 margin, before the share has moved at all.
How CFDs are regulated in the EU and the UK
Since 2018, after measures introduced by ESMA (the European Securities and Markets Authority), EU regulators and the UK’s FCA (Financial Conduct Authority) apply strict rules to CFDs sold to retail clients. The best-known rule caps leverage by type of asset:
| Underlying asset | Maximum leverage | Minimum margin |
| Major currency pairs | 30:1 | 3.33% |
| Non-major currency pairs, gold and major stock indices | 20:1 | 5% |
| Commodities other than gold and non-major stock indices | 10:1 | 10% |
| Individual shares and other assets | 5:1 | 20% |
| Cryptocurrencies | 2:1 | 50% |
Leverage limits for CFDs sold to retail clients in the EU and the UK. Source: ESMA
The same rules also require:
- Margin close-out: positions are closed when your account falls to 50% of the margin required.
- Negative balance protection: retail clients can’t lose more than the money in their CFD account.
- A standard risk warning: every broker must publish the share of its retail accounts that lose money on CFDs, a figure that is usually well above half.
- No trading incentives: brokers can’t offer bonuses to get you to trade CFDs.
These protections apply to retail clients only. Professional clients can use higher leverage but give them up. In the US, CFDs can’t be offered to retail investors at all.
Pros and cons of CFDs
Pros
-
Access to shares, indices, currencies and commodities from one account
-
Easy to go short
-
Leverage lets you open a position with less capital
- Can be used to hedge an existing portfolio
Cons
-
Losses are amplified as much as gains
-
Overnight financing makes long holding periods expensive
-
Your broker is the counterparty to every trade
-
Spreads and currency costs add up with frequent trading
- Most retail accounts lose money
What other leveraged products are there?
All leveraged products share one feature: a move in the underlying asset has a bigger effect on your money. Where they differ is where they trade, who owes you the money and how much you can lose. These are the main ones available to European investors.
Leveraged and inverse ETFs and ETPs
Leveraged ETFs (exchange-traded funds) aim to deliver a multiple, usually 2x or 3x, of an index’s daily return. Inverse (short) versions aim to deliver the opposite. For example, the ProShares UltraPro Short S&P 500 (SPXU) targets -3x the daily return of the S&P 500, so if the index falls 3% in a day, it should rise about 9% that day.
You buy them on a stock exchange like any other ETF, so you don’t need a margin account and you can’t lose more than you invest. In Europe, retail investors usually can’t buy US-listed products like SPXU. Leveraged UCITS ETFs (funds that follow the EU’s UCITS rules) are generally limited to 2x, so 3x products are usually ETPs (exchange-traded products), often structured as exchange-traded notes (ETNs). An ETN is a debt security, so you also depend on the issuer being able to pay.
Why daily reset matters: volatility decay
Because these products reset their leverage every day, their return over several days is not simply 2x or 3x the index’s return. In a market that goes up and down without a clear direction, they lose value even if the index ends close to where it started.
Here is an example. An index alternates between +5% and -5% every day for 10 days. The index ends down 1.2%. A 3x daily ETF, which moves +15% and -15% on the same days, ends down 10.8%, about nine times the index’s loss rather than three times.
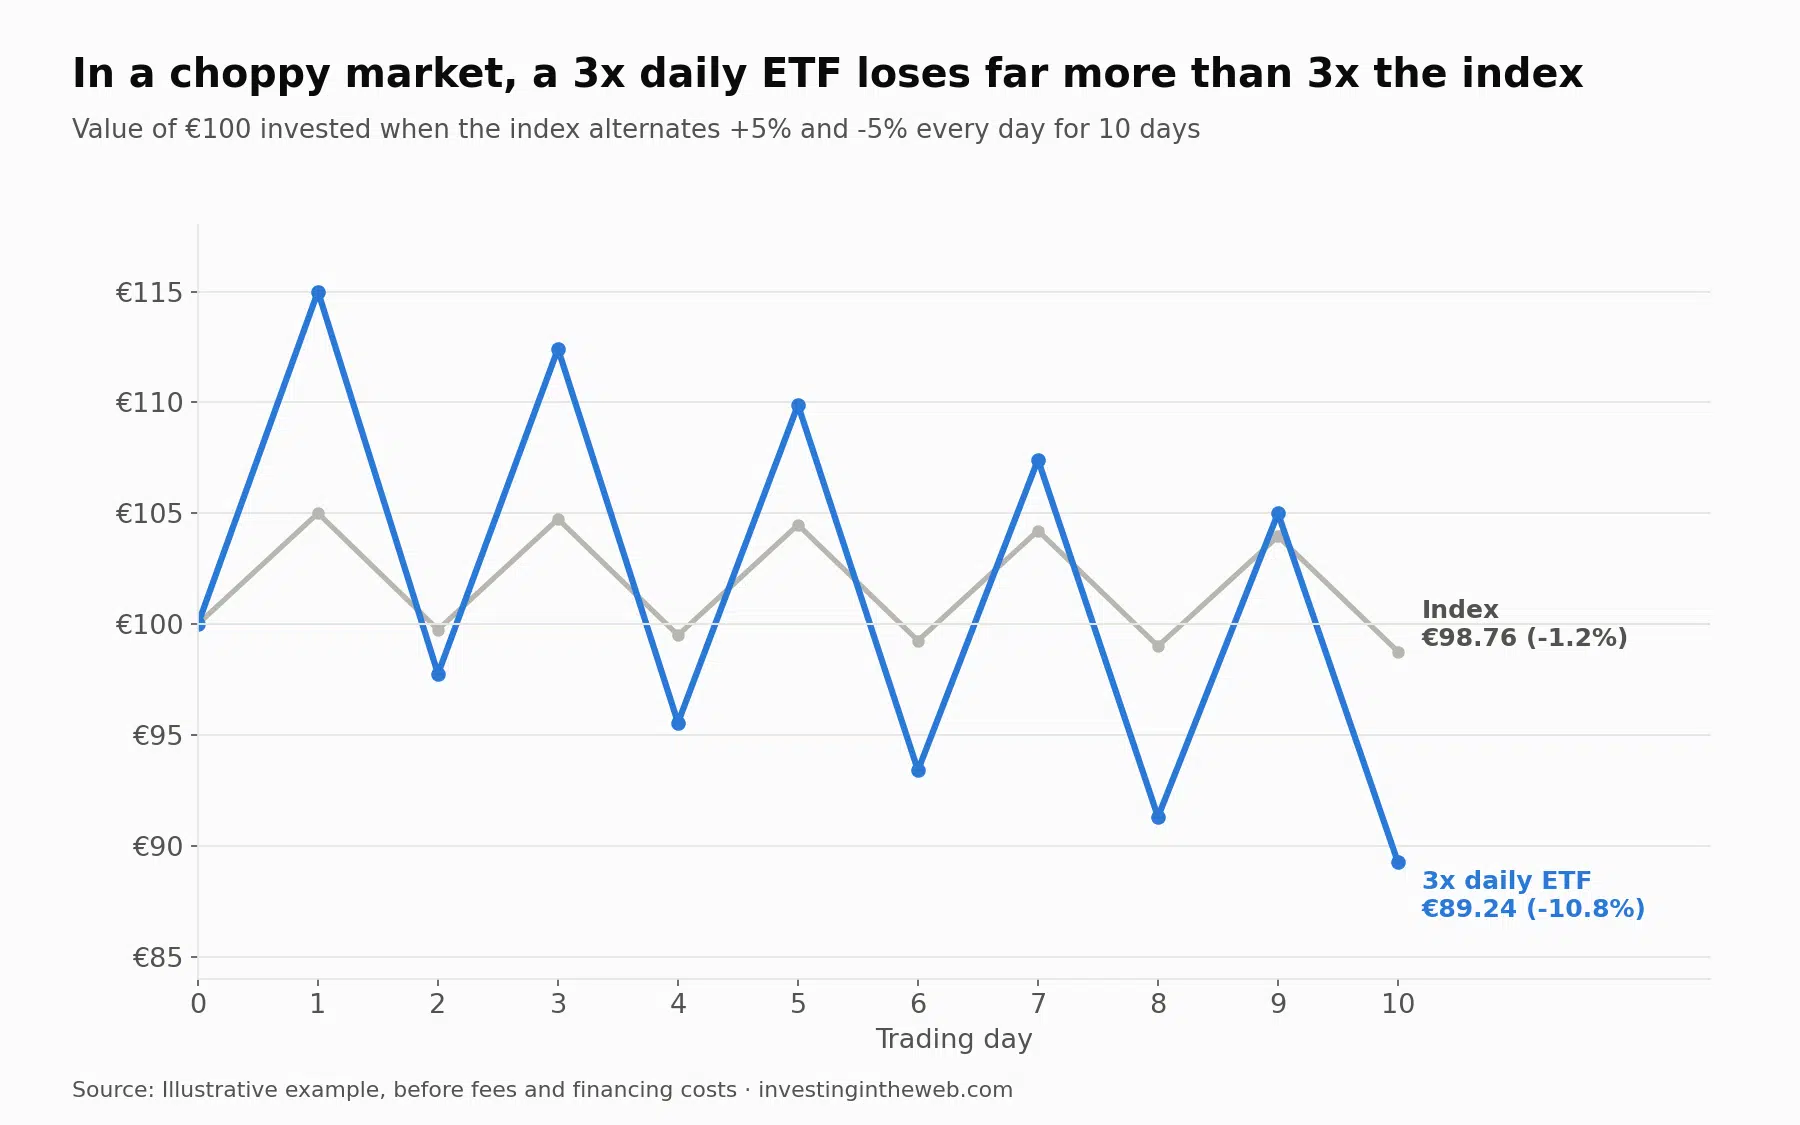
The effect works in your favour in a strong, steady trend and against you in a choppy market. That is why issuers describe these products as intended for short holding periods.
Knock-out certificates, mini futures and factor certificates
These are securities issued by banks and traded on exchanges, very popular in Germany, Austria and the Netherlands.
- Knock-out certificates (turbos): the leverage comes from a financing level set by the issuer. If the price touches the knock-out barrier, the certificate expires and you lose most or all of what you paid. You can’t lose more than that.
- Mini futures: similar to knock-outs, but without a fixed expiry date. The financing cost is built into a financing level that changes every day.
- Factor certificates: constant daily leverage, like leveraged ETPs, so they suffer from the same volatility decay.
- Warrants: options issued by a bank rather than an exchange.
As with ETNs, these are debt securities of the issuing bank, so you take on the issuer’s credit risk.
Futures
Futures are standardised contracts to buy or sell an asset at a set price on a future date, traded on exchanges and guaranteed by a clearing house. You post margin set by the exchange, and gains and losses are settled every day. Contracts are large (one Micro E-mini S&P 500 future is worth $5 times the index), they expire and must be rolled over, and there is no negative balance protection, so losses can exceed your deposit.
Options
An option gives you the right, but not the obligation, to buy (call) or sell (put) an asset at a set price before a set date. When you buy an option, your maximum loss is the premium you paid, while small price moves can produce large percentage gains. Selling options is very different: your potential loss can be far larger than the premium you receive.
Buying shares on margin
With a margin account, your broker lends you money to buy more shares than you could with your own cash. Unlike a CFD, you own the shares. You pay interest on the loan, and if your portfolio falls too far, you get a margin call: you must add money or the broker sells your positions. Losses can exceed your own capital.
Pros and cons of exchange-traded leveraged products
Pros
-
Traded on regulated exchanges with transparent prices
-
Maximum loss is limited to the amount invested for leveraged ETPs, knock-outs and bought options
-
No margin account needed for ETPs and certificates
- Inverse products make it easy to bet on falling prices
Cons
-
Volatility decay erodes daily-reset products over time
-
Issuer credit risk for ETNs and certificates
-
Ongoing charges are higher than for regular ETFs
-
Bid-ask spreads still apply and widen in volatile markets
- A brief price spike can knock out a certificate
CFDs vs other leveraged products: side by side
The table below summarises how the main leveraged products compare for a retail investor in the EU or the UK.
| Product | Where it trades | Who owes you the money | Can you lose more than you invest? | Main holding cost |
| CFD | With your broker (over the counter) | Your broker | No, for EU and UK retail clients | Overnight financing |
| Leveraged ETF or ETP | Stock exchange | The fund (ETF) or the issuer (ETN) | No | Ongoing charge and volatility decay |
| Knock-out certificate | Exchange or the issuer | The issuing bank | No | Financing built into the price |
| Futures | Exchange | Clearing house | Yes | Rollover and financing built into the price |
| Options (bought) | Exchange | Clearing house | No | Time decay of the premium |
| Buying shares on margin | Exchange (you own the shares) | You own the shares and owe the broker | Yes | Margin interest |
Simplified comparison for retail investors in the EU and the UK. Rules differ by country and by broker.
Which one fits which purpose?
- A short-term trade on a single share or currency pair: CFDs are the most flexible tool, as they cover thousands of markets and let you go long or short.
- A view on an index over a day or two: leveraged ETPs, knock-out certificates and futures all work, and the exchange-traded options cap your loss at what you invest.
- Hedging a portfolio you don’t want to sell: short CFDs, inverse ETPs, put options or index futures can offset part of a fall.
- Long-term investing: none of them. For a long-term portfolio, plain shares and ETFs avoid financing costs, volatility decay and margin calls.
Taxes can also differ between these products. In some countries, CFDs, certificates and ETFs are taxed in different ways, and in the UK, spread betting (a close relative of CFDs) is generally free of capital gains tax. Check the rules where you live before choosing.
FAQs
Is a CFD the same as a leveraged ETF?
No. A CFD is a private contract with your broker, financed overnight and protected (for EU and UK retail clients) by margin close-out and negative balance protection. A leveraged ETF is a fund you buy on a stock exchange, with daily-reset leverage built in. You can’t lose more than you invest in a leveraged ETF, but its value erodes in choppy markets.
Can you lose more than you invest with CFDs?
Retail clients in the EU and the UK can’t lose more than the money in their CFD account, thanks to negative balance protection. You can still lose your entire deposit, and quickly. Professional clients and clients of brokers outside these regions may not have this protection.
What is the difference between margin and leverage?
Margin is the deposit you put up to open a position. Leverage is the ratio between the size of the position and that deposit. A 20% margin means 5:1 leverage, and a 5% margin means 20:1 leverage.
Are CFDs legal in the US?
No. US rules don’t allow CFDs to be offered to retail investors. Americans who want leverage usually use options, futures, margin accounts or leveraged ETFs instead.
Can I hold a leveraged ETF for the long term?
You can, but it is risky. Because leverage resets every day, long-term returns can be very different from 2x or 3x the index, and in volatile, sideways markets they can be negative even when the index rises slightly. Issuers design these products for short holding periods.
Is spread betting the same as trading CFDs?
They are very similar. With spread betting, you bet an amount per point of price movement rather than buying a number of contracts. It is mainly offered in the UK, where gains are generally free of capital gains tax because they are treated as betting.
Bottom line
CFDs and other leveraged products can be useful for specific purposes: hedging a portfolio, taking a short-term view in either direction or going short without borrowing shares. However, they are tools for short holding periods, and the same leverage that multiplies gains multiplies losses just as fast.
The main differences come down to three questions:
- Who is on the other side? With a CFD, your broker. With ETNs and certificates, the issuing bank. With futures and listed options, a clearing house.
- How much can you lose? Your stake with leveraged ETPs, knock-outs and bought options. Your account balance with CFDs for EU and UK retail clients. More than your deposit with futures, sold options and margin loans.
- What does time cost you? Overnight financing with CFDs and margin loans, volatility decay with daily-reset products and time decay with options.
If you decide to use them, size your positions so that a bad day can’t wipe out your account, understand every cost before you trade and never use money you can’t afford to lose.
Risk disclaimer: CFDs and other leveraged products are complex instruments and come with a high risk of losing money rapidly due to leverage. Consider whether you understand how they work and whether you can afford to take the high risk of losing your money. When investing, your capital is at risk and you may get back less than invested. Past performance doesn’t guarantee future results.