



Pensions are a foundational part of the UK economy, with workplace and personal pensions playing a critical role in retirement planning for millions of Britons. As we all naturally compare and contrast our finances with others, there’s understandable curiosity around average pension pot sizes in the UK.
What’s worth keeping in mind is that the size of your pension will likely correlate strongly with your age. More years in employment typically mean more time to contribute, more years of employer matching, and more time for compound investment growth to work in your favour.
To give you some insights into the state of UK pensions, this article looks at average pension sizes by age and region, provides statistics from the Office for National Statistics (ONS) and the Department for Work and Pensions (DWP), and offers practical tips to help you make the most of your personal and workplace pensions.
What is the average pension pot in the UK?
According to the ONS, the latest Wealth and Assets Survey (April 2020 to March 2022) puts the median private pension wealth at £57,500 among adults in Great Britain who have a private pension. Across all adults, including those with no private pension at all, the median is just £19,700. These figures span everyone from people just starting their careers to those about to retire, which is why they are far below what is typically considered adequate for retirement.
For context, the Retirement Living Standards from Pensions UK (formerly the Pensions and Lifetime Savings Association, PLSA) estimate that a single retiree needs to spend roughly:
- £13,900 a year for a “minimum” retirement standard.
- £32,700 a year for a “moderate” retirement standard.
- £45,400 a year for a “comfortable” retirement standard.
The full new State Pension is £241.30 a week (about £12,548 a year). Using a 4% withdrawal rate, covering the rest of a “moderate” budget from a pension pot would require roughly £500,000, far above the median pot.
UK average pension pot size by region
Beyond age, where you live in the UK significantly affects the average size of pension pots. Regional differences reflect variations in average earnings, employment patterns, cost of living, and historical industrial composition. Regions with higher-paying professional services and finance jobs tend to show larger average pension pots.
Here’s how average household private pension wealth varied across Great Britain in the ONS data from April 2018 to March 2020:
| Region | Average household private pension wealth |
| South East | £155,100 |
| Wales | £131,300 |
| East of England | £121,500 |
| South West | £115,600 |
| North West | £112,900 |
| West Midlands | £107,100 |
| Yorkshire and the Humber | £102,000 |
| North East | £97,000 |
| East Midlands | £87,200 |
| London | £84,500 |
| Great Britain average | £111,700 |
Source: ONS (April 2018 to March 2020), via Hargreaves Lansdown. The survey covers Great Britain, so Northern Ireland is not included.
Average UK pension pot by age
It can be difficult to find precisely accurate UK pension statistics because the field is complex, figures vary by data provider, methodology, and definitions of what counts as a “pension”. However, PensionBee publishes useful insights on defined contribution (DC) pensions drawn from 285,287 customers (as at 30 June 2025), broken down by age and gender. Their data is widely cited as a reasonable proxy for the broader DC pension landscape, although it represents only the workplace and personal pensions held with PensionBee specifically.
Below is the average UK DC pension pot broken down by age and gender, alongside ONS median figures by age.
Average pension pot by age and sex
| Age | Male | Female | Gender gap |
| Under 30 | £4,009 | £3,481 | 13% |
| 30 to 39 | £11,870 | £9,451 | 20% |
| 40 to 49 | £26,482 | £20,141 | 24% |
| 50+ | £54,512 | £30,644 | 44% |
Source: PensionBee Pension Landscape, July 2025.
Average pension pot under 30
As might be expected, average pension balances for those just starting their careers are relatively modest. For UK workers under 30:
- Male: £4,009
- Female: £3,481
The gender gap is already visible at this age, with women holding around 13% less than men on average. This early divergence reflects pay differentials, career break patterns and lower employer matching among lower-paid roles, and importantly, gaps at this stage compound substantially over a working lifetime due to lost investment growth.
Average pension pot at 30 to 40 years old
Here’s what the average UK pension pot looks like for those between 30 and 39 years of age:
- Male: £11,870
- Female: £9,451
Pension balances roughly triple between the under-30 bracket and the 30 to 39 bracket, reflecting growing salaries, longer contribution periods, and the powerful effects of compounding. The gender gap widens to around 20% at this age. This decade is critical for catch-up: workers who start increasing their contributions in their 30s still benefit from 25 to 30 years or more of compound growth before retirement.
Average pension pot at 40 to 50 years old
Here’s what the average UK pension pot looks like for those between 40 and 49 years of age:
- Male: £26,482
- Female: £20,141
The 40s typically represent peak earning years for many UK professionals, which is reflected in the accelerated pension growth shown here. The gender gap remains stubbornly around 24%, often reflecting the cumulative impact of career breaks, part-time work, and reduced employer matching among women returning to the workforce. Anyone in this age bracket who feels behind on pension savings still has roughly 20 to 25 years before typical retirement age, which is enough time for meaningful catch-up contributions to make a substantial difference.
Average pension pot at over 50 years old
Here’s what the average UK pension pot looks like for those over 50 years of age:
- Male: £54,512
- Female: £30,644
By age 50, the gender pension gap widens significantly to around 44%, reflecting cumulative effects of pay gaps, career breaks, and the disproportionate impact of caring responsibilities on women’s earnings throughout their careers. For workers in this bracket, the priority shifts from long-term accumulation to a balanced approach: continuing meaningful contributions where possible while considering risk reduction as retirement approaches.
Average pension pot at 55, 60, 65 and above
The ONS Wealth and Assets Survey covers all private pension types, including defined benefit (DB) pensions, which tend to be larger. These are the median values for people who hold a private pension, from April 2020 to March 2022:
| Age | Median private pension wealth |
| 16 to 24 | £5,500 |
| 25 to 34 | £18,800 |
| 35 to 44 | £39,500 |
| 45 to 54 | £80,000 |
| 55 to 64 | £137,800 |
| 65 to 74 | £145,900 |
| 75 and over | £59,700 |
Source: ONS Wealth and Assets Survey, Pension wealth in Great Britain (Table 6.10), April 2020 to March 2022, published January 2025. The ONS has suspended the accredited official statistics status of the survey from this round, so treat the figures as indicative.
Pension wealth peaks in the 55 to 74 age range, at around £140,000 to £146,000, which is meaningfully higher than the PensionBee averages because the ONS data includes DB pensions. It then falls for those aged 75 and over, who have been drawing down their pots or converting them into annuities for longer, and who often have DB income that is not fully reflected in pot sizes.
What’s the biggest pension pot in the UK?
According to FTAdviser analysis of HMRC data from 2023, the largest known pension pot in the UK is worth approximately £11 million, dramatically higher than the typical UK pension pot. This is largely a function of decades of high earnings, consistent contributions and sustained investment growth. Large pots used to face the Lifetime Allowance (LTA) tax charge, which was abolished from April 2024. It was replaced by a cap on tax-free cash, the Lump Sum Allowance of £268,275.
While £11 million sits at the extreme upper end, the broader top tier shows just how much variation exists in UK pensions: a small minority of high earners hold pots in the multi-million-pound range, while the median pension is a tiny fraction of that. The gap underscores why personal pension strategy (regular contributions, employer matching and long-term investing in low-cost diversified portfolios) matters more than chasing benchmark figures.
Overview of pensions in the UK
After diving into the statistics, it’s worth providing a brief overview of how the UK pension system actually works. Pensions are a frequently discussed and constantly evolving area due to political reforms and societal shifts.
The main types of pensions in the UK are:
- State Pension: a government-funded pension paid to people who have reached State Pension age and have built up qualifying National Insurance contributions (35 years for the full new State Pension of £241.30 a week).
- Defined benefit (DB) pensions: employer-provided pensions paying a guaranteed retirement income based on salary and years of service (also known as “final salary” or “career average” schemes). DB pensions were historically the dominant workplace pension model but have been largely phased out in the private sector.
- Defined contribution (DC) pensions: workplace or personal pensions where you, your employer, or both contribute into an investment pot. The final retirement value depends on contributions made and investment performance.
For the purpose of this guide, we focus mostly on defined contribution (DC) pensions, the dominant model for today’s UK workforce. The State Pension is set by government and not within individual control, and DB pensions are now relatively rare in the private sector and harder to quantify in pot-size terms.
A DC pension is a workplace or private pension that you pay into to build up a retirement pot over your working life. For most UK employees, this is set up automatically through auto-enrolment, with your employer typically contributing alongside you.
The minimum statutory contribution under auto-enrolment is 8% of qualifying earnings, typically split as:
- 5% from the employee (which includes 1% government tax relief).
- 3% from the employer.
Many employers contribute more than the statutory minimum: some match employee contributions up to 6% or more, effectively giving you “free money” if you raise your own contributions accordingly. You also receive pension tax relief on contributions: basic-rate taxpayers receive 20% relief automatically, while higher-rate (40%) and additional-rate (45%) taxpayers can claim additional relief through their self-assessment tax return, making pension contributions one of the most tax-efficient savings vehicles available to UK workers.
UK Pension Statistics
Let’s take a look at some overall statistics relating to workplace and private pensions in the UK.
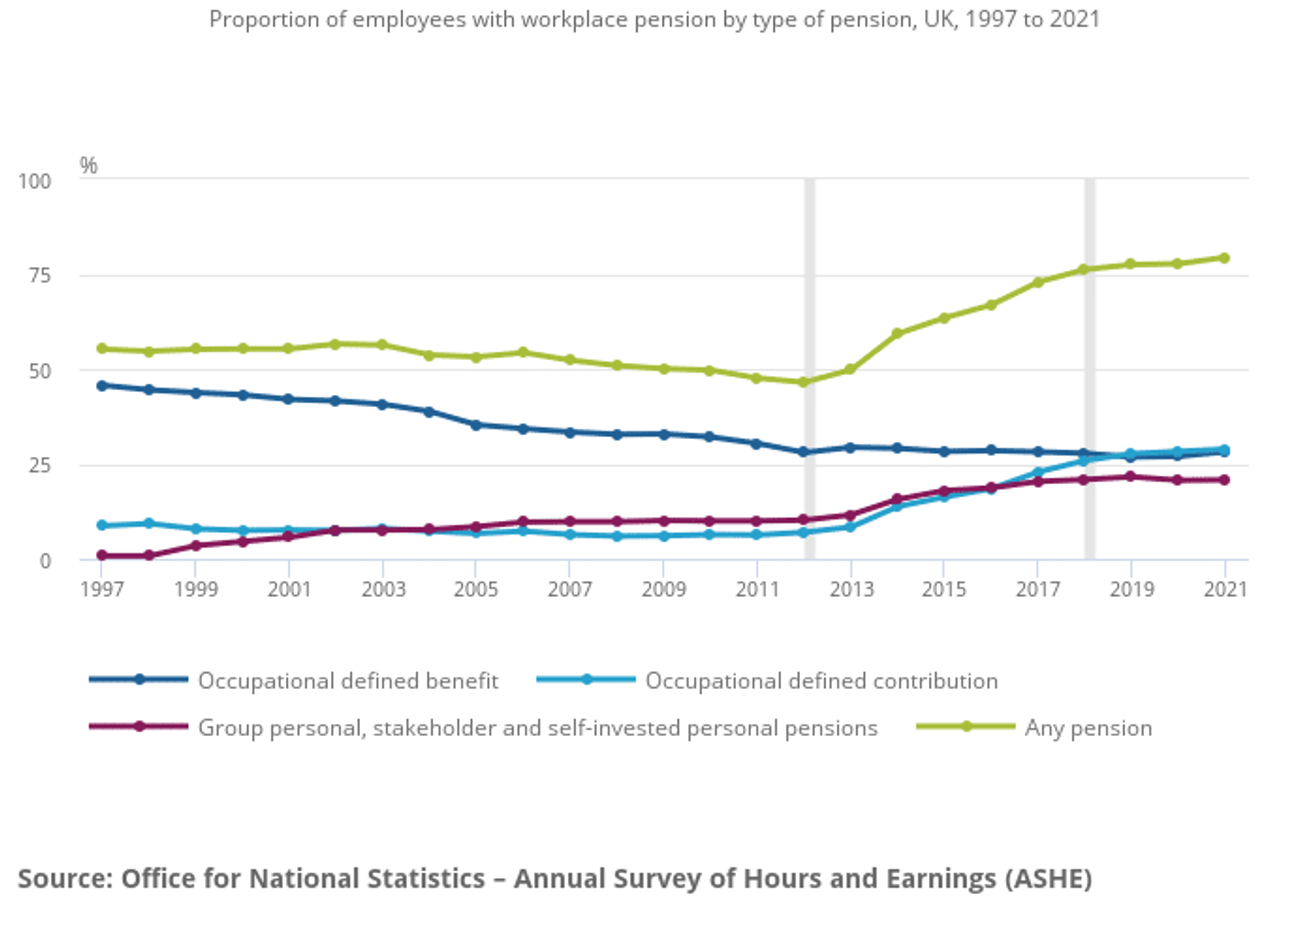
According to the DWP, around 9 in 10 eligible employees (90%) in Great Britain were saving into a workplace pension in 2025, or 22.6 million people, and together they saved £166.1 billion that year. The chart below, from the ONS, shows how participation took off after auto-enrolment started.
Source: ONS
Workplace pension participation has risen sharply (even as defined benefit (DB) membership declined), largely because auto-enrolment was introduced in 2012 (shown by the first grey line in the graph).
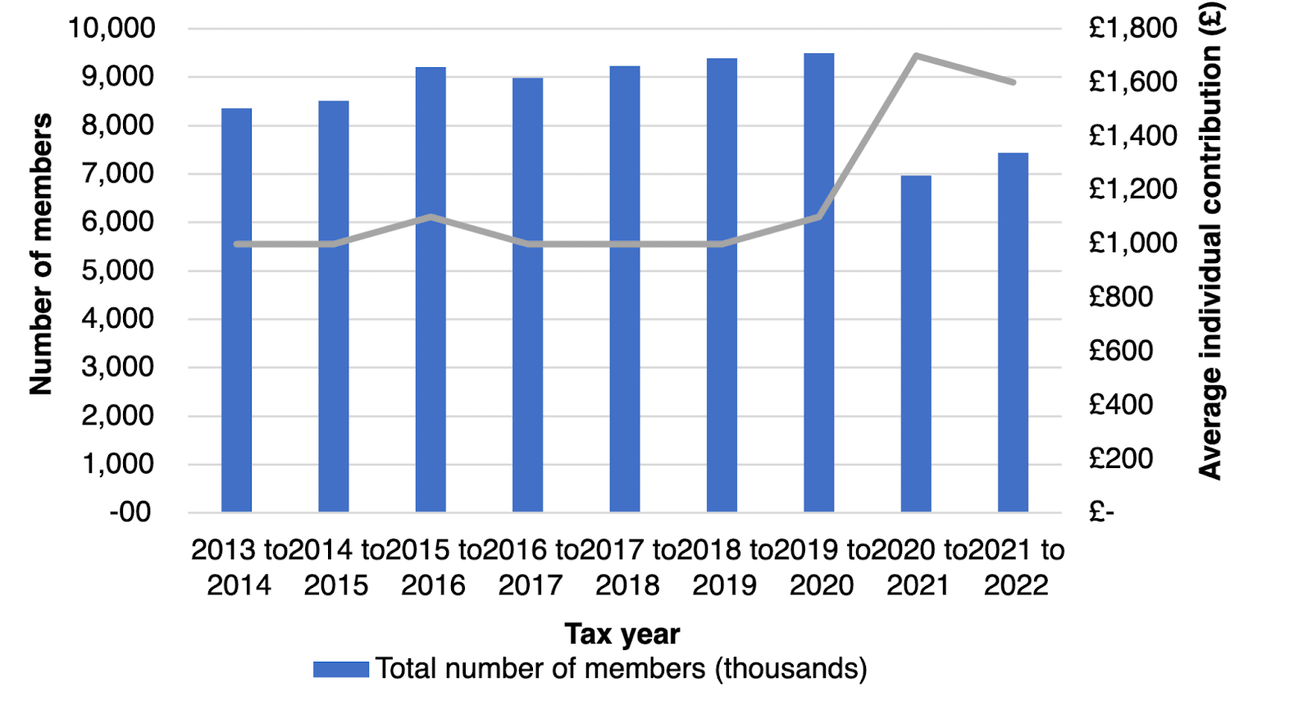
Personal and stakeholder pensions followed a different path: membership and average contributions dipped during the coronavirus pandemic, when some people paused contributions. The chart below shows that trend up to 2022:
Source: UK Gov
Why it’s helpful to know the average UK pension pot
One of the most important reasons this information is useful is that it helps you better plan and prepare for your retirement. Knowing where you stand relative to UK averages and recognised retirement benchmarks allows you to assess whether your savings trajectory is on track or whether catch-up contributions may be warranted.
Even if retirement feels many years away, the steps you take today (increasing contributions, choosing low-cost diversified investments, taking advantage of employer matching, and minimising fees) can make a substantial difference to the quality of your retirement. Compounding investment growth over decades is one of the most powerful forces in personal finance, but it only works in your favour if you start contributing early and consistently.
According to the Pensions and Lifetime Savings Association (PLSA) Retirement Living Standards, now published by Pensions UK, these are the approximate yearly amounts needed for various standards of living in retirement. They assume you own your home outright:
| Household type | Minimum lifestyle | Moderate lifestyle | Comfortable lifestyle |
| Single retiree | £13,900 a year | £32,700 a year | £45,400 a year |
| Couple | £22,500 a year | £45,400 a year | £62,700 a year |
Source: Retirement Living Standards, Pensions UK, checked in October 2026.
Using a typical 4% withdrawal rate, here are the approximate pension pot sizes a single retiree would need to cover the gap between these living standards and the full new State Pension (about £12,548 a year in 2026/27):
- Minimum lifestyle: approximately £34,000 (the full new State Pension covers most of it, if you have 35 qualifying National Insurance years).
- Moderate lifestyle: approximately £504,000.
- Comfortable lifestyle: approximately £821,000.
These figures should be treated as rough benchmarks rather than precise targets, and pension income above your personal allowance is taxed, so you may need a larger pot. Actual retirement needs vary substantially based on housing situation (mortgage paid off vs renting), location (London and the South East have significantly higher cost of living), health, lifestyle preferences, and whether you have additional income sources such as a defined benefit pension or part-time work in retirement.
Tips for boosting the size of your pension pot
Now that you’ve got a better understanding of the statistics around average pension pot sizes in the UK, here are some practical ways to try to build an above-average pension pot for your retirement:
- Start early: this may be out of your control depending on your current age, but the earlier you start, the more time compound investment growth has to work in your favour. Even modest contributions in your 20s can outperform much larger contributions started in your 40s thanks to decades of compounding.
- Maximise employer matching: many employers match contributions above the statutory minimum (some up to 6% or more). If your employer offers matching, contributing enough to capture the full match instantly adds to your pot before any investment growth.
- Open a SIPP: if you’re already maxing out workplace pension contributions or want greater investment flexibility, consider opening a Self-Invested Personal Pension (SIPP) as an additional retirement pot. SIPPs offer broader investment choice (ETFs, individual stocks, bonds, funds) and the same 25% tax-free lump sum at retirement (capped at £268,275 across all your pensions). UK SIPP providers worth comparing include InvestEngine, AJ Bell, Hargreaves Lansdown and Vanguard. See our guide to the best SIPP providers.
- Consolidate your pensions: keeping all your pensions under one provider can simplify management, reduce duplicate platform fees, and give you a clearer picture of your overall position. Be sure to check exit fees and lost benefits (like guaranteed annuity rates) before transferring.
- Minimise fees: with some workplace pensions, you cannot choose the provider, but where you have flexibility, prioritise low-fee providers and low-cost index funds. Over 40 years, an extra 1% a year in fees can leave your final pot around 20% to 30% smaller.
- Review your investment allocation: most people leave their pension on the default fund without realising it may be too conservative for their age. Younger workers (in their 20s and 30s) can typically afford higher equity allocations for long-term growth, while those approaching retirement may benefit from a more balanced approach. Review your allocation periodically.
- Claim higher-rate and additional-rate tax relief: if you’re a higher-rate (40%) or additional-rate (45%) taxpayer, you can claim the extra tax relief on personal pension contributions through your self-assessment tax return.
- Track down lost pensions: many UK workers have small pension pots with previous employers they’ve forgotten about. The Pension Tracing Service from the UK government can help you locate them.
Bottom line on average pension pots in the UK
Your pension should form the backbone of your long-term finances. Unless you’re approaching retirement, you don’t need to check your investments daily or weekly. In fact, frequent monitoring often leads to counterproductive emotional decisions. Instead, take time to understand your pension thoroughly and review it periodically (annually is typically enough for most workers) to make sure everything is on track.
Across the UK, there are wide differences in average pension pot sizes based on age, gender, region, and pension type. Some elements (employer, available auto-enrolment scheme, regional cost of living) will be outside your immediate control, but understanding the averages allows you to compare your position with peers in your age bracket and identify whether catch-up contributions might be warranted.
If you’re behind, the good news is that UK pensions offer one of the most tax-efficient savings vehicles available: contributions receive tax relief at your marginal rate, growth is tax-free within the wrapper, and you can take 25% as a tax-free lump sum (up to £268,275) from age 55, rising to 57 from April 2028. Keep in mind that from April 2027, unused pension funds will generally count towards your estate for inheritance tax. Increasing your contributions even modestly can have a substantial compounding effect over time.
The most important takeaway: it’s better to be aware of where you stand and take proactive steps, even small ones, than to bury your head in the sand. Whether that means raising your auto-enrolment contributions by 1%, opening a SIPP, consolidating old pensions, or simply reviewing your fund allocation, every small step compounds into meaningful retirement income over decades. For personalised advice, consider consulting an FCA-regulated independent financial adviser (IFA), particularly if you’re close to retirement, have multiple pension pots, or have complex circumstances.







