



Founded in 2011, SoFi Technologies, Inc. (NASDAQ: SOFI), commonly known as SoFi, is a US-based personal finance company and digital bank. It first gained popularity for offering more affordable student loan refinancing, but has since grown into a one-stop shop for digital financial services, spanning lending, banking, investing (via SoFi Invest), credit cards, insurance, and even a technology platform that powers other fintechs.
SoFi has grown rapidly: it reached 15.8 million members at the end of June 2026 (up 35% year-on-year), reported a record $1.2 billion in quarterly net revenue in Q2 2026 and has now been profitable under US accounting rules (GAAP, generally accepted accounting principles) for eleven consecutive quarters. In this article, we examine the SoFi statistics that matter most (members, revenue, assets, valuation and more) to show how the company has scaled and the impact it’s had on the digital banking and investing industry.
Whether you’re a current or potential SoFi user, a SOFI shareholder, or simply interested in the fintech sector, keep reading to discover the latest SoFi statistics for 2026.
Overview
SoFi is a US-based personal finance company and digital bank, best known for its checking and savings accounts, lending products, and investment services. Before SoFi went public in 2021, CEO Anthony Noto clearly defined his ambition for the company to be a “one-stop shop” for financial services. It targets the gap between traditional brick-and-mortar banks and online brokerages by combining banking, wealth management, and lending in a single app.
Here are some key corporate facts about SoFi:
- Founded: 2011
- Headquarters: San Francisco, California, US
- IPO date: June 1, 2021 (via a merger with Social Capital Hedosophia V, a special purpose acquisition company or SPAC)
- Listed exchange: NASDAQ
- Ticker: SOFI
- Sector: Financial services / fintech
- Business segments: Lending, Financial Services, and Technology Platform
- Founders: Mike Cagney, Dan Macklin, James Finnigan, and Ian Brady
- CEO: Anthony Noto
- Number of employees: approximately 6,100 (end of 2025)
- Key subsidiaries: SoFi Bank N.A., Galileo Financial Technologies, Technisys
Ownership
SoFi went public in June 2021, and its stock (NASDAQ: SOFI) has an ownership structure made up of institutional investors, retail investors, and company insiders. According to TipRanks, exchange traded funds (ETFs), mutual funds and other institutional investors hold about a third of the shares, while public companies and individual investors hold around two thirds. That is a large retail base for a company of SoFi’s size. Other data providers classify holdings differently: Stock Analysis, for example, puts institutional ownership at about 51%.
| Investor Type | Ownership (approx.) |
| Public Companies and Individual/Retail Investors | 66% |
| ETFs | 14% |
| Mutual Funds | 11% |
| Other Institutional Investors | 8% |
| Insiders | 1% |
Source: TipRanks, October 2026.
As of October 2026, Vanguard is the largest single institutional investor in SoFi, with about 8.4% of the shares across its funds, followed by BlackRock’s iShares ETFs (about 2.5%). CEO Anthony Noto is the largest individual shareholder, with close to 1%. As passive asset managers, Vanguard and BlackRock hold their stakes primarily through index funds that track the broad market, rather than through active conviction in SoFi specifically.
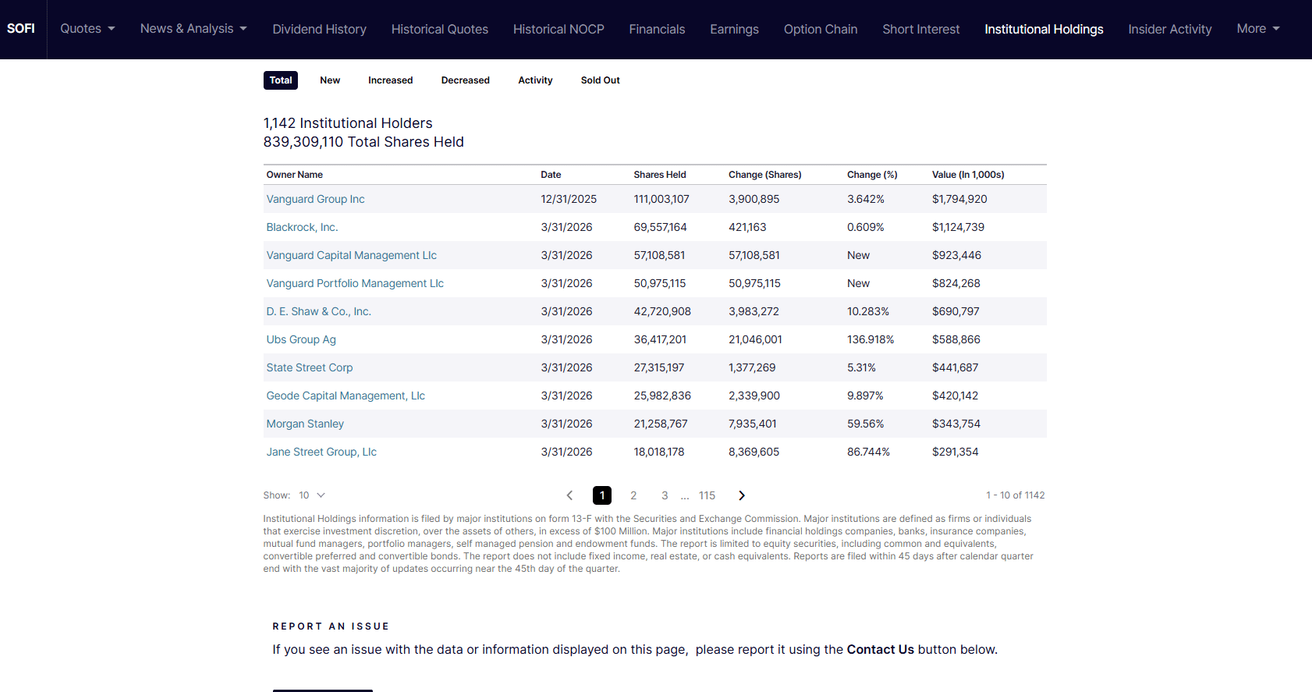
Source: Nasdaq
SoFi AUMs
SoFi’s assets have grown rapidly as the company has scaled its banking and lending operations. It’s worth distinguishing two different measures: the assets under management (AUM) within SoFi Invest (its brokerage and wealth arm), and total assets on the company’s balance sheet (which reflect its growth as a bank). On the balance sheet side, SoFi’s total assets have grown dramatically, from around $9 billion in 2021 to over $50 billion by the end of 2025 and $60.9 billion at the end of June 2026, driven by deposit growth following its 2022 bank charter. Deposits reached $45.5 billion in Q2 2026.
| Year | Total assets |
| Q2 2026 | $60.9 billion |
| 2025 | $50.66 billion |
| 2024 | $36.25 billion |
| 2023 | $30.07 billion |
| 2022 | ~$19 billion |
| 2021 | ~$9 billion |
Since SoFi only went public in 2021, detailed asset data for the preceding years is limited. For the years since, the figures above are drawn from SoFi’s annual reports and quarterly releases. Total assets are mainly the loans SoFi holds, funded largely by the deposits in its Checking and Savings accounts. Brokerage assets in SoFi Invest are client assets and are not part of the balance sheet.
SoFi Users
By the end of 2025, SoFi had 13.7 million members, a 35% year-over-year increase from 10.1 million a year earlier, after adding a record 1 million members in Q4 2025. Growth then accelerated: SoFi added about 1.05 million members in Q1 2026 and a record 1.1 million in Q2 2026, reaching 15.8 million members at the end of June 2026. SoFi defines these users as “SoFi members,” following the principle that once someone becomes a member, they remain one unless they violate the terms of service. It’s worth noting that not all members are necessarily active users at any given time.
This sustained growth reflects SoFi’s “one-stop shop” strategy and its Financial Services Productivity Loop (FSPL): the idea that offering members multiple products deepens engagement and cross-selling. Total products reached 20.2 million at the end of 2025 (up 37% year-over-year) and 24.4 million at the end of June 2026 (up 42%). In Q4 2025, 40% of new products were opened by existing members.
| Period | SoFi Members (in thousands) |
| Q1-2019 | 704 |
| Q2-2019 | 759 |
| Q3-2019 | 864 |
| Q4-2019 | 976 |
| Q1-2020 | 1,086 |
| Q2-2020 | 1,204 |
| Q3-2020 | 1,501 |
| Q4-2020 | 1,851 |
| Q1-2021 | 2,281 |
| Q2-2021 | 2,560 |
| Q3-2021 | 2,937 |
| Q4-2021 | 3,460 |
| Q1-2022 | 3,868 |
| Q2-2022 | 4,319 |
| Q3-2022 | 4,743 |
| Q4-2022 | 5,223 |
| Q1-2023 | 5,656 |
| Q2-2023 | 6,240 |
| Q3-2023 | 6,957 |
| Q4-2023 | 7,542 |
| Q4-2024 | 10,127 |
| Q1-2025 | 10,916 |
| Q2-2025 | 11,746 |
| Q3-2025 | 12,642 |
| Q4-2025 | 13,654 |
| Q1-2026 | 14,706 |
| Q2-2026 | 15,814 |
Source: SoFi quarterly earnings releases. Data for Q1 to Q3 2024 is not shown.
SoFi Revenues
SoFi generates revenue through three primary business segments: Lending, Financial Services, and Technology Platform. The Lending segment earns income through interest and fees on personal, student, and home loans. The Financial Services segment generates revenue primarily through fees and net interest from SoFi Invest, Checking and Savings, the SoFi Credit Card, and its loan platform business. The Technology Platform segment (built around Galileo and Technisys) earns revenue from services provided to other financial and non-financial institutions.
For the full year 2025, SoFi reported record adjusted net revenue of $3.59 billion, up 38% year-over-year (GAAP net revenue of $3.61 billion), and surpassed $1 billion in quarterly revenue for the first time in Q4 2025. Growth continued in 2026: GAAP net revenue was $1.10 billion in Q1 and a record $1.22 billion in Q2 2026, up 43% year-over-year. After the Q2 results, SoFi raised its 2026 guidance to adjusted net revenue of $4.75 billion to $4.85 billion.
A key theme in 2025 was the shift toward fee-based and capital-light revenue. Full-year fee-based revenue reached $1.54 billion (up 59%), and the combined Financial Services and Technology Platform segments grew to represent a record share of total revenue. The segment breakdown for 2025:
- Lending: adjusted net revenue grew 24% year-over-year to $1.8 billion (56% margin), with $36.4 billion in loans originated, including a record $10.5 billion in Q4. Originations rose further to $14.8 billion in Q2 2026.
- Financial Services: became one of SoFi’s fastest-growing segments, with Q4 2025 net revenue of $456.7 million, up 78% year-over-year, reflecting strong growth in deposits, SoFi Money and fee income.
- Technology Platform: Q4 2025 net revenue grew 19% year-over-year to $122.4 million, with a 39% contribution margin. In Q2 2026, segment revenue fell 23% year-over-year to $84.5 million after a large client moved off the platform.
| Period | SoFi total net revenue (GAAP) |
| 2018 | $240 million |
| 2019 | $451 million |
| 2020 | $621 million |
| 2021 | $985 million |
| 2022 | $1,536 million |
| 2023 | $2,122 million |
| 2024 | $2,675 million |
| 2025 | $3,613 million |
| H1 2026 | $2,319 million |
Below, we will present the quarterly revenue figures for SoFi.
| Period | Total net revenue |
| Q4-2019 | $62 million |
| Q1-2020 | $86 million |
| Q2-2020 | $136 million |
| Q3-2020 | $217 million |
| Q4-2020 | $182 million |
| Q1-2021 | $216 million |
| Q2-2021 | $237 million |
| Q3-2021 | $277 million |
| Q4-2021 | $280 million |
| Q1-2022 | $322 million |
| Q2-2022 | $356 million |
| Q3-2022 | $419 million |
| Q4-2022 | $443 million |
| Q1-2023 | $460 million |
| Q2-2023 | $489 million |
| Q3-2023 | $531 million |
| Q4-2023 | $594 million |
| Q1-2024 | $645 million |
| Q2-2024 | $597 million |
| Q3-2024 | $697 million |
| Q4-2024 | $734 million |
| Q1-2025 | $772 million |
| Q2-2025 | $855 million |
| Q3-2025 | $962 million |
| Q4-2025 | $1,025 million |
| Q1-2026 | $1,100 million |
| Q2-2026 | $1,219 million |
Average Revenues Per User
The Average Revenue Per User (ARPU) is a critical metric for evaluating a company’s revenue generation efficiency. Here, we calculate it by dividing SoFi’s total net revenue for the year by the number of members at the end of that year.
| Period | SoFi average revenue per member |
| 2019 | $462 |
| 2020 | $335 |
| 2021 | $292 |
| 2022 | $295 |
| 2023 | $283 |
| 2024 | $261 |
| 2025 | $265 |
The figures show that SoFi’s average revenue per member has decreased over the years, falling from $462 in 2019 to around $265 in 2025. This metric provides useful insight into SoFi’s revenue generation and operational efficiency.
However, the decline doesn’t necessarily indicate weaker productivity. It largely reflects the fact that SoFi has grown its member base far faster than its revenue. As the company has scaled, many new members join with a single product (often a free Checking and Savings account) before gradually adopting additional products over time, which temporarily dilutes the per-member average.
Earlier surges in sign-ups, such as during the COVID-19 period in 2020, accelerated this effect. Encouragingly, the metric ticked back up slightly in 2025 (from $261 in 2024), suggesting that monetisation per member is beginning to improve as cross-buy rates rise and members deepen their relationships with the platform.
SoFi Profit
SoFi’s path to profitability has been a defining part of its story. The company posted a net loss of $484 million in 2021, narrowing to $320 million in 2022 and $301 million in 2023. It achieved its first profitable quarter in Q4 2023, and then in 2024 delivered its first full year of GAAP profitability, with net income of $499 million (helped by a one-off deferred tax benefit).
In 2025, SoFi confirmed this was no fluke, reporting full-year GAAP net income of $481 million, its second consecutive profitable year and the first driven by operating performance rather than one-time tax items. In 2026, SoFi earned $167 million in Q1 and $157 million in Q2 (up 61% year-over-year), extending its run to eleven consecutive profitable quarters since Q4 2023.
| Period | SoFi GAAP net income (loss) |
| 2019 | -$240 million |
| 2020 | -$224 million |
| 2021 | -$484 million |
| 2022 | -$320 million |
| 2023 | -$301 million |
| 2024 | +$499 million |
| 2025 | +$481 million |
| H1 2026 | +$323 million |
SoFi Products
As highlighted above, SoFi operates in three main segments: Lending, Financial Services, and Technology Platform. In the Lending segment, SoFi offers three core products: personal loans, student loans, and home loans. The Technology Platform segment is built around Galileo, which provides payment and banking technology services to financial and non-financial institutions, and Technisys, a cloud-native digital banking platform, together enabling SoFi to power other fintechs and banks on a “banking-as-a-service” basis.
The Financial Services segment encompasses products such as SoFi Checking and Savings, SoFi Invest, and the SoFi Credit Card, providing digital banking, investing, and credit. SoFi also offers a range of complementary services, including loan referrals via its Loan Platform Business, personal finance management through SoFi Relay, employer-based financial benefits through SoFi At Work, and insurance through SoFi Protect. In 2025, SoFi further expanded its offering with crypto and blockchain products, alongside international remittances and the new SoFi Smart Card. In December 2025, it launched SoFiUSD, a fully reserved stablecoin issued by SoFi Bank.
| Year | Lending Products | Financial Services Products | Technology Platform Accounts |
| 2019 | 798,005 | 387,357 | n/a |
| 2020 | 917,645 | 1,605,910 | 59,735,210 |
| 2021 | 1,078,952 | 4,094,245 | 99,660,657 |
| 2022 | 1,340,597 | 6,554,039 | 130,704,351 |
| 2023 | 1,663,000 | 9,479,000 | 145,000,000 |
| 2024 | 2,000,000 | 12,700,000 | 167,700,000 |
| 2025 | 2,600,000 | 17,500,000 | 128,500,000 |
| Q2 2026 | 3,093,359 | 21,287,615 | 134,800,000 |
Source: SoFi quarterly results (Q4 2025 and Q2 2026 releases). Technology Platform accounts fell in 2025 after a large client moved off the platform.
Below, we will look more closely into the Lending Products and Financial Services Products:
| Qtr | Lending Products | Financial Services Products |
| Q3-2019 | 0.752 million | 0.268 million |
| Q4-2019 | 0.798 million | 0.387 million |
| Q1-2020 | 0.842 million | 0.601 million |
| Q2-2020 | 0.862 million | 0.783 million |
| Q3-2020 | 0.893 million | 1.160 million |
| Q4-2020 | 0.918 million | 1.606 million |
| Q1-2021 | 0.945 million | 2.239 million |
| Q2-2021 | 0.981 million | 2.686 million |
| Q3-2021 | 1.031 million | 3.237 million |
| Q4-2021 | 1.079 million | 4.094 million |
| Q1-2022 | 1.139 million | 4.724 million |
| Q2-2022 | 1.202 million | 5.362 million |
| Q3-2022 | 1.280 million | 5.919 million |
| Q4-2022 | 1.341 million | 6.554 million |
| Q1-2023 | 1.416 million | 7.138 million |
| Q2-2023 | 1.504 million | 7.897 million |
| Q3-2023 | 1.594 million | 8.854 million |
| Q4-2023 | 1.663 million | 9.479 million |
| Q4-2024 | 2.000 million | 12.700 million |
| Q1-2025 | 2.130 million | 13.786 million |
| Q2-2025 | 2.270 million | 14.900 million |
| Q3-2025 | 2.463 million | 16.090 million |
| Q4-2025 | 2.600 million | 17.500 million |
| Q1-2026 | 2.831 million | 19.328 million |
| Q2-2026 | 3.093 million | 21.288 million |
Taking a closer look, it’s evident that SoFi has significantly expanded its Financial Services segment. Comparing Q3-2019, when SoFi had 268 thousand Financial Services products, to a year later, the number surged to 1.606 million, a year-over-year increase of nearly 500%. By the end of June 2026, the Financial Services segment had grown to 21.3 million products, far ahead of the Lending segment’s 3.1 million. Lending products have also grown steadily, up 36% year-over-year in Q2 2026.
Let’s now take a closer look at the main contributors within each segment at the end of June 2026:
Q2 2026: Financial Services segment
| Product | Q2 2026 total |
| Money | 7.89 million |
| Relay | 7.99 million |
| Invest | 3.93 million |
| Credit Card and other | 1.47 million |
Q2 2026: Lending segment
| Lending Product | Total (Q2 2026) |
| Personal Loans | 2.325 million |
| Student Loans | 0.703 million |
| Home Loans | 0.065 million |
Source: SoFi Q2 2026 earnings release.
Valuation
SoFi’s growth is also reflected in its market valuation. The company’s market capitalisation has been volatile since its 2021 SPAC debut: ended 2021 at about $13 billion, then fell sharply to roughly $3.7 billion by the end of 2022 amid the broader sell-off in growth and fintech stocks and concerns over the student loan moratorium. Since then, as SoFi reached sustained profitability, its valuation has recovered strongly. As of 7 October 2026, SoFi’s market capitalisation stands at about $20.2 billion, with the stock at $15.66. That is well above its 2022 lows, but below the roughly $34 billion it was worth at the end of 2025.
SoFi’s valuation continues to attract debate among analysts. Bulls point to its eleven consecutive quarters of GAAP profitability, rapid growth in fee-based revenue, and expanding member base. Bears note that the stock trades at a premium to many traditional banks, with a price-to-book ratio of about 1.8, leaving little room for execution missteps. As of October 2026, the consensus of 25 analysts is “Hold”, with an average 12-month price target of about $20.
| Year | Valuation |
| 2015 (Jan)** | $1.10 billion |
| 2017 (Feb)** | $3.80 billion |
| 2019 (May)** | $4.30 billion |
| 2021* | $12.99 billion |
| 2022* | $3.68 billion |
| 2023* | $9.53 billion |
| 2024* | $17.34 billion |
| 2025* | $34.12 billion |
| 2026 (7 Oct)* | $20.2 billion |
*Market capitalisation at the end of each year, from CompaniesMarketCap.
**SoFi went public in June 2021. Earlier valuations are pre-money private funding valuations from Crunchbase.
Bottom Line
In summary, SoFi Technologies has established itself as a “one-stop shop” for digital financial services, bridging the gap between traditional banks and online brokerages. What began as a student loan refinancing startup in 2011 has grown into a nationally chartered US bank offering lending, banking, investing through SoFi Invest, credit cards, insurance, and even a technology platform that powers other fintechs.
Throughout this article, we explored the key statistics behind that growth, from a member base that reached 15.8 million in June 2026 (up 35% year-on-year), to record full-year revenue of $3.6 billion in 2025 and $1.2 billion in Q2 2026 alone, to eleven consecutive profitable quarters. SoFi’s trajectory illustrates how a digital-first model can scale rapidly and reshape the consumer finance industry, though, as with any high-growth company, investors continue to weigh its premium valuation against the risks of execution and competition.
This article is for informational purposes only and does not constitute financial or investment advice. All figures are based on publicly available data as of October 2026 and are subject to change.
FAQs
Is SoFi safe? Is my money with SoFi protected?
SoFi’s brokerage arm is a member of the Securities Investor Protection Corporation (SIPC), which protects securities and cash in a brokerage account if the broker fails, up to $500,000, including $250,000 for cash. SoFi Checking and Savings deposits are held at SoFi Bank and covered by Federal Deposit Insurance Corporation (FDIC) insurance up to $250,000 per depositor, per ownership category. Neither scheme protects you against investment losses.
Is SoFi regulated?
Yes. SoFi Bank is a national bank supervised by the Office of the Comptroller of the Currency (OCC), and SoFi’s brokerage business is regulated by the Securities and Exchange Commission (SEC) and the Financial Industry Regulatory Authority (FINRA).
Does SoFi work internationally?
No, SoFi isn’t available internationally. Only US and HK residents are allowed to open an account with SoFi.
1Includes SoFi Checking and Savings accounts held at SoFi Bank and cash management accounts.







