Trading 212 pays interest on uninvested cash in several currencies. New clients of Trading 212 EU GmbH currently get a 4.2% promotional rate on EUR for 4 months, while clients of Trading 212 Markets Ltd (CySEC) earn 2.50% on EUR, and clients in general earn 3.30% on USD and 3.55% on GBP (rates checked in September 2026, variable):
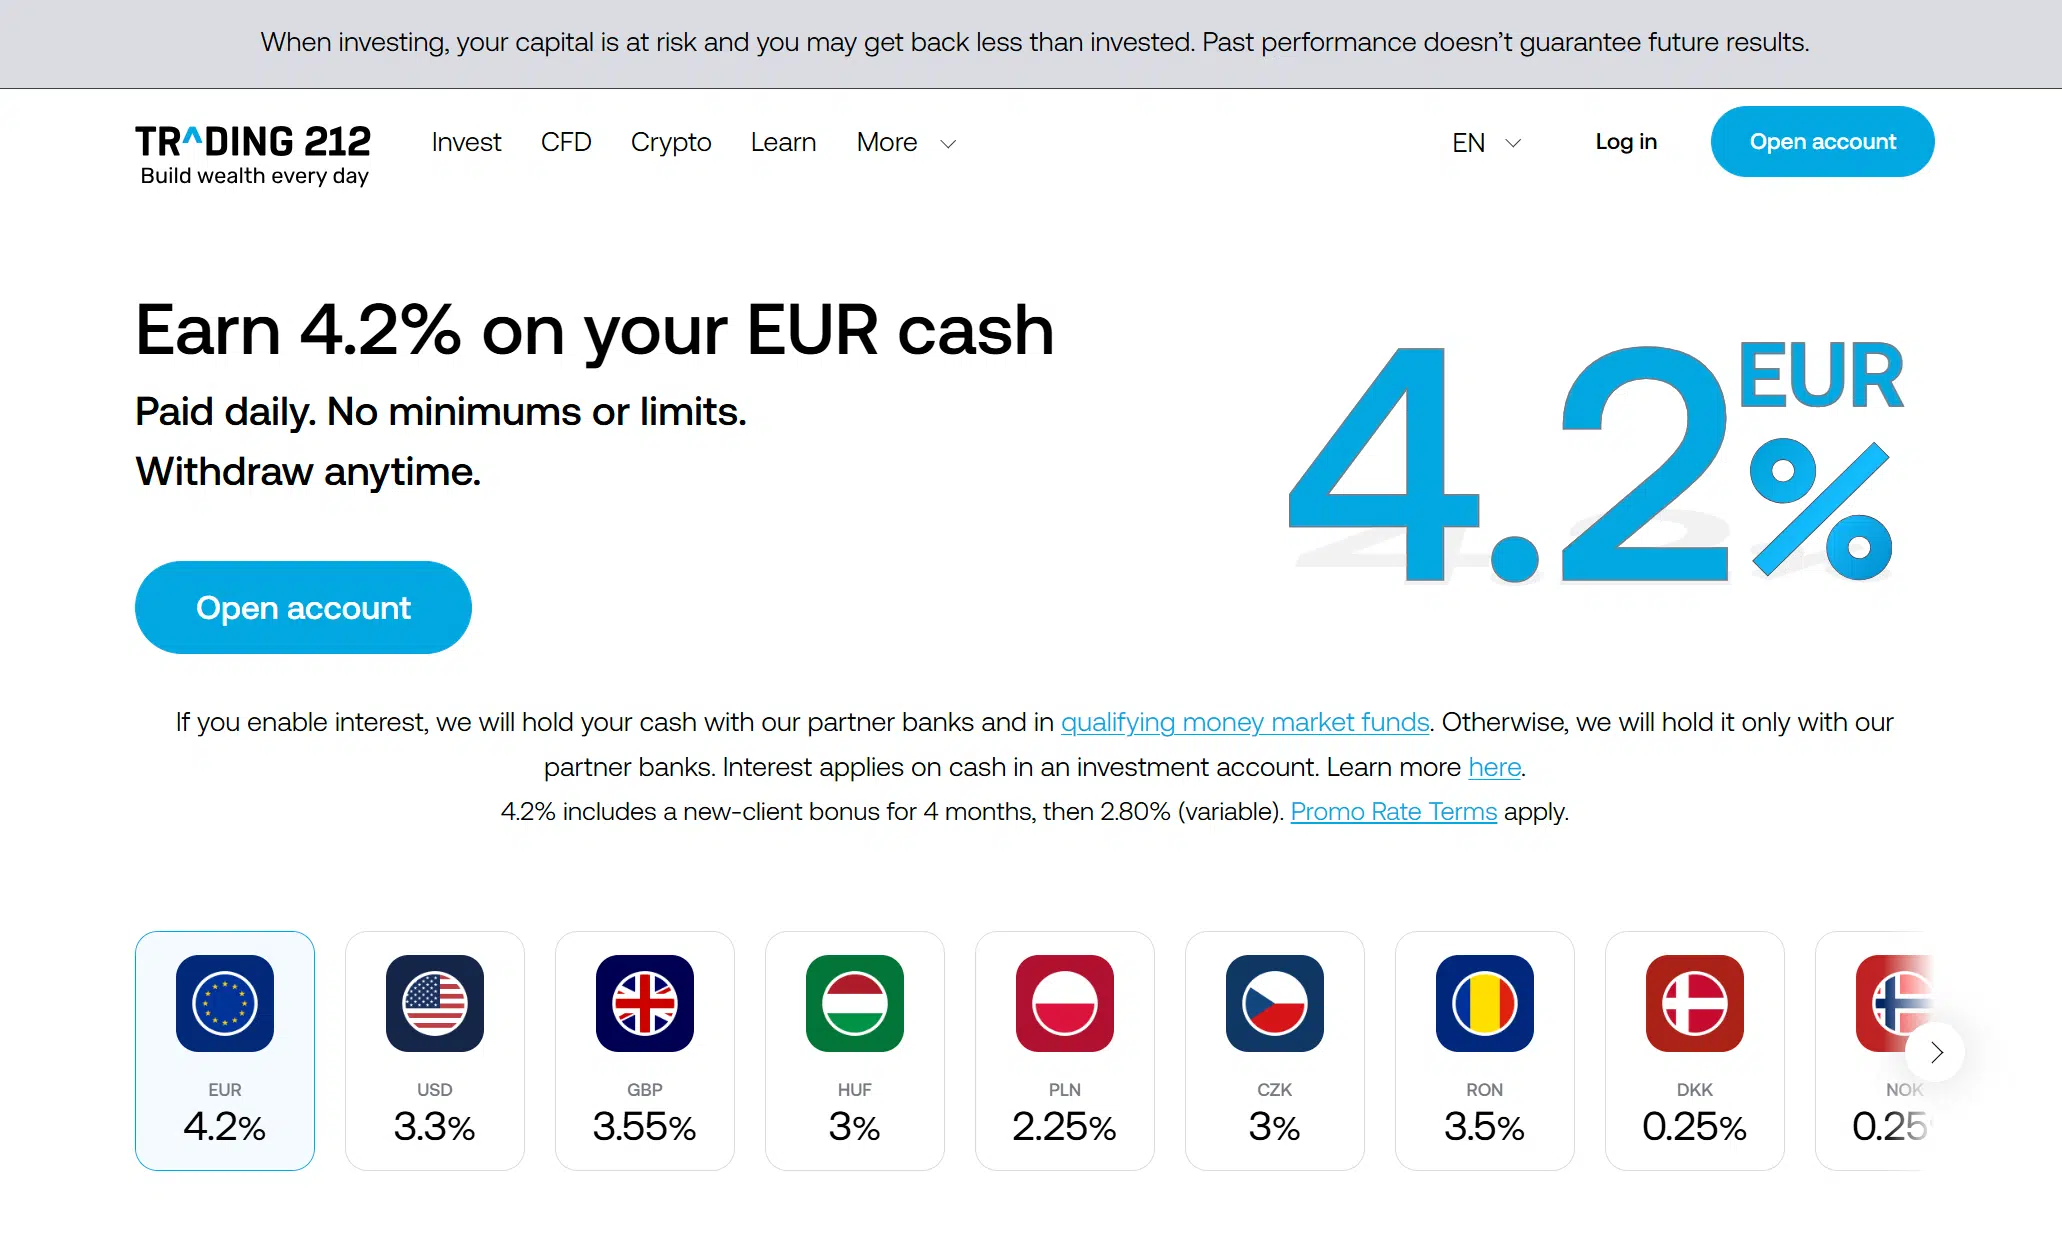
When investing, your capital is at risk. If you enable interest, Trading 212 will hold your cash in qualifying money market funds and banks. Otherwise, your cash will be held only in banks. Interest applies on cash in an investment account. Terms apply. The rates shown may no longer be current. Please refer to Trading 212’s Terms and Fees page for the live rates.
How are the rates set? How does protection work? What is the difference between an APY and an APR? Is there a catch? Let’s take a look.
What interest is Trading 212 offering?
The answer depends on the currency and on the Trading 212 entity that holds your account, which depends on your country of residence. Each rate follows the policy of the corresponding central bank. For example, the EUR rate depends on the European Central Bank’s (ECB) decisions.
Trading 212 EU GmbH (BaFin)
New clients onboarded to Trading 212 EU GmbH, regulated in Germany by BaFin, get a 4.2% variable promotional rate on uninvested EUR for 4 months from activation. After that, the rate reverts to the standard variable EUR rate shown on the Terms and Fees page.
To qualify, you must:
- Be a new Trading 212 client (never held an account with any Trading 212 Group company).
- Open an Invest account with Trading 212 EU GmbH during the campaign period, which currently runs from 16 September to 2 November 2026 (Trading 212 may extend it).
- Within 10 calendar days, deposit at least the minimum amount shown on the Terms and Fees page and opt in to interest.
See the promotional rate terms for full details. Countries onboarded to Trading 212 EU GmbH include Austria, Denmark, Finland, France, Germany, Iceland, Ireland, Liechtenstein, Luxembourg, the Netherlands, Norway, Portugal (new clients since September 2026), Sweden and Switzerland. Existing clients in these countries who already had an account with another Trading 212 entity keep their account and their standard rate.
Trading 212 Markets Ltd (CySEC) and Trading 212 UK
These were the rates for other clients when we last checked (September 2026):
- EUR (euro): 2.50% (up from 2.40% on 16 September 2026, after the ECB rate rise)
- USD (US dollar): 3.30%
- GBP (British pound): 3.55%
- RON (Romanian leu): 3.50%
- CZK (Czech koruna): 3.00%
- HUF (Hungarian forint): 3.00%
- PLN (Polish zloty): 2.25%
- DKK (Danish krone), NOK (Norwegian krone) and SEK (Swedish krona): 0.25%
- CHF (Swiss franc) and CAD (Canadian dollar): 0.00%
Rates change often, so check the interest on cash page or the app for the current figures.
Looking for other brokers that pay interest? Check our broker interest tool.
How does Trading 212 pay these rates?
Trading 212 is not a bank. It holds your cash through a mix of “qualifying money market funds (QMMFs), time deposits and current accounts” with banks. Here’s what each one is:
Qualifying money market funds (QMMFs)
QMMFs are funds that invest in low-risk, short-term debt securities, such as government bonds, and aim to keep a stable value. They are called “qualifying” because they meet stricter rules on quality and liquidity, which allow them to be treated as cash equivalents.
Money market funds are widely used by pension funds, insurers and banks. According to ESMA’s 2023 market report, around €1.4 trillion was invested in EU money market funds.
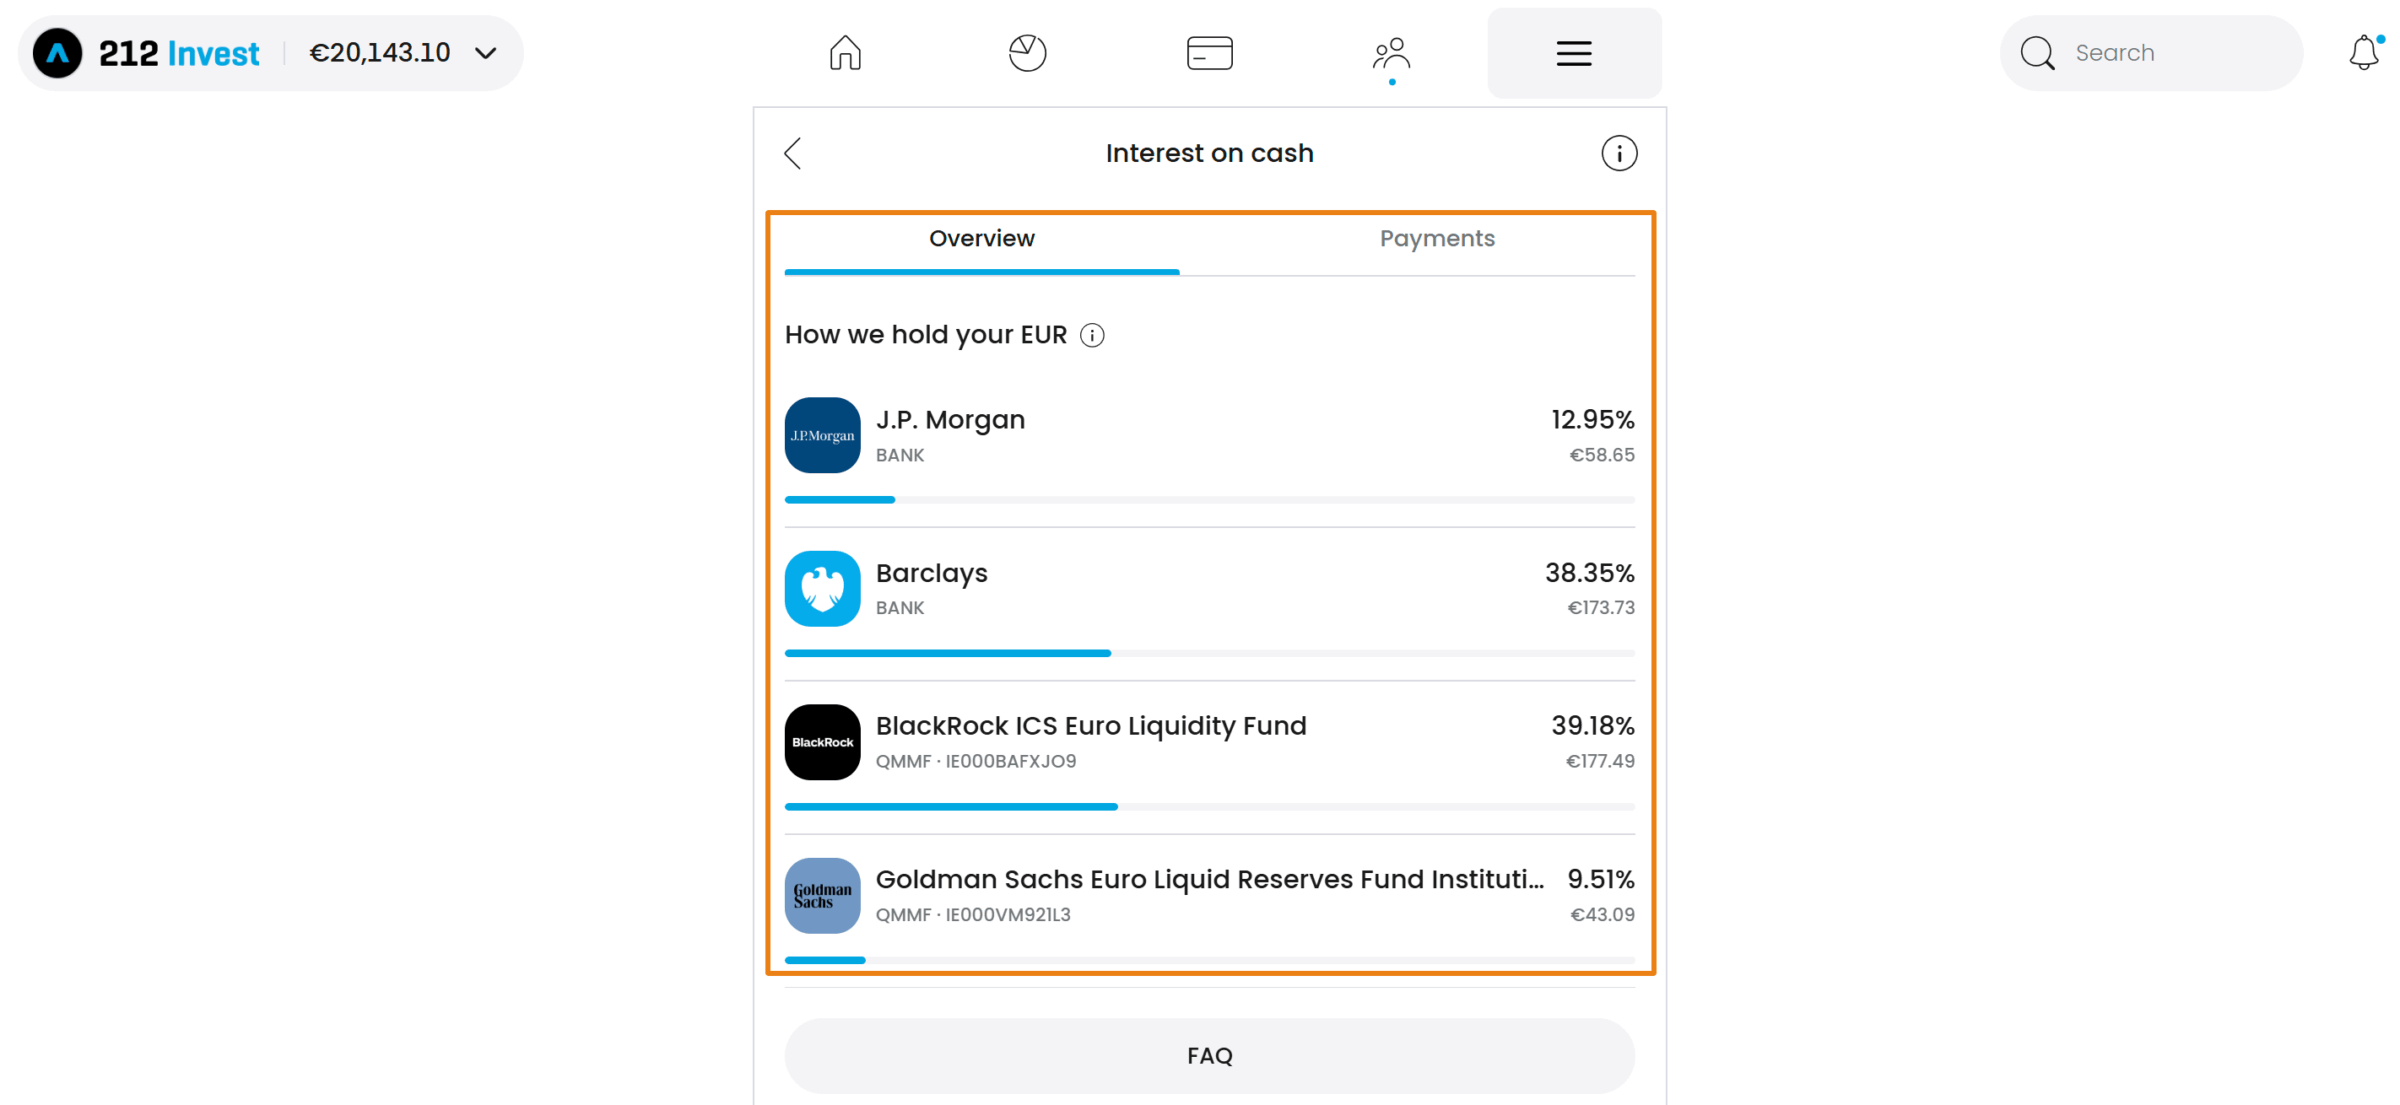
A common example used by other brokers is the BlackRock ICS Euro Liquidity Fund. Trading 212 does not publicly disclose which QMMFs it uses, but you can see in the app how your cash is split between banks and QMMFs.
Time deposits
A time deposit is a bank product where the depositor (Trading 212, in this case) places money for a fixed period to earn a set interest rate.
Current accounts
A current account is a standard bank account where money is simply held and available.
How does compensation work? What are the risks?
Compensation schemes
The scheme that applies depends on the Trading 212 entity and on where your cash is held:
- Trading 212 Markets Ltd (CySEC): eligible clients are covered by the Cyprus Investor Compensation Fund (ICF) up to €20,000.
- Trading 212 UK Ltd (FCA): eligible clients are covered by the Financial Services Compensation Scheme (FSCS) up to £85,000 for investment firms.
- Trading 212 EU GmbH (BaFin): cash held with a bank is covered by the applicable deposit guarantee scheme up to €100,000.
How these schemes apply depends on your circumstances and the type of service. They cover the failure of a firm, not investment losses.
Risks
Money placed in a QMMF is an investment, not a bank deposit, so deposit guarantee schemes don’t apply to it. QMMF holdings are kept separately from Trading 212’s own assets, which means they should not be available to Trading 212’s creditors if the company fails.
QMMFs are low-risk, but their value can still move. In rare situations, such as a financial crisis, a money market fund can lose value. There is no guarantee that you’ll get back the full amount.
Weigh the rate against these risks before enabling interest. You can read more in our article on Trading 212’s safety.
How can I start earning interest?
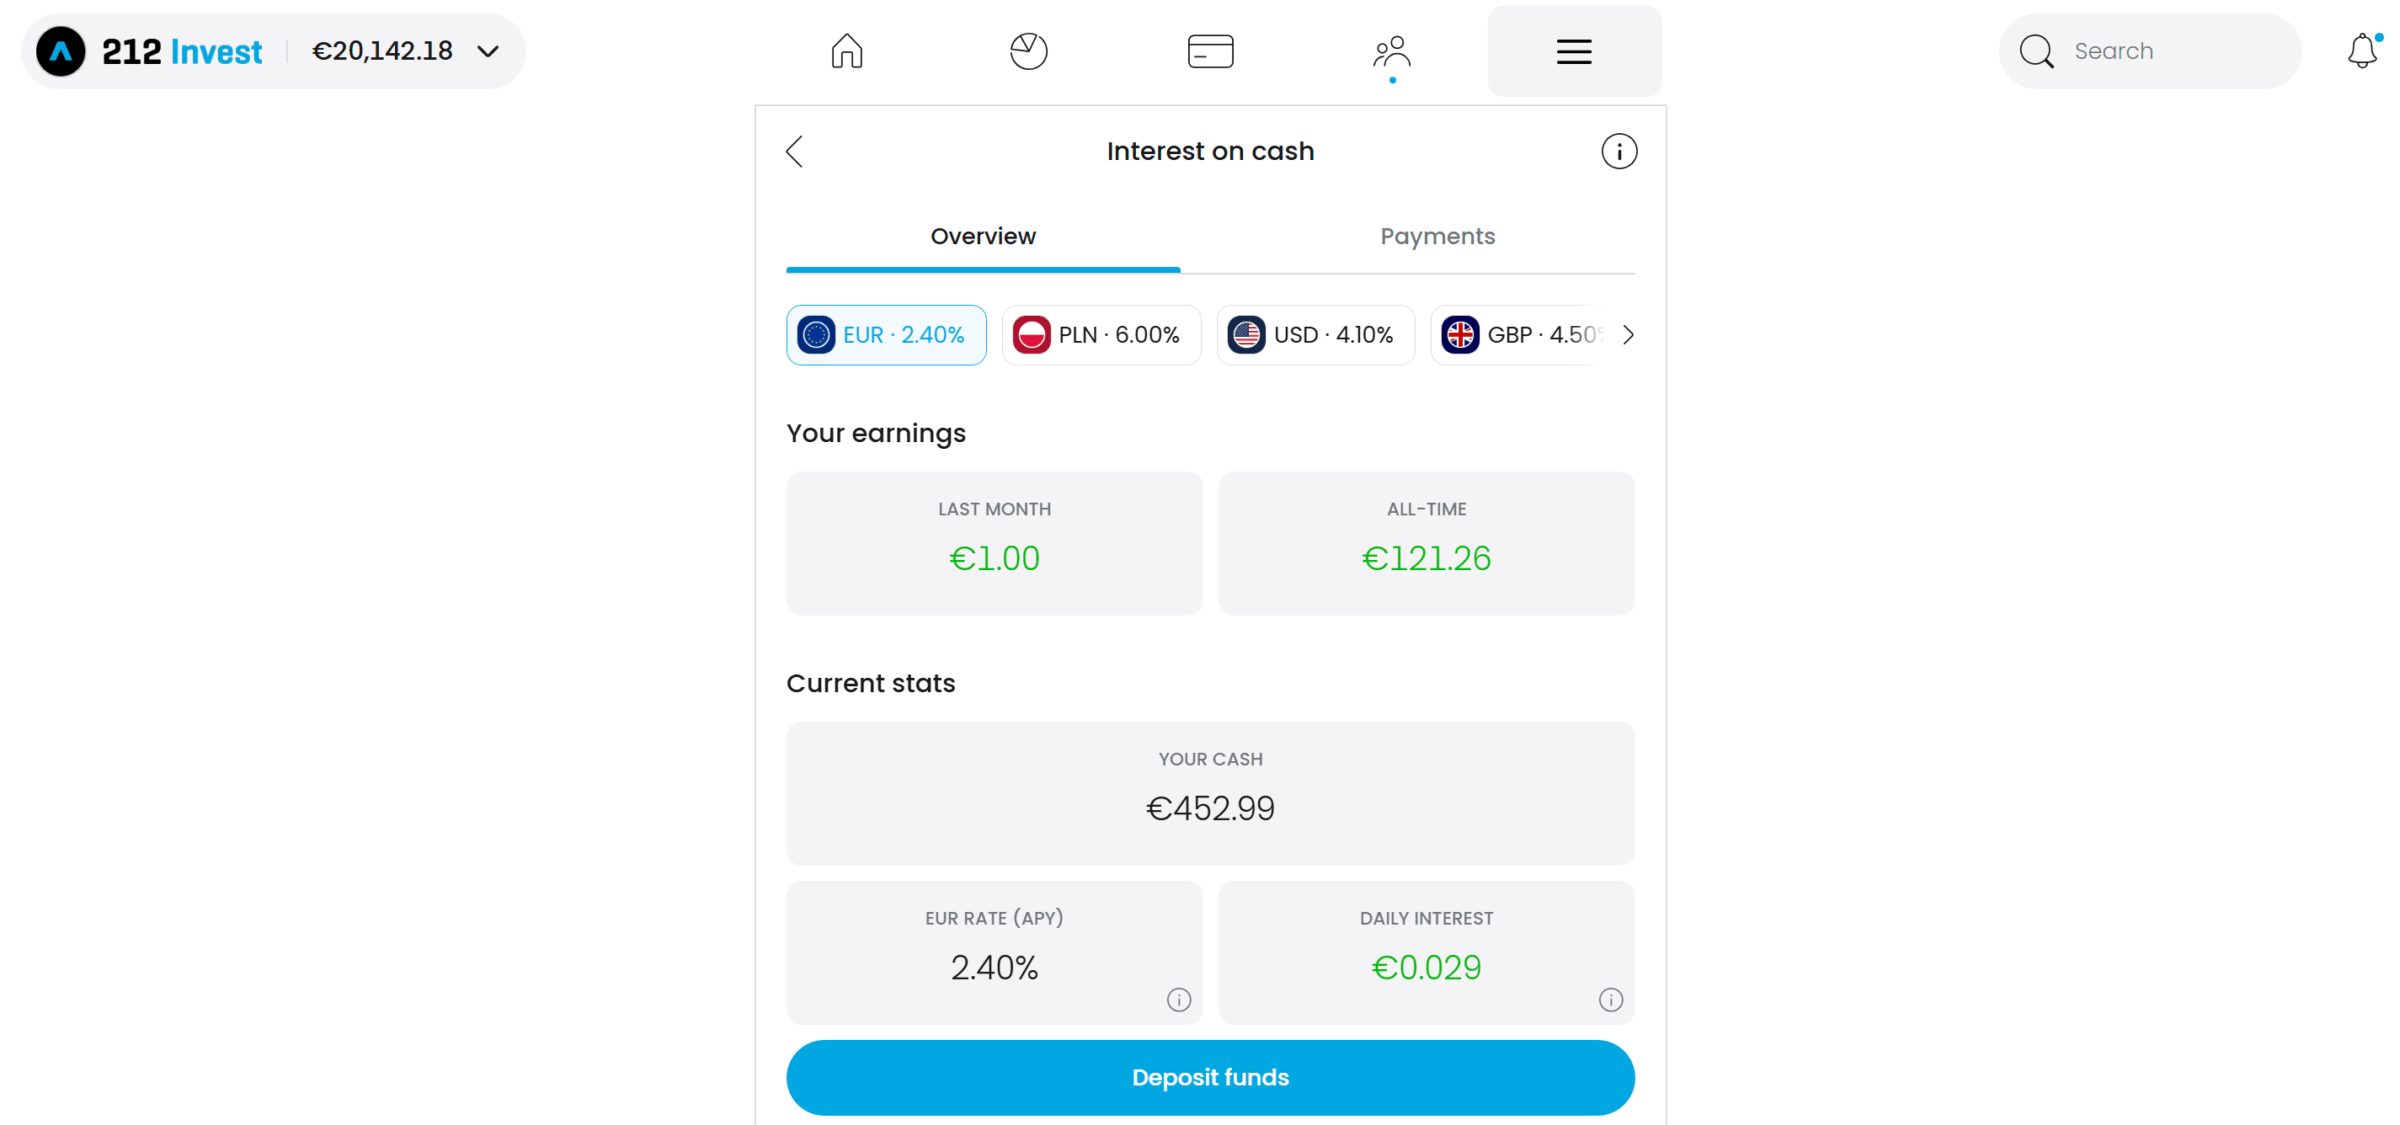
First, you need to enable interest on cash in the app:

Once it is enabled, you can deposit and start earning interest right away:
In the same dashboard, you can see how much of your money is held with banks and how much in QMMFs:
Are Trading 212 interest rates fixed or variable?
They are variable. The rates depend on what Trading 212 earns from its banks and QMMFs, which follow the central banks’ reference rates: the ECB for EUR, the Bank of England for GBP and the US Federal Reserve for USD. The EUR promotional rate for new Trading 212 EU GmbH clients is also variable.
If a central bank raises or lowers its rates, the interest on cash will likely move in the same direction. For example, after the ECB’s September 2026 rise, Trading 212 Markets Ltd raised its EUR rate from 2.40% to 2.50%.
Trading 212’s interest rate is an APY: why does this matter?
Trading 212 quotes its rates as an Annual Percentage Yield (APY), also called the Annual Equivalent Rate (AER). This measure includes the effect of compounding, and Trading 212 pays and compounds interest daily.
Other brokers may quote an Annual Percentage Rate (APR), the nominal yearly rate that doesn’t include compounding. For example, Trade Republic pays existing clients the ECB deposit facility rate, 2.50% since 16 September 2026, as an APR with interest paid monthly.
To compare the two offers, convert them to the same measure. As an APY:
- Trading 212 (CySEC, EUR): 2.50%
- Trade Republic (existing clients): about 2.53% (2.50% APR compounded monthly)
As an APR:
- Trading 212 (CySEC, EUR): about 2.47% (2.50% APY compounded daily)
- Trade Republic (existing clients): 2.50%
In other words, at the same headline number, a rate quoted as an APR pays slightly more than one quoted as an APY. Let’s walk through the calculation with €1,000 of uninvested cash at Trading 212.
The general APY formula is:
(1 + r/n)n − 1, where:
- r = APR (nominal annual rate)
- n = number of compounding periods (365.25 days, as Trading 212 uses 365.25 to account for leap years)
The daily payment is calculated as:
Daily payment = cash balance × [(1 + APY)1/365.25 − 1]
With a €1,000 balance and a 2.50% APY:
- Daily payment = €1,000 × [(1.025)1/365.25 − 1]
- (1.025)1/365.25 ≈ 1.0000676
- Daily payment = €1,000 × 0.0000676 = €0.0676 per day
Trading 212 rounds daily interest down to the nearest cent and carries smaller amounts forward. Over a full year, €0.0676 × 365.25 = €24.69, or about 2.47% of €1,000. That is the APR equivalent of the 2.50% APY. The 0.03 percentage point difference comes from daily compounding. If you reinvested the daily interest, you would end the year with about €25.
Are there any limits?
Very few. Keep these points in mind:
- No minimum or maximum balance: you earn interest on your whole uninvested cash balance, whether it is €100 or €1,000,000.
- You can use your money whenever you need it, for withdrawals or investments, with no interest penalties.
- Interest is paid daily.
- The EUR promotional rate for new Trading 212 EU GmbH clients only applies to the Invest account, lasts 4 months and requires opting in to interest within 10 calendar days of opening the account.
Do I have to pay taxes on Trading 212 interest?
Yes, in most cases. Except for tax-advantaged accounts, such as the Stocks and Shares ISA in the UK, interest is usually taxable.
For German tax residents with Trading 212 EU GmbH, Trading 212 withholds the 25% capital income tax, plus the 5.5% solidarity surcharge and church tax where applicable. For other clients, interest is paid gross, and you’ll need to declare it in your country of residence.
This article is for Trading 212 clients in many countries, so we can’t cover each country’s rules or your personal circumstances. Check with your tax authority or a tax adviser.
What about the latest ECB decisions?
EUR cash rates at Trading 212 and its competitors follow ECB policy closely. The ECB raised its deposit facility rate from 2.00% to 2.25% in June 2026, and on 10 September 2026 it raised it again to 2.50%, with effect from 16 September 2026. Trading 212 Markets Ltd raised its EUR rate to 2.50% on the same day.
The deposit facility rate, the rate banks earn when they deposit money at the ECB, is a useful reference for what brokers can pay on EUR cash. The next ECB monetary policy decision is scheduled for 29 October 2026, so check the app for the current figures after that date.
Trading 212 alternatives for interest
If you’re looking for alternatives, see our lists of the best brokers and digital banks for interest on uninvested cash in EUR, USD and GBP.
Bottom line
Trading 212’s interest on uninvested cash is a convenient way to earn interest on money you are not investing yet, often at a higher rate than many retail banks pay. Keep in mind that rates are variable, that the EUR promotional rate only applies to new Trading 212 EU GmbH clients for 4 months, and that money in QMMFs is an investment, not a deposit. If you want to start investing, see our guide on how to invest in the S&P 500 with Trading 212.
Trading 212’s group companies are authorised by the Financial Conduct Authority (FCA) in the UK, the Cyprus Securities and Exchange Commission (CySEC), BaFin in Germany and the Financial Supervision Commission (FSC) in Bulgaria, among others.
If you hold cash in several currencies, remember that a 0,15% FX fee applies when converting funds. Other fees may apply. See terms and fees.
Do you have feedback or questions about Trading 212? Read our review and get in touch to share your experience. If you decide to open an account, you can use our promo code.
Sponsored content. When investing, your capital is at risk and you may get back less than invested. Past performance doesn’t guarantee future results. When investing, your capital is at risk. If you enable interest, Trading 212 will hold your cash in qualifying money market funds and banks. Otherwise, your cash will be held only in banks. Interest applies on cash in an investment account. Terms apply. The rates shown may no longer be current. Please refer to Trading 212’s Terms and Fees page for the live rates.