According to its 2025 annual report, Revolut ended 2025 with 68.3 million retail customers and $67.5 billion in customer balances, on revenue of $6.0 billion and pre-tax profit of $2.3 billion. It has grown quickly since: it passed 80 million customers during 2026 and was valued at around $75 billion in a secondary share sale in July 2026. On 11 March 2026 it also exited mobilisation and received its full UK banking licence.
It has built a huge audience that now has access to interest on uninvested cash in three currencies: EUR, USD and GBP.
Revolut calls this service “Savings”. In this article we take a deep dive into how you earn that interest, where it comes from, the risks involved and more. One thing has changed since we first wrote this guide: there are now two different products sitting behind that word, and only one of them is what most people would call a savings account. We cover both.
Key points
- Revolut offers two savings products in the EEA: Flexible Cash Funds, a money market fund, and Instant Access Savings, a real bank deposit;
- Flexible Cash Funds has no minimum or maximum amount, and you can add or withdraw money at any time;
- With Flexible Cash Funds you are investing in a money market fund managed by Fidelity, not depositing money in a bank account;
- You can set up recurring transfers into your savings every day, week or month;
- Flexible Cash Funds is covered by the Lithuanian investor insurance scheme up to €22,000, which protects against Revolut failing, not against investment losses;
- Flexible Cash Funds is not covered by the European deposit guarantee scheme of €100,000. Instant Access Savings is;
- Rates vary by plan: on the free Standard plan the fund pays 1.25% in EUR, 2.65% in GBP and 2.34% in USD, rising to 2.1% in EUR on the Ultra plan (Revolut’s published rates, 12 May 2026);
- Rates also vary with market conditions, are quoted after Revolut’s cut, and the return is compounded.
What is “Savings”?
There are several reasons to use Revolut: exchanging currencies, managing day-to-day money and investing. All of them have something in common: there’s usually some cash sitting idle in the account.
Savings is the feature that lets you earn a return on that cash, whether your balance is €1 or €1,000,000.
Inside the app, “Savings” now covers two products that work very differently:
- Flexible Cash Funds: your money buys units in a money market fund. This is the original product and the main subject of this article. The return is variable, it is quoted as an APY after Revolut’s cut, and it is an investment rather than a deposit;
- Instant Access Savings: your money stays as a deposit with Revolut Bank UAB. It pays a stated rate, and it carries the €100,000 deposit guarantee that the fund does not.
The distinction matters more than the names suggest, so we compare them side by side further down. For the rest of this section, “Savings” means Flexible Cash Funds.
What are the interest rates offered?
Rates depend on your plan and on market conditions. These are the Flexible Cash Funds rates per currency and plan that Revolut currently publishes:
| Currency and plan | Standard (free) | Plus | Premium | Metal | Ultra |
| EUR | 1.25% | 1.4% | 1.85% | 2% | 2.1% |
| USD | 2.34% | 2.59% | 3.09% | 3.34% | 3.69% |
| GBP | 2.65% | 2.9% | 3.4% | 3.65% | 3.8% |
Flexible Cash Funds APY as published by Revolut, dated 12 May 2026. This is the most recent table Revolut publishes on its EEA pricing pages, and the APY changes daily, so check the live figure in the app.
An important caveat on timing. Revolut’s published table is dated 12 May 2026, and euro rates have moved since: the European Central Bank raised its deposit facility rate to 2.25% on 17 June 2026 and again to 2.50% on 16 September 2026. A euro money market fund follows those moves with a lag of a few weeks, so the EUR figure you see in the app today should be meaningfully higher than the 1.25% in the table above. The sterling and dollar rates follow the Bank of England, which has held its base rate at 3.75%, and the Federal Reserve.
That lag is not a criticism of Revolut, it is how money market funds work: the fund holds paper with an average maturity of about 42 days, so it takes roughly that long for a new central bank rate to feed through into what you earn. The same is true on the way down.
How does Revolut offer these rates?
Revolut can offer these rates because it invests your money in money market funds. These funds hold low-risk, short-term debt, such as government bonds and commercial paper, and aim to keep a stable share price.
Money market funds are widely used by institutional investors, such as pension funds, insurers and banks. In Europe, more than a trillion euros are invested in these vehicles.
The fund Revolut uses for euro cash is the Fidelity Institutional Liquidity Fund, The Euro Fund, Class R Flex Distributing Shares (ISIN IE000AZVL3K0):
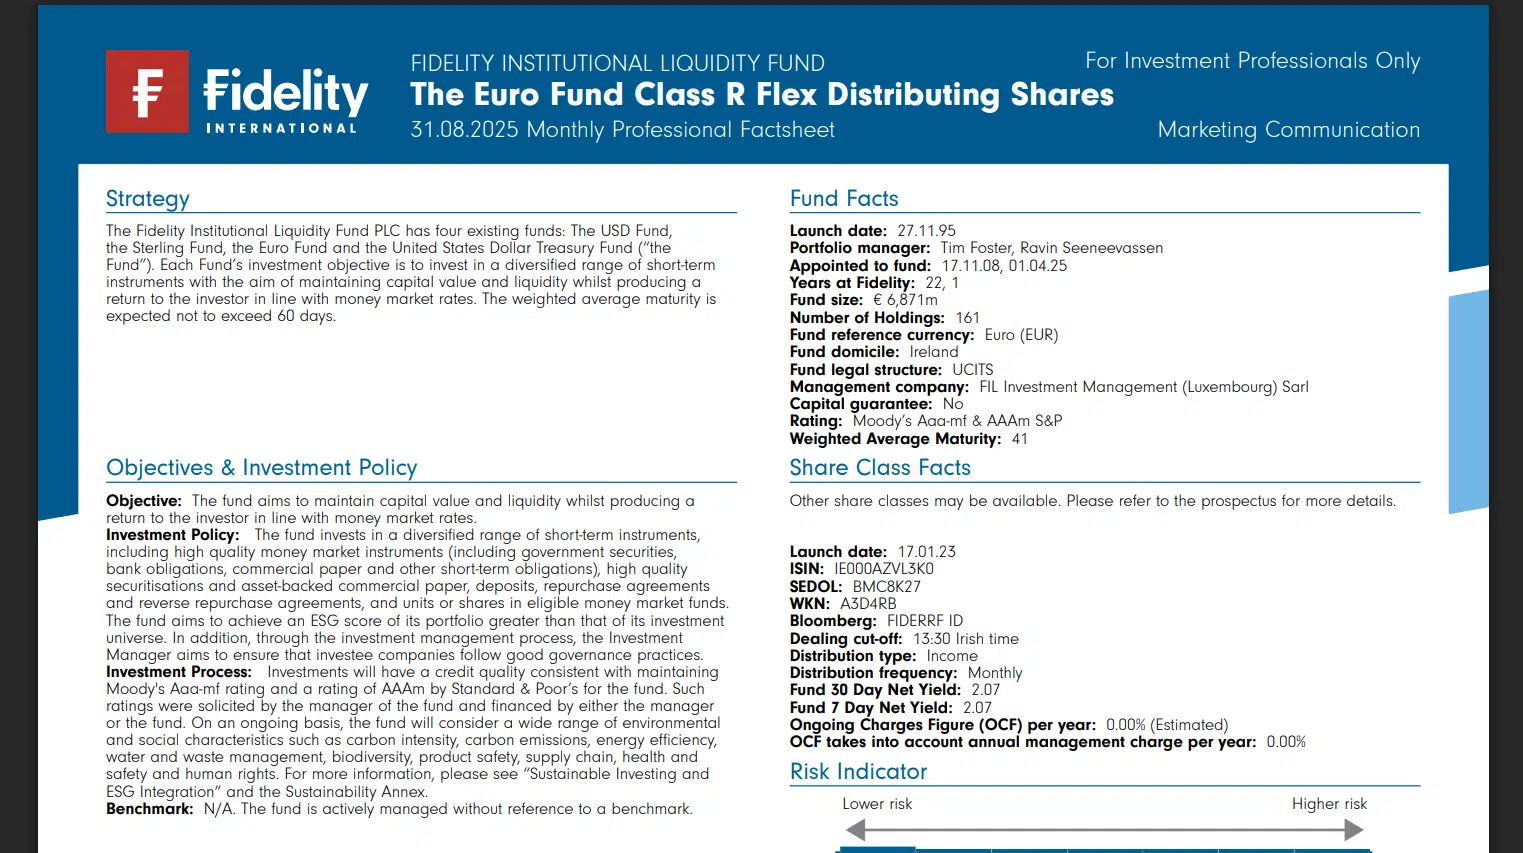
The fund itself yields more than what Revolut passes on to you. The difference between the fund’s yield and the rate you receive is effectively Revolut’s fee, and it’s larger on the free plan than on the paid ones. Revolut doesn’t present it as a fee, which is why it’s worth comparing the fund’s yield with the rate shown in your app.
How much does Revolut keep?
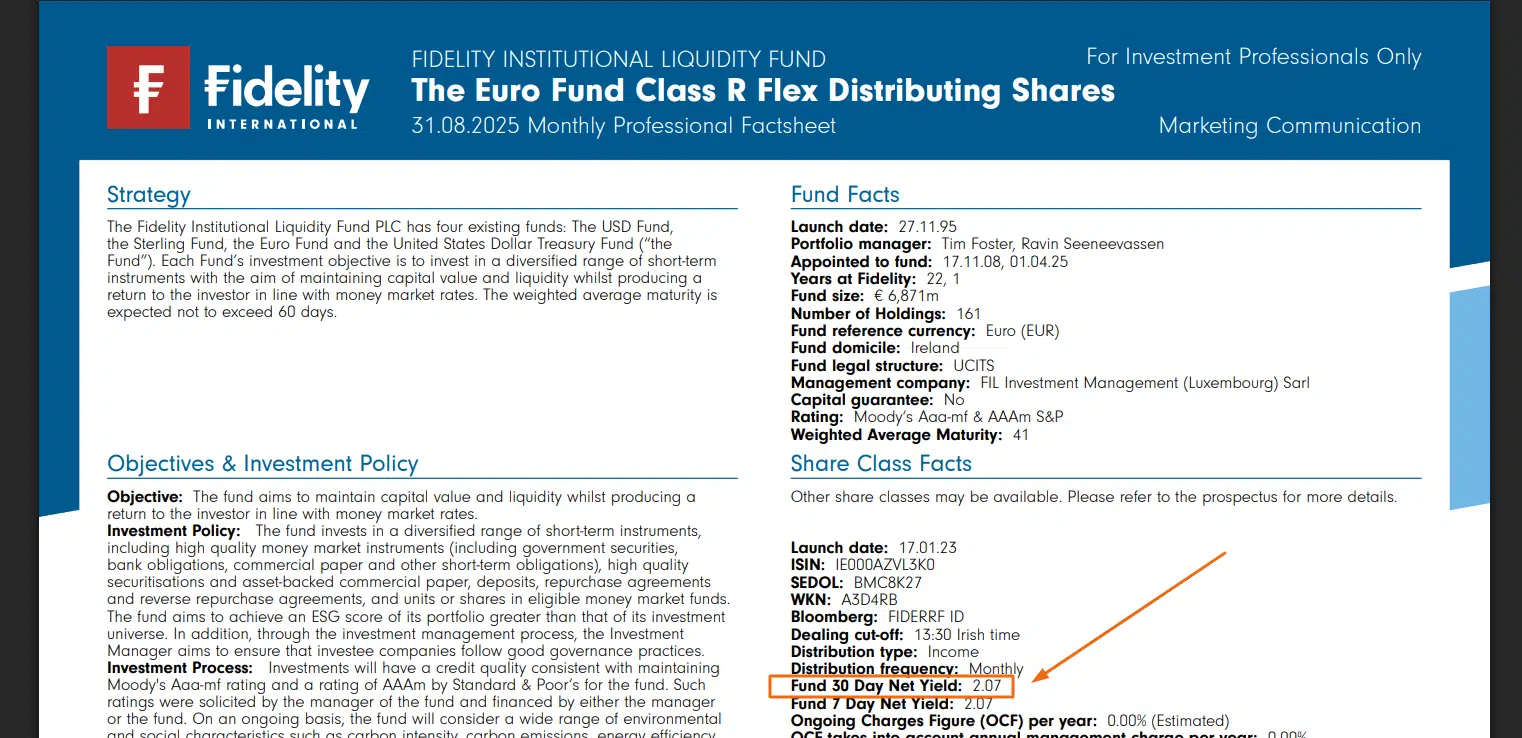
This is the part nobody puts in a table, so we did. The fund’s own factsheet dated 31 August 2026 reports a 7-day yield of 2.4% and an ongoing charge of 0.00% on this share class, which means essentially all of the gap between the fund and your app is Revolut’s margin. Compare that with the EUR rates Revolut published on 12 May 2026:
| Plan | Your EUR rate | Gap versus the fund | Share of the yield kept |
| Standard | 1.25% | 1.15 p.p. | 48% |
| Plus | 1.4% | 1 p.p. | 42% |
| Premium | 1.85% | 0.55 p.p. | 23% |
| Metal | 2% | 0.4 p.p. | 17% |
| Ultra | 2.1% | 0.3 p.p. | 12% |
Fund 7-day yield of 2.4% from the Fidelity factsheet dated 31 August 2026, against Revolut’s published EUR APYs dated 12 May 2026. The two dates differ, so read this as the shape of the pricing rather than today’s exact spread. Calculations by us.
The pattern is what matters, and it is consistent: the free plan gives up roughly half of what the fund earns, while the most expensive plan gives up a small slice. Revolut is not doing anything hidden here, the fund factsheet is public and so are the app rates, but you do have to put the two numbers next to each other yourself to see the price of the service.
Does a paid plan actually pay for itself?
To get Revolut’s highest rate, you need the Ultra plan, which is the most expensive one. Before paying for a plan just for the rate, do the maths: the extra return only covers the monthly fee if your balance is large enough. Using the Portuguese plan prices and the published EUR rates, here is the balance each plan needs before it breaks even against the free Standard plan:
| Plan | Price | Annual cost | Extra EUR yield | Balance needed to break even |
| Plus | 3.99€/month | 47.88€/year | +0.15 p.p. | 31,920€ |
| Premium | 9.99€/month | 119.88€/year | +0.6 p.p. | 19,980€ |
| Metal | 17.99€/month | 215.88€/year | +0.75 p.p. | 28,780€ |
| Ultra | 55€/month | 660€/year | +0.85 p.p. | 77,650€ |
Break-even balance calculated by us, dividing each plan’s annual price by the extra EUR yield it delivers over the free Standard plan. Plan prices are the Portuguese ones and vary by country. Gross of tax, and it ignores every other benefit the plans include.
Two things jump out. Premium has the lowest break-even of the paid plans, at about €19,980, because its rate jump is large relative to its price. And Ultra needs roughly €77,650 in the fund before the rate alone justifies it, which is far more cash than most people keep idle.
Read those numbers as a floor, not a recommendation. They compare the rate benefit only. If you already value the travel insurance, the FX allowances or the other plan perks, the plan may be worth it at a much smaller balance. But if the rate is your only reason to upgrade, and your balance is below these thresholds, upgrading costs you money.
Flexible Cash Funds or Instant Access Savings?
If you open the Savings section today you may be offered both products. They are not variations of the same thing:
| Flexible Cash Funds | Instant Access Savings | |
| What it is | Units in a money market fund | A deposit with Revolut Bank UAB |
| Who manages the money | Fidelity | Revolut Bank UAB |
| Protection | Lithuanian investor insurance, up to €22,000 | Deposit guarantee, up to €100,000 |
| What the protection covers | Assets that cannot be returned to you, not investment losses | The deposit itself if the bank fails |
| Can the value fall? | Yes, in principle, though it is rare for this type of fund | No |
| Rate quoted as | APY, variable, changes daily | A stated rate per plan, variable |
| Currencies | EUR, GBP, USD | EUR in the eurozone markets |
| Rate ceiling | Higher, especially in GBP and USD | Usually lower, and often tiered by balance |
The two Revolut savings products compared, September 2026.
Which one suits you depends on what you are optimising for.
Instant Access Savings is the one that behaves like a savings account. It is a deposit, it carries the €100,000 guarantee, and the balance cannot fall. The trade-off is that the headline rate is generally lower and often tiered, so the good rate applies only up to a threshold and the balance above it earns much less. The tiers differ by country, which is why we are not quoting a single number here: check your own market’s page before assuming the advertised rate applies to your whole balance.
Flexible Cash Funds is the one that reaches higher rates, particularly in sterling and dollars, where there is no comparable Revolut deposit product. You are accepting fund risk and a €22,000 protection limit in exchange.
One country-specific note worth knowing: in Germany, Revolut’s terms state that for Instant Access Savings accounts opened from 4 August 2026 the money sits with Deutsche Bank rather than under the Lithuanian deposit guarantee, and that you ultimately carry the risk if Deutsche Bank were to fail. If you are in Germany, read your own terms rather than assuming the standard arrangement.
Is it safe?
As we said, with Flexible Cash Funds your money goes into low-risk short-term debt. These are the holdings of the Fidelity fund:
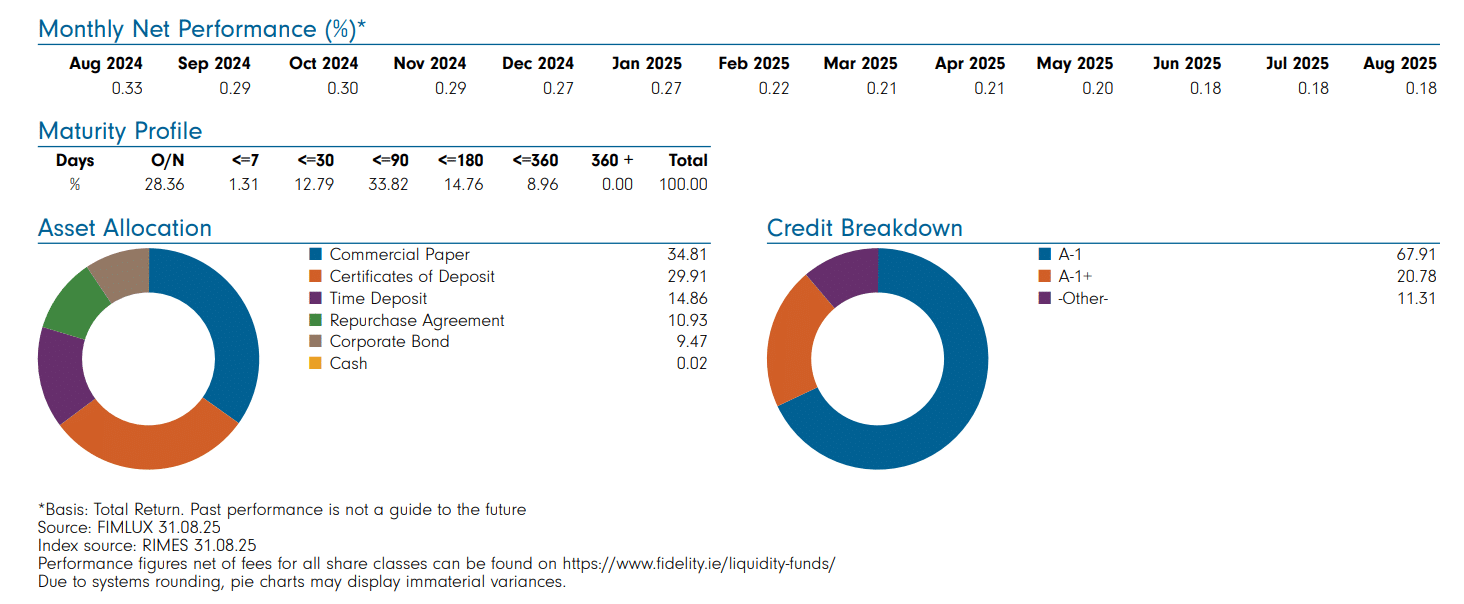
The credit quality is good and the fund runs a weighted average maturity of about 42 days, which keeps the interest rate risk low. Even so, a money market fund is an investment, not a deposit: its value can fall, although that is rare for this type of fund.
If something were to happen to Revolut, an insolvency for example, the money in Flexible Cash Funds is covered by the Lithuanian investor insurance scheme, up to €22,000 per investor. The scheme is run by the Lithuanian public institution “Deposit and Investment Insurance”, it pays out within three months in normal circumstances, and it protects you if your assets can’t be returned. It explicitly does not compensate you for a fall in the value of your investment.
The key point: this service is not covered by the European deposit guarantee scheme, which protects bank deposits up to €100,000. If protection matters more to you than reaching the highest rate, Revolut’s own Instant Access Savings, a bank account elsewhere, or a broker holding your cash in bank deposits will suit you better.
Note that Revolut is a bank in several markets, including the UK since March 2026 and Lithuania for the EEA, but Flexible Cash Funds is an investment product, not a deposit, wherever you are.
Pros and cons of Revolut Savings
Pros
-
Competitive returns compared with most traditional bank accounts, especially in GBP and USD
-
The return compounds, since it stays invested in the fund
-
Easy to manage in the app, with instant deposits and withdrawals
-
No minimum or maximum balance
-
A deposit-based alternative, Instant Access Savings, now sits alongside it with the €100,000 guarantee
- Well integrated with the rest of Revolut, including budgeting and investing
Cons
-
Not a deposit: it is an investment in a money market fund, with no deposit guarantee
-
Protection limited to €22,000 under the Lithuanian investor scheme
-
The best rates require a paid plan, and the break-even balance is high
-
Revolut keeps a large share of the fund's yield, around half of it on the free plan, and doesn't present it as a fee
-
Rates are variable, change daily, and lag central bank moves by several weeks
-
Revolut's published rate table is updated infrequently, so the app is the only reliable source
- Not available in every country
How can I activate this service?
In the Revolut app, on the “Home” tab, scroll down until you find “Savings”:

You will then see the rates for your plan. Ours is Standard, so these are the rates shown:
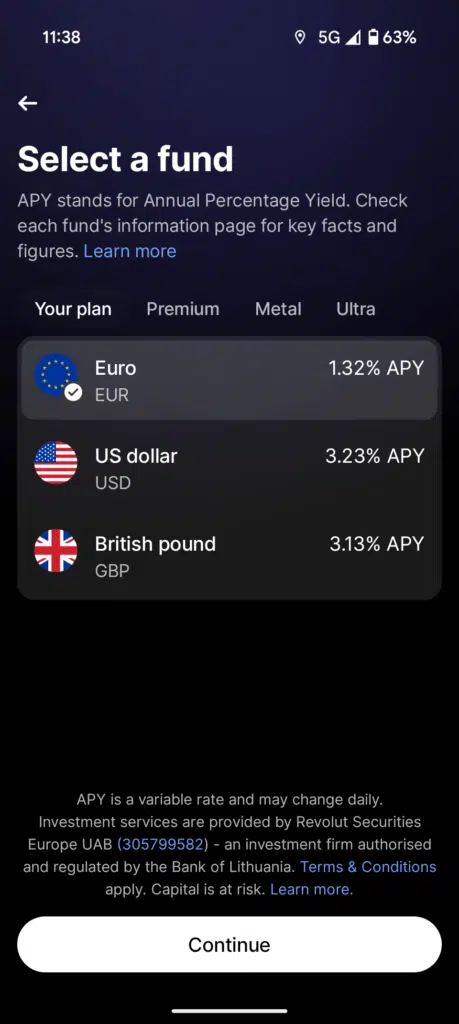
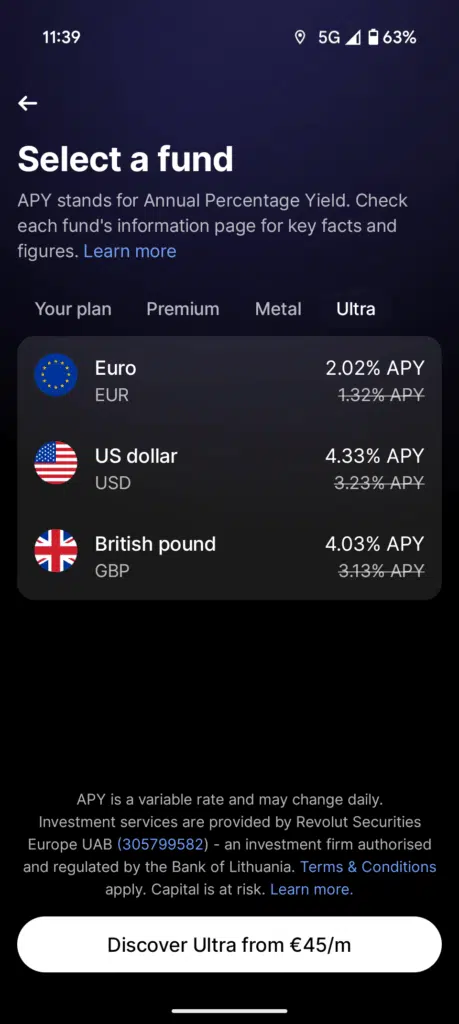
If you scroll right through the plans, up to “Ultra”, you’ll see the highest rates for each currency:
We went ahead with the Standard plan and, after tapping “continue”, we were shown the details of the money market fund we were about to invest in:
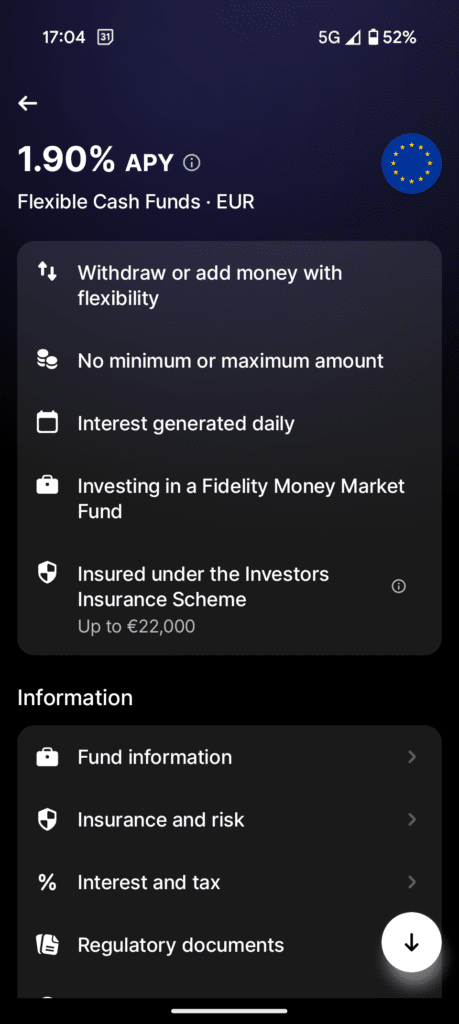
Once everything is set up, you get the “Flexible Cash Funds” page:
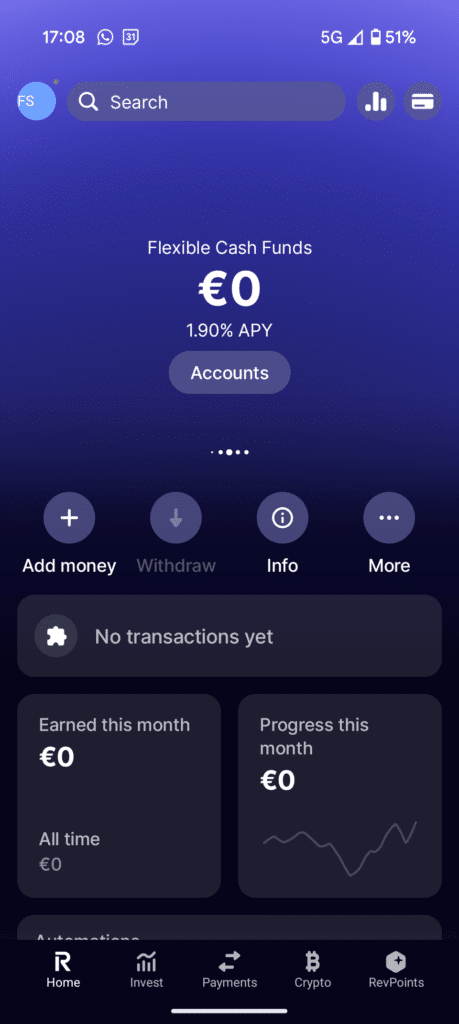
We set this account up in euros. If you want the same in pounds or dollars, follow the same process and choose the other currency instead.
The screenshots above show the rates at the time we opened the account. Since the APY changes daily, treat the figure on your own screen as the current one and the tables in this article as the shape of the pricing.
Revolut Savings alternatives
If you’re looking for alternatives to Revolut Savings, check our articles on the best brokers and digital banks paying interest on cash in EUR, USD and GBP, as well as our comparison of the best savings accounts in Europe.
Some of those options hold your cash in bank deposits, which come with the €100,000 guarantee, rather than in money market funds. Worth checking before you decide: several European brokers now pay a rate on uninvested euro cash that sits close to the ECB deposit facility rate of 2.50%, which is above what the free Revolut plan passes on from the fund. If you’re also interested in other products on Revolut, take a look at our review of Revolut’s ETFs.
Bottom line
Revolut Savings is a convenient way to earn a return on money you’d otherwise leave idle in the app, with no minimum, instant access and a simple setup.
The trade-offs are worth understanding: Flexible Cash Funds is a money market fund rather than a deposit, the protection is €22,000 rather than €100,000, the best rates require a paid plan whose break-even balance runs from about €19,980 on Premium to about €77,650 on Ultra, and Revolut keeps a large share of the fund’s yield, roughly half of it on the free plan.
The most useful change since we first wrote this guide is that you no longer have to accept those trade-offs to save inside Revolut. Instant Access Savings is a genuine deposit with the €100,000 guarantee, so if the protection gap was your objection, that objection now has an answer inside the same app, at a lower rate and usually with balance tiers.
If convenience is what you value, the fund does the job well. If you want the highest return on your cash, or the strongest protection, compare it with the alternatives above before moving your money.
Disclaimer: When investing, your capital is at risk and you may get back less than invested. Money market funds are investments, not deposits, and are not covered by deposit guarantee schemes. Rates are variable and change daily. This article is for information only.