


This is our review of Untapped Global, an impact investing platform that finances businesses in frontier and emerging markets.
Untapped Global currently offers fixed income notes with terms of 12 to 36 months and a fixed annual yield of 6% to 14%, according to its investor page. On the downside, the platform is not supervised by a financial regulator in the way a broker is, so you carry the full credit risk of Untapped and of the businesses it finances.
Overview
In a nutshell, Untapped Global finances revenue-generating assets, such as electric motorbikes, solar equipment or water systems, that tech-enabled companies in emerging markets put to work. Investors are repaid from a share of the revenue those assets produce.
Untapped Global is based in San Francisco (US). Its investment platform has been active since 2021, the starting point of the impact figures it publishes.
The founders’ background is in a water distribution venture in Haiti that depended on donations, which made funding unreliable and growth hard to plan. Bank loans were not an option either, because small businesses in these markets rarely have collateral or a track record of cash flows.
The company built a platform that connects these businesses with global investors. Each financed asset is tracked with IoT (Internet of Things) devices, so Untapped can follow its usage and revenue in real time.
Their business model is based on revenue sharing. Untapped takes a percentage of the revenues that the financed assets generate and uses this money to pay back investors.
According to its website, from 2021 to the end of January 2025 Untapped financed more than 55,000 assets, supported 578,231 entrepreneurs and helped generate $46.5 million in revenue for them, or $3.83 of revenue for each $1 invested. These are company figures and have not been independently audited.
Pros and cons
Pros
- Access to fast-growing emerging markets
- Impact investment with published impact data
- Fixed annual yields of 6% to 14% on its notes
- Asset usage and revenue tracked in real time
- Returns not directly tied to US stock market performance
Cons
- Not supervised by a financial regulator and no investor compensation scheme
- No secondary market: your money is locked until the note matures
- High credit risk: the businesses financed or Untapped itself could fail to repay
- Default rates are not published
How does it work?
Untapped currently offers two products, according to its investor page:
- Fixed income notes: terms of 12 to 36 months with a fixed annual yield of 6% to 14%, and the option to receive interest every quarter.
- Digital Financial Inclusion Fund: a five-year fund with a variable yield that targets returns in the mid to high teens. That target is not guaranteed.
When a note matures, you can withdraw your money or reinvest it. Untapped uses the capital to finance assets for its partner companies and is repaid from a share of the revenue those assets generate. In some cases the financing works as a “lease to own” arrangement, so the entrepreneur ends up owning the asset.
You do not take an equity stake in the businesses. That sets Untapped apart from equity crowdfunding, where investors buy shares in a company.
Example: $10,000 in a 24-month note at a fixed 10% a year would pay about $2,000 in interest over the term (before tax), if Untapped repays in full. If it does not, you could lose part or all of the $10,000.
Platform
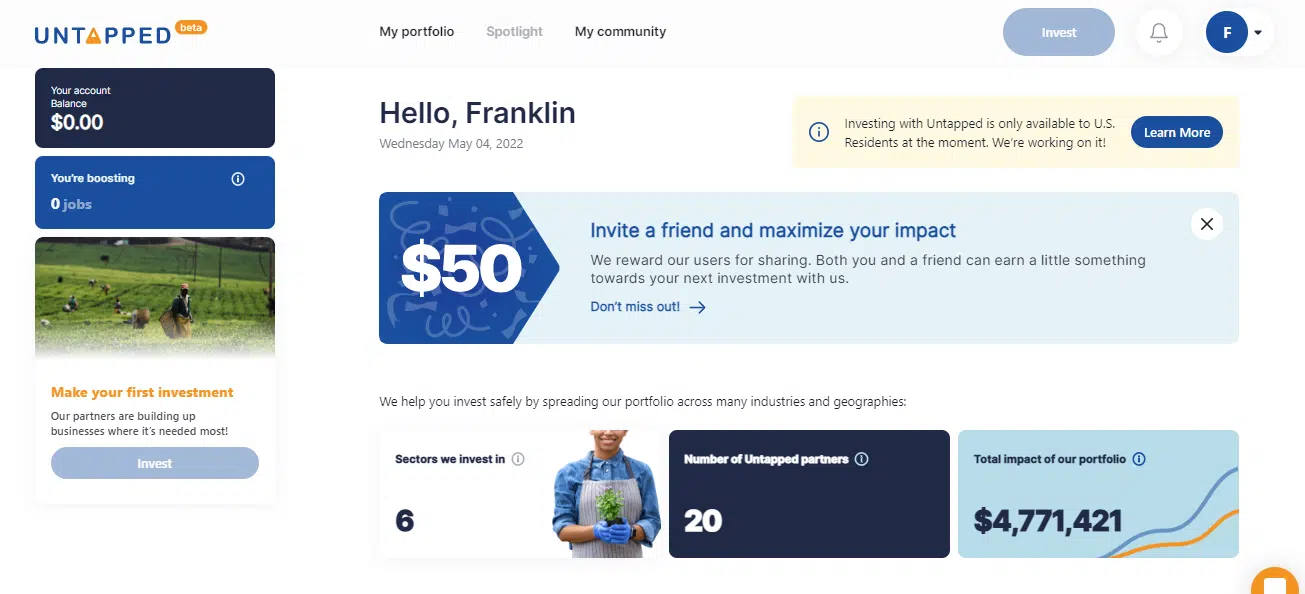
Untapped’s online platform gives you access to the information about your investments. The dashboard shows your balance, the impact of each business and the breakdown of the Untapped portfolio.
In the portfolio tab, you can follow the usage and revenue of the assets used by local entrepreneurs in real time. The screenshots below are from an earlier version of the platform.
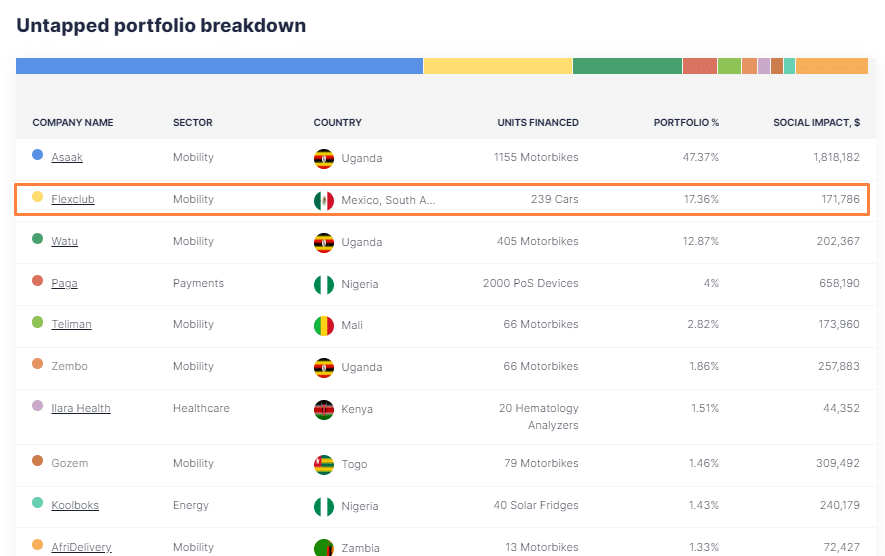
The Untapped portfolio is split between different companies, in different countries and sectors:
What is the default rate?
Untapped does not publish a default rate on its website. Its investor page only states that all major investments have exceeded the minimum internal rate of return (IRR) needed to repay investors, without giving the figures.
During its 2022 Wefunder campaign, the company reported an IRR of 24% on its portfolio. These are company-reported numbers that have not been independently verified, so treat them with caution and ask Untapped for its latest repayment and loss data before investing.
Fees
Untapped does not list investor fees on its website. Its revenue comes mainly from the spread: the difference between what the financed assets pay Untapped and the fixed rate it pays you.
For example, if your note pays 8% a year and the assets it finances return 12% (return on investment, or ROI), Untapped keeps the 4% difference.
This model aligns Untapped with the performance of the assets, but it also means your return is fixed while the risk is not: if the assets underperform badly, Untapped may not be able to pay the promised rate.
Safety and reliability
Untapped Global is not a broker or a bank, and no financial regulator supervises its lending in the way the SEC (Securities and Exchange Commission) or FINRA (Financial Industry Regulatory Authority) supervise a broker. Investor protection schemes such as the SIPC (Securities Investor Protection Corporation) in the US or the FSCS (Financial Services Compensation Scheme) in the UK do not apply.
Its notes are offered under US private placement or crowdfunding exemptions. For example, its 2022 Wefunder raise used Regulation Crowdfunding. These exemptions require some disclosure, but they do not mean the SEC has reviewed or approved the investment.
In essence, you are relying on Untapped and its partner companies to repay you. Only invest money you can afford to lose and keep it to a small part of your portfolio.
Supported countries
Untapped’s website does not publish who can invest. The platform has mainly targeted US accredited investors, meaning people who meet the SEC’s income or net worth thresholds, such as an income above $200,000 a year or a net worth above $1 million excluding their main home.
Investors outside the US have been able to invest through a manual process that includes KYC (Know Your Customer) checks and a wire transfer. To find out whether you can invest today, contact Untapped through the “Get in touch” form on its website.
Bottom line
Untapped Global offers a way to finance real businesses in emerging markets, with fixed yields of 6% to 14% and detailed impact data. The trade-off is significant: there is no regulator or compensation scheme behind the notes, no secondary market and no published default rate. It suits investors who value impact and can afford to lock up and potentially lose the money, not anyone looking for a safe place for savings.
Is Untapped Global safe?
It is not regulated like a broker, and there is no compensation scheme. Your money depends on Untapped and the businesses it finances repaying you.
What returns does Untapped Global offer?
Its fixed income notes pay a fixed 6% to 14% a year over 12 to 36 months. Its Digital Financial Inclusion Fund targets variable returns in the mid to high teens over five years, with no guarantee.
Can I withdraw my money early?
There is no secondary market, so you should plan to keep your money invested until the note matures.
This review is for information only and is not investment advice. Investing in private notes involves a high risk of losing your capital.
