


Hello, fellow investor! This article is our honest review of the Trine platform.
It does so by collecting money from individuals and companies (lenders) through crowdfunding, and lending it to solar companies (borrowers) in emerging markets.
The company’s motto, “It’s easy to invest in a greener future”, sums up the idea. By tapping the largely unused solar potential of developing countries, Trine aims to make a profit for itself and for its investors while having a positive impact on communities and the climate.
Registration is straightforward, and after that you pick the loans you want to fund. The barrier to entry is low, with a minimum of €25 per loan, and your first investment is guaranteed up to €100.
Since December 2023 Trine also holds an EU crowdfunding licence, which brought a set of investor protections that did not exist when the platform launched. We cover them below.
The upsides are the chance to invest in an environmentally and socially useful way while earning a return. The downsides, which we go through in detail, are a loan selection process that is not beginner friendly, limited room for diversification and long waits between a project being funded and the first repayment.
If you want the detail, keep reading.
Overview
Trine was built to make money through solar energy investments while helping people and the planet at the same time. The company calls it a “triple return on investment”, which tells you the vision is not about profit alone.
Trine AB was founded in Gothenburg in 2015 and is majority owned by its cofounders and employees, with some outside funding. There is more on the ownership structure here.
That fits the growth of ESG (Environmental, Social and Governance) investing, and Trine has grown steadily since 2016 (see its progress page).
At the time of writing, investments through Trine have brought electricity to more than 3 million people and avoided over a million tonnes of CO2. More than €100 million has been invested across upwards of 250 loans, by a community of over 15,000 investors, and the platform is still actively originating deals: in January 2026 it committed €5 million to Miale Solar in Kenya.
Investing is simple. You register, get verified, and then fund the loans available on the platform by direct bank payment through Trustly or by bank transfer. Trine accepts individual investors aged 18 and over from the European Economic Area, as well as companies.
It is essential to understand that Trine is not covered by any state deposit guarantee. Your money is held in an account separate from the company’s own funds, and if Trine were to fail you could in theory pursue the outstanding repayments yourself. We come back to this below.
Pros and cons
Pros
- Simple registration process
- Intuitive and user-friendly platform
- An easy way to invest in solar energy with a low barrier to entry (€25)
- The possibility of investing in a socially and environmentally useful way
- Authorised crowdfunding service provider under EU Regulation 2020/1503, with the investor protections that come with it
- No default recorded in the platform’s own regulatory disclosure for 2024 and 2025
Cons
- Higher risk than traditional asset classes, with no capital protection
- No deposit guarantee scheme covering your money
- Long period between a project being fully funded and the first repayment
- Loan selection process that is not beginner friendly
- Few loans available on the platform at any one time
- Limited opportunities for diversification
- Borrowers are outside the EU, which makes recovery difficult if things go wrong
- Repayments may be a taxable event in your country of residence
Loan selection and investment process
Trine lends mainly into the commercial and industrial (C&I) segment: small and large businesses, governments, schools and nonprofits, among others.
Solar is used there as a cheaper supplement to grid electricity, which cuts costs for the borrower and provides clean energy. Trine has also moved into e-mobility, financing electric forklifts, and into longer-term power purchase agreements, the structure behind its 2026 deal with the Kenyan developer Miale Solar.
Trine runs its own assessment system to grade the risk of each borrower, from A+ to B-, looking at financial performance, governance, track record, management, operating environment and competition, among other factors. It does not list companies rated below B-.
When you look at an opportunity you can inspect the loan, its terms and Trine’s due diligence on the company, including the key opportunities and the key risks. There is more on the due diligence process here.
It is worth being blunt about a limitation: it is very difficult to research these borrowers beyond what Trine itself publishes. You are relying on the platform’s own assessment to a degree that would be unusual in listed markets.
Depending on the size of your portfolio you may also qualify for Trine Rewards, extra interest on top of the base rate. The general terms are here, and the specific terms appear on each loan.
Fees
- Trine charges you, the lender, nothing. Its fees are paid by the borrower;
- The borrower pays a one-off fee for arranging the loan and a management fee through the repayment period;
- The exact fees depend mostly on the size of the loan.
There is more on the fee structure here.
Note that “no fees” is not the same as “no costs”. Your return is the interest actually paid by the borrower, and a delayed or defaulted loan costs you far more than any platform fee would.
Platform
The Trine platform runs in the browser and works on desktop and mobile. There is no native app for Android or iOS.
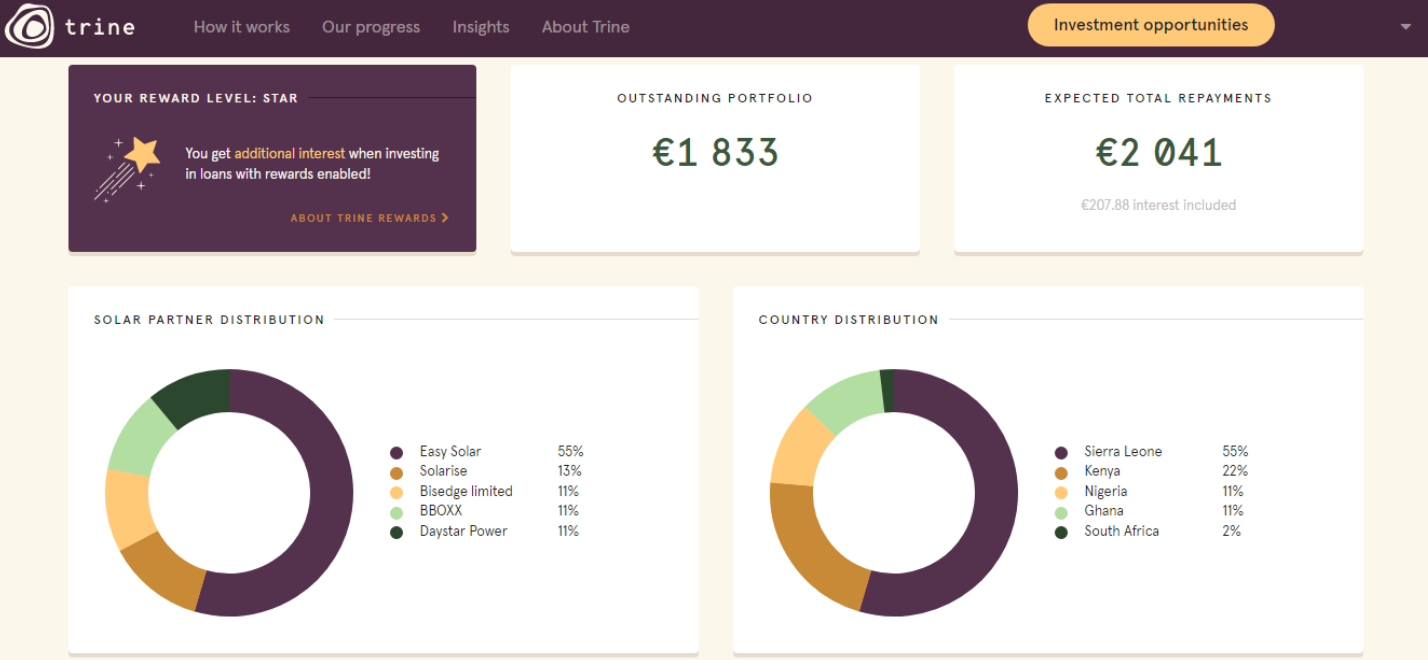
The interface is simple and intuitive. The dashboard shows the status of your investments, your portfolio, expected repayments, transactions and the impact figures behind them.
Regulation and investor protections
Trine AB (org. no. 559003-1463) is supervised by the Swedish Financial Supervisory Authority (Finansinspektionen) on two counts. It has been an authorised payment institution since 2019, and since December 2023 it is an authorised crowdfunding service provider under EU Regulation 2020/1503, the European Crowdfunding Service Providers Regulation. It appears in the ESMA register of authorised platforms, and the licence passports across the European Union.
That licence is the biggest change to this platform since our first review, and it brought concrete obligations:
- Key Investment Information Sheet (KIIS): every offer must come with a standardised document setting out the project, the terms, the risks and the costs, so you can compare offers across platforms rather than across marketing pages;
- Entry knowledge test: before investing, non-sophisticated investors have to answer questions about their experience and understanding of the products;
- Loss-bearing simulation: the platform has to show you a simulation of your ability to bear a loss, based on your finances;
- Warning above certain amounts: if you invest more than the greater of €1,000 or 5% of your net worth in a single offer, the platform must warn you and ask you to confirm;
- Four-day reflection period: non-sophisticated investors can withdraw an investment offer, with no penalty and no need to give a reason, within four calendar days;
- Standardised default-rate disclosure: platforms must publish their default rates using a common definition, which is what makes the numbers in the next section comparable with other platforms.
None of this makes the investment safe. It makes the risks disclosed and the platform supervised, which is a different thing.
Risks, safety and protection
The three major risks of investing with Trine are non-performing loans, the failure of Trine itself and currency exposure.
The mechanisms that offer some protection are the First Investment Guarantee and the investment protection arranged with SIDA and DFC. We go through each below.
Non-performing loans
Investing with Trine carries the risk of losing your capital. When repayments are late, a loan has to be restructured or it defaults. Trine manages debt recovery and the default process on behalf of investors, using measures that range from monitoring and contact with the borrower, through late fees, to restructuring, hiring a debt collector or filing for bankruptcy.
What the numbers say. Under the EU rules, Trine has to publish its default rate on a standard definition: a loan counts as defaulted when the borrower is more than 90 days late on significant obligations, or when Trine judges the borrower will not pay in full without action such as realising security. On that basis:
| Year | Active loans at the start of the year | Loans that defaulted during the year | Default rate |
| 2023 | 89 | 8 | 8.99% |
| 2024 | 108 | 0 | 0.00% |
| 2025 | 95 | 0 | 0.00% |
Source: Trine’s EU crowdfunding default rate disclosure, updated 29 January 2026.
Two readings of the same table. The good one is that no loan met the regulatory definition of default in 2024 or 2025, after a difficult 2023. The cautious one is that this definition is narrower than “everything went to plan”: a loan whose schedule is renegotiated under terms the contract already allows is not counted as a default, and delays are common in these markets. Trine uses its own loan statuses for day-to-day reporting, and those are the ones to watch in your dashboard.
There is more on the debt recovery process here.
If Trine itself fails
If Trine goes bankrupt, your money is not covered by a deposit guarantee scheme, unlike cash at a bank or, in a different way, assets at a regulated broker.
What you do have is segregation: the funds in your Trine wallet and the money arriving from repayments are kept separate from the company’s own finances, as required of a payment institution.
The loan note instrument is between you and the borrower, so in theory you could pursue repayment yourself if Trine disappeared. In practice that would be difficult, since the borrowers are outside the EU. The realistic outcome is that a third party would take over the administration of the outstanding loans, which is the arrangement crowdfunding platforms are expected to have in place under the EU rules.
Currency exposure
Trine lends into countries with different currencies, so there is currency risk on both sides.
The borrower usually earns in local currency but owes manufacturers and creditors in dollars or euros, which makes its business vulnerable to exchange rate moves. That is a credit risk for you, even though the loan itself is in euros.
As a lender, you take direct currency risk only if your own currency is not the euro, since the loans are issued in euros.
There is more on general risks here.
First investment guarantee
New investors get their first investment guaranteed up to €100. It covers a default by the borrower and only the principal, not the interest.
If your first investment is larger than €100, only €100 is protected, and the guarantee cannot be combined with others.
There is more on it here.
Investment protection with SIDA or DFC
Some loans come with protection arranged with the U.S. International Development Finance Corporation (DFC) or the Swedish International Development Cooperation Agency (SIDA).
Both cover a borrower default on the loan: DFC covers 50% of outstanding losses of principal and SIDA covers 60%.
The protection is loan by loan, not account-wide, so check the information on each offer to see whether it is covered and by which institution. In practice this is one of the few levers you have to reduce risk on the platform, alongside spreading your money across more loans.
There is more on Trine’s investment protection here.
Supported countries
Trine is open to investors aged 18 and over across the European Economic Area, plus Switzerland. UK investors who were already using the platform can continue, but Trine has not accepted new UK investors since January 2021.
The list: Austria, Belgium, Bulgaria, Croatia, Republic of Cyprus, Czech Republic, Denmark, Estonia, Finland, France, Germany, Greece, Hungary, Iceland, Ireland, Italy, Latvia, Liechtenstein, Lithuania, Luxembourg, Malta, Netherlands, Norway, Poland, Portugal, Romania, Slovakia, Slovenia, Spain, Sweden and Switzerland.
The platform is only available in English.
Bottom line
Trine offers a simple way to lend to solar companies in emerging markets, with the possibility of a return alongside a measurable impact on communities and emissions. That combination is its biggest selling point, and the dashboard makes the non-financial side of it visible in a way few platforms manage.
The interface is simple, but picking the right loan and building any real diversification is harder than it looks, particularly because there are rarely many offers open at once.
The regulatory picture has improved since our first review. Trine is now an authorised crowdfunding service provider under the EU rules, which brought the information sheet, the knowledge test, the reflection period and, usefully for anyone comparing platforms, a standardised default rate. That disclosure shows 8.99% in 2023 and zero in 2024 and 2025.
None of that removes the risks: loans can be late or unpaid, Trine itself is not covered by a deposit guarantee, and recovering money from a borrower outside the EU would be difficult. Treat it as a high-risk, illiquid slice of a portfolio, size it accordingly, and use the loans that carry SIDA or DFC protection if the impact is what brought you here.
Thank you for reading.
