


This article will give you our honest review of the biggest robo-advisor in Spain: Indexa Capital.
The business model incentivises a long-term approach by using index funds in an automated and efficient way. On the downside, its website is only in Spanish and French, and the minimum deposit is relatively high for beginners.
The leading robo-advisor has over €6 billion in AUM and more than 170,000 clients as of September 2026, having roughly grown its assets by 63% over the past year. Beyond Spain it now also operates in Belgium and France. Over the years, it has received awards from reputable entities such as Rankia, Wealthtech 100, and Allfunds.
That’s Indexa Capital in a nutshell. If you want to find out what our research team has to say after carefully analysing Indexa Capital, keep reading.
Overview
Founded in 2015, Indexa Capital was the first automated online investment manager in Spain. Through a passive investment approach, investors can obtain a diversified and transparent investment portfolio with low commissions compared to traditional wealth management services.
You will need at least €2,000 to open a fund portfolio. Pension plans start much lower, from €50, which makes them the more accessible entry point for anyone not ready to commit a lump sum.
The management fee is the only revenue stream of Indexa Capital and it is low, scaling down as your portfolio grows. From January 2026 the average total cost of its fund portfolios, including the underlying fund charges and custody, is 0.530% a year. Indexa states this is on average 81% below what banks and funds in Spain charge. There are no hidden costs: no rebalancing fees and no reporting fees.
From over 2,200 opinions, it sits at a strong score on TrustPilot. The comments highlight the platform, customer support and investment strategies.
Finally, the FAQ for Indexa Capital is well-organised and has helpful information. We even came across an important but uncomfortable topic: “What happens to my investments if I die?”.
Highlights
| 🗺️ Supported Countries | European Union (Except Cyprus, Gibraltar and Malta), United Kingdom and Switzerland. |
| 💰 Management fee | 0.15% to 0.41% (per year), depending on portfolio size |
| 💰 Average total cost | 0.530% (per year), including fund and custody charges |
| 🎮 Demo Account | No |
| 📈 Portfolio Rebalancing | Yes |
| 💵 Minimum Deposit | €2,000 for fund portfolios; from €50 for pension plans |
| 📍 Investment Instruments | Index Funds |
| 📜 Regulator | CNMV (registration number 257) |
Pros and cons
Pros
- Automatic rebalancing
- Low fee structure and transparency, reduced repeatedly since launch
- Access to institutional share classes of Vanguard index funds
- Index funds qualify for tax-free traspasos for Spanish residents
- Annual consolidated summary activity for tax purposes
- Tax Loss Harvesting
Cons
- A minimum deposit of €2,000 for fund portfolios, higher than most rivals
- The website is only in Spanish and French
- The portfolio management fee is calculated per account, not per client (in case you have multiple accounts)
- Only investment in Equity and Bonds. No cryptocurrencies, alternative investments, and/or Forex.
Why index funds rather than ETFs? The traspaso advantage
This is the part that explains Indexa’s whole design, and it is specific to Spanish residents.
Under Spanish tax law, you can transfer money between investment funds (a traspaso) without realising a capital gain. The tax is deferred until you finally take the money out. ETFs do not qualify for this treatment, so switching between ETFs, or rebalancing a portfolio of them, triggers a taxable event each time.
For a robo-advisor that rebalances your portfolio automatically, that difference is decisive. Indexa can shift your allocation back to target without generating a tax bill along the way, and you can move your entire portfolio to a different fund manager later without paying tax on the gains accumulated so far. An identical ETF portfolio would leak tax at every rebalance.
This is also why Indexa’s total cost of around 0.53% can beat a cheaper ETF portfolio in after-tax terms for a Spanish resident, even though ETF TERs are often lower. The comparison that matters is not the headline fee but the fee plus the tax drag.
If you are not a Spanish tax resident, this advantage does not apply to you, and the case for Indexa rests on the cost and convenience arguments alone.
Investment platform
The Indexa Capital platform is very straightforward and user-friendly. It does not have a modern look and feel, but it includes all the relevant tools for a robo-advisor. The menus are where you expect them to be, and there are no customisation options.
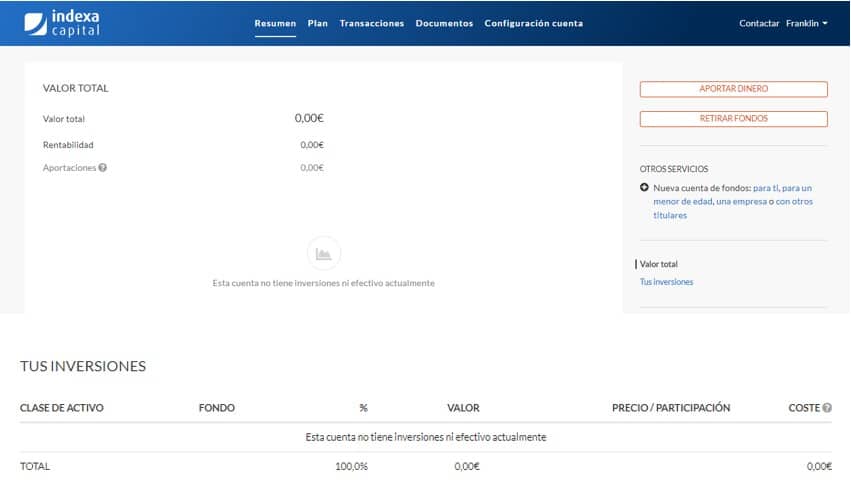
In “Resumen” (dashboard), you will immediately see a summary of your investment value at the top and a breakdown by asset class at the bottom.
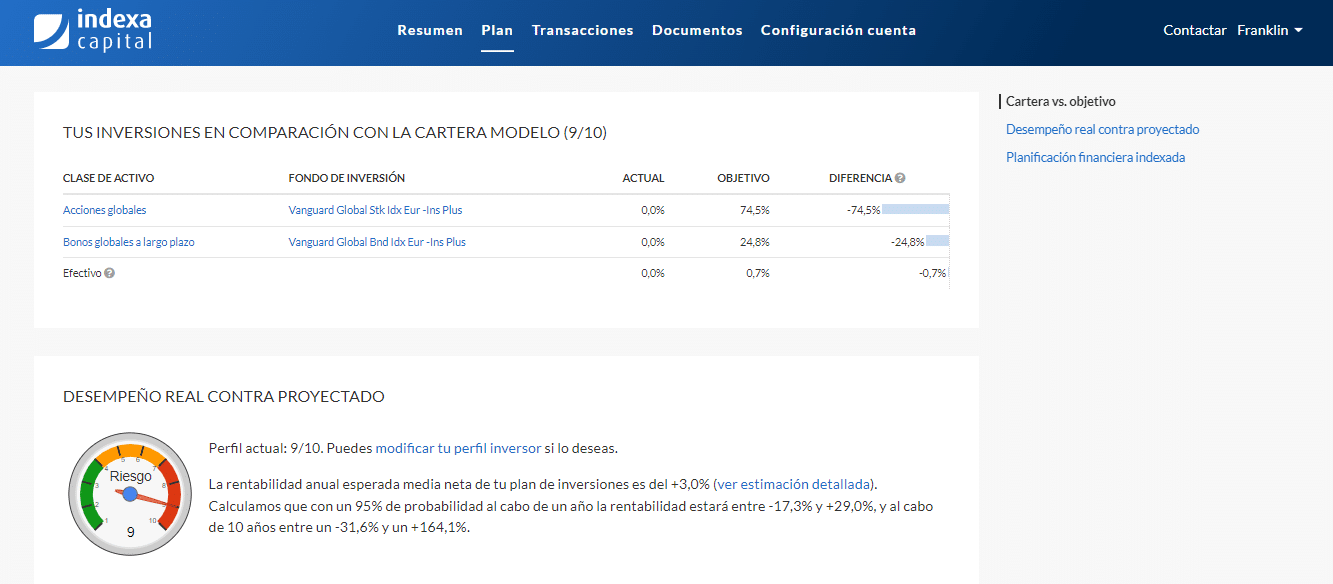
In the tab “Plan”, you can quickly revisit your target asset allocation, the instruments used and the expected returns:
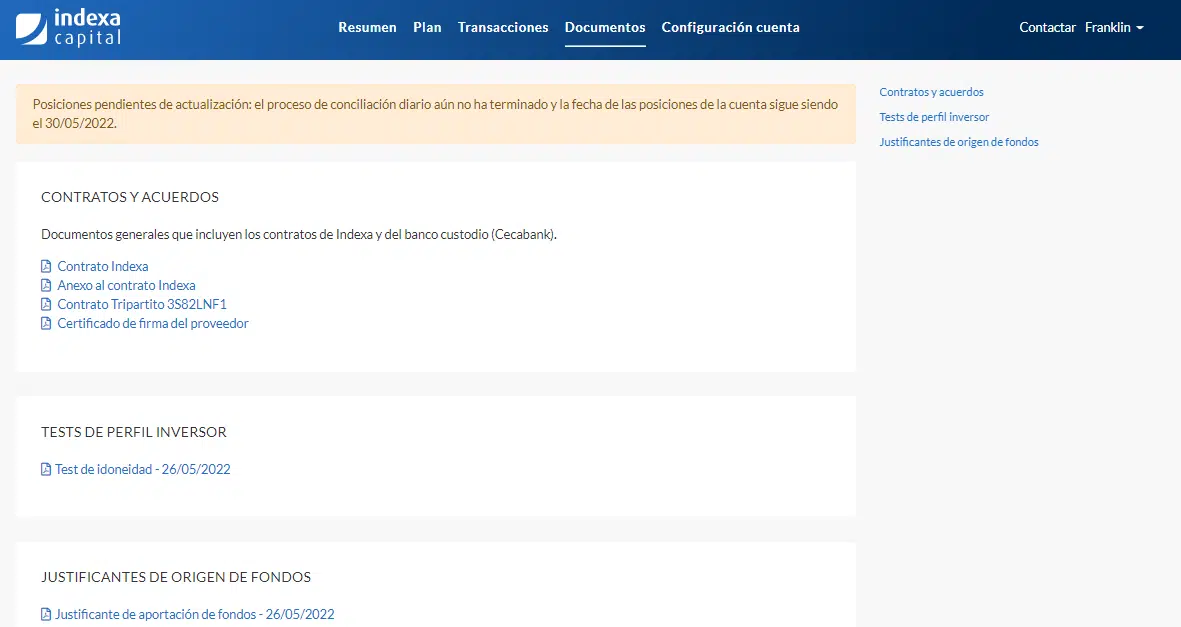
In the “Documentos” tab, you will find all the signed contracts plus the adequacy test used to arrive at your risk profile.
Investment strategy
Since Indexa Capital only uses index funds, its main job is to optimise asset class allocation, combining assets to achieve maximum return for a given level of risk. Once the asset classes are identified, they define the weights of each class for each investor profile.
Indexa Capital’s portfolio selection is based on Modern Portfolio Theory (Markowitz, 1952) and the Black-Litterman model.
The Markowitz model establishes a relationship between the expected return within each asset class and the risk that its inclusion brings to the portfolio. For a predetermined level of risk, it finds the highest expected return.
Black-Litterman improves on MPT by taking additional input from investors’ views to determine how the ultimate asset allocation should deviate from the initial portfolio weights.
Therefore, the ingredients to find the proper allocation for your needs are:
- Your investor profile
- The long-term expected return of each asset class
- The variance-covariance matrix of asset classes (risk)
The Indexa Capital Advisory Committee’s role is to analyse data from past market behaviour and include market expectations for the different asset classes. So there is a human element in the decision-making process.
The investment portfolios
The Indexa Capital offering depends on your country of residency and your investment amount, and there are socially responsible options alongside the standard range. All include the essential services: passive investing, automatic rebalancing, global diversification, low management costs and security.
The investment structures are different for Spanish and non-Spanish (international) investors.
Spanish Investors
As a retail Spanish resident, your options are “Cartera de fondos de inversión”, “Cartera de planes de pensiones” and “Cartera de planes de EPSV” (only for País Vasco).
- Cartera de fondos de inversión
You are offered a range of diversified portfolios for different investor profiles. The types available also depend on the amount invested, with more asset classes included as the portfolio grows.
- Cartera de planes de pensiones y EPSV
Pension plans start from €50 and give access to passive instruments in equity and bonds from providers such as Vanguard, iShares (BlackRock), State Street SPDR, Amundi, Xtrackers and Nomura. These are tax-efficient for Spanish investors, as explained here. Indexa Capital publishes the past performance of these strategies. Be aware that past performance is no guarantee of future returns.
The plans managed by Indexa Capital are Indexa Más Rentabilidad Acciones (N5138) and Indexa Más Rentabilidad Bonos (N5137). These can also be accessed through third parties such as Caser, Selfbank and MyInvestor.
Apart from the investment side, Indexa Capital also offers a life insurance policy that may help your family if something happens to you.
International Investors
As an investor outside Spain, you access portfolios using index funds in two asset classes: equity and bonds. This is the same structure as the “Cartera de fondos de inversión” described above.
The sub-asset classes used are the following:
- Equity: Europe, US, Emerging Markets, Pacific ex-Japan and small global capitalisation.
- Bonds: European Governments, European Corporate, Emerging Markets – EUR Hedged, European Inflation-Linked, US governments – EUR Hedged and US corporates – EUR Hedged.
These are the index funds that will be present in your portfolio:
| Name | ISIN | Tracking Index | Sub-Asset Class | TER |
| Vanguard European Stk Idx Eur -Ins Plus | IE00BFPM9L96 | MSCI Europe | European Equity | 0.08% |
| Vanguard US 500 Stk Idx Eur -Ins Plus | IE00BFPM9V94 | S&P500 | US Equity | 0.06% |
| Vanguard Japan Stk Idx Eur -Ins Plus | IE00BFPM9P35 | MSCI Japan | Japan Equity | 0.12% |
| Vanguard Emrg Mk Stk Idx Eur -Ins Plus | IE00BFPM9J74 | MSCI Emerging Markets | Emerging Markets Equity | 0.16% |
| Vanguard Pacific Ex-Japan Stk Idx Eur -Ins Plus | IE00BGCC5G60 | MSCI Pacific ex-Japan Index | Pacific Ex-Japan Equity | 0.12% |
| Vanguard Global Small Cap Idx Eur -Ins Plus | IE00BFRTDD83 | MSCI Small Caps | Small Global Capitalization Equity | 0.24% |
| Vanguard Euro Inv Gr Bnd Idx Eur -Ins Plus | IE00BFPM9X19 | Barclays Euro Non-Government Bond | European Corporate Bonds | 0.08% |
| iShares EM Gov Bnd Idx -I2 Eur Hdg | LU1373035663 | JP Morgan EMBI Global Diversified Index | Emerging Markets Bonds – EUR Hedged | 0.24% |
| Vanguard Eur Gov Bnd Idx -Ins Plus | IE00BFPM9W02 | Barclays GA Euro Government Bond | European Governments Bonds | 0.06% |
| Vanguard Euroz Inf Lk Bnd Idx Eur -Ins Plus | IE00BGCZ0719 | Barclays Eurozone – Euro CPI TR | European Inflation Linked Bonds | 0.06% |
| Vanguard US Gov Bnd Idx Eur Hdg -Ins Plus | IE00BF6T7R10 | Barclays US Government Float Bond Index | US Treasuries Bonds – EUR Hedged | 0.06% |
| Vanguard US Inv Gr Bnd Idx Eur Hdg -Ins Plus | IE00BZ04LQ92 | Barclays GA USD Credit Float Bond Index | US Corporate Bonds – EUR Hedged | 0.08% |
For Socially Responsible Investments (SRI), Indexa Capital offers the following index funds:
| Name | ISIN | Tracking Index | Sub-Asset Class | TER |
| Vanguard ESG Dev. World Stk Idx Eur-Ins Plus | IE00BFPM9S65 | FTSE All Cap Choice Index | Global Equity SRI | 0.13% |
| Vanguard ESG Emrg Mk Stk Idx Eur-Ins Plus | IE00BNDQ1L38 | FTSE Emerging All Cap Choice Index | Emerging Markets Equity SRI | 0.18% |
| iShares ESG Global Corp Bnd Idx Eur Hdg | IE00BJN4RG66 | BBGA Corporate Index | Global Corporate Bonds SRI | 0.16% |
| Amundi JPM Global Gov Bnd Idx Eur Hdg | LU0389812693 | JPM Global Gov – EUR Hedged | Global Government Bonds | 0.20% |
As the TER column shows, the costs of SRI index funds are higher than those of the standard index funds. Unless you believe these instruments will achieve superior returns, these additional expenses will reduce your portfolio performance. The trade-off is a values question rather than a purely financial one.
Indexa Capital does not allow you to hold two separate accounts in SRI and non-SRI investments in order to reduce your overall management fee.
Fees
Indexa Capital only charges management fees, and the rate varies according to the amount invested. Custody and index fund fees are external costs, unrelated to Indexa Capital, so it is in their interest to keep them low.
| Portfolio amount | Management fee | Custody fee | Index Funds fees | Total Costs |
| <€10,000 | 0.41% | 0.12% | 0.08% | 0.61% |
| €10,000 – €100,000 | 0.39% | 0.12% | 0.08% | 0.59% |
| €100,000 – €500,000 | 0.36% | 0.12% | 0.08% | 0.56% |
| €500,000 – €1,000,000 | 0.30% | 0.12% | 0.08% | 0.50% |
| €1,000,000 – €5,000,000 | 0.25% | 0.06% | 0.08% | 0.39% |
| >€5,000,000 | 0.15% | 0.06% | 0.08% | 0.29% |
Across all client portfolios, Indexa reports an average total cost of 0.530% a year from January 2026. Its pension plans carry a management fee of 0.355% plus 0.048% custody, giving 0.403% in total for 2026.
The portfolio management fee is calculated per account, not per client, so the balances of several accounts held by the same client are not consolidated. It is calculated on the daily value of the portfolio and charged quarterly to the client’s cash account at the custodian bank.
Economies of scale have allowed Indexa Capital to reduce management fees several times already, and it has done so every year since launch. The more clients they gain, the lower the expected commissions.
How Indexa compares to its Spanish rivals
Indexa is the largest independent robo-advisor in Spain, but not the only credible option, and it is not the cheapest entry point.
MyInvestor has a far lower minimum, which makes it more accessible if you are starting with a small amount, and many investors hold a MyInvestor portfolio alongside its remunerated account. inbestMe offers a broader range of socially responsible portfolios, which is the clearest gap in Indexa’s line-up. Finizens manages a smaller book and leans on themed portfolio options.
Where Indexa wins is scale and track record: ten years of operation, the largest asset base, access to institutional share classes of Vanguard funds, and a documented history of cutting fees as it grows. Where it loses is the entry point. If you have less than €2,000 to commit, the fund portfolios are simply closed to you, though the pension plans are not.
Safety and Reliability
Indexa Capital is regulated by the Comisión Nacional del Mercado de Valores (CNMV), the Spanish securities regulator, with registration number 257.
There are a set of ringfences to protect you in the unfortunate event of Indexa Capital going bankrupt, or any other institution that works with them.
First, you choose between two Spanish custodian banks: Inversis and Cecabank. Both have good solvency ratios, above 25%. The account at either entity is in your name, so you are not exposed to problems at those banks. If either ceased to operate, you would only need to transfer your assets to another custodian.
Indexa Capital sets a structure that we consider safe. Still, there are risks you cannot control, such as fraud, and regulators want to make sure you are protected in severe circumstances. As such, additional layers apply:
- When you open an account at Indexa Capital, they automatically open a bank account to hold your cash. That account is protected up to €100,000 per client by the Spanish Guarantee Fund. In practice, less than 1% of your money is expected to sit in cash, since the rest is invested.
- Regarding your investment portfolio, you are protected up to €100,000 per client by the Spanish Investor Protection Scheme (FOGAIN).
These protections apply to any client, Spanish or not, and work separately. Note that FOGAIN covers the failure of the investment firm, not investment losses: if your portfolio falls in value, no scheme compensates you for that.
Customer Support
Customer support is good. You can contact them quickly through the chat box in the bottom right corner of the homepage. We have spoken with an assistant called Monica several times, and her answers have been relevant and precise.
You can also contact them at [email protected], with a reply typically within 48 hours, and by phone on (+34) 900 431 282, a free number from Spanish networks.
Account opening
As soon as you click the sign-up button, these are the steps to complete your registration:
- Choose the type of investment. As a non-Spanish investor, you must choose the fund portfolio: long-term investment, but liquid and redeemable at any time. As a Spanish investor, you have more options available.
- Answer a questionnaire to establish your risk tolerance and investment objectives, including choosing the custodian bank where your assets will be held: Inversis Banco (Spanish residents) or Cecabank (international investors).
- Get your recommended plan. You receive a recommended investment plan with details of the portfolio’s composition, expected returns and cost analysis.
- Open an account and fill in your personal details.
- Make your deposit, at least €2,000 for a fund portfolio, and the funds will be automatically invested according to your investor profile.
Companies in Spain can also create an account and a pension plan for their employees. More information here.
Supported countries
Indexa Capital accepts residents of the European Union (except Cyprus, Gibraltar, and Malta), the United Kingdom, and Switzerland. Beyond Spain, it has an established presence in Belgium and France.
Bottom line
Indexa Capital is a major player in the robo-advisor space, and the numbers back that up: assets have grown from €1 billion in 2021 to over €6 billion in 2026, with more than 170,000 clients. It suits buy-and-hold investors who want the long-term growth of their savings without the work of choosing and monitoring investments themselves.
Indexa will likely continue to benefit from economies of scale, allowing it to keep cutting fees as it has done every year since launch. Automatic rebalancing and tax loss harvesting make for a low-maintenance investment journey, and for Spanish residents the tax deferral available through index funds is a genuine structural advantage over an ETF portfolio.
Not everything is a bed of roses. The website still lacks an English version, which limits its appeal to anyone who does not read Spanish or French, and we have given that feedback directly to them. A €2,000 minimum for the fund portfolios is also higher than most Spanish rivals, though the pension plans start from €50 and are a way in for smaller amounts.
All in all, customers seem satisfied with the service, so it comes down to reassessing whether the pros outweigh the costs in your particular case.
FAQs
Why does Indexa use index funds instead of ETFs?
Because of Spanish tax rules. Transfers between investment funds (traspasos) do not trigger a capital gains tax event for Spanish residents, while switching between ETFs does. That lets Indexa rebalance your portfolio, and lets you move providers later, without generating a tax bill along the way. For a Spanish resident this often outweighs the slightly lower TERs available on ETFs.
Is Indexa Capital safe?
It is regulated by the CNMV under registration number 257, and your assets are held in your name at an independent custodian, Inversis or Cecabank, rather than on Indexa’s balance sheet. Cash is covered up to €100,000 by the Spanish deposit guarantee fund and investments up to €100,000 by FOGAIN. Those schemes cover firm failure, not market losses.
Can I use Indexa Capital if I do not live in Spain?
Yes. Indexa accepts residents of the European Union except Cyprus, Gibraltar and Malta, plus the United Kingdom and Switzerland, and has an established presence in Belgium and France. Note that the tax advantage of traspasos applies to Spanish residents only, so the case for Indexa rests on cost and convenience if you live elsewhere.
What is the minimum to start?
€2,000 for a fund portfolio. Pension plans start from €50, which is a considerably more accessible entry point if you are not ready to commit a lump sum. Confirm the current minimum on Indexa’s site before applying, as it has been reduced over time.
