


This review gives you our honest take on InvestEngine, a commission-free UK-based ETF investment platform with more than 100,000 customers.
InvestEngine lets users build either a Do-It-Yourself (DIY) ETF portfolio or an automated (managed) ETF portfolio, including the “LifePlans” range, matched to their risk profile, within a Stocks & Shares ISA, General Investment Account (GIA), SIPP (Self-Invested Personal Pension) or Business Account.
The platform focuses exclusively on exchange-traded funds (ETFs), with a selection of 870+ ETFs from major providers including iShares, Vanguard, Invesco, HSBC and Amundi. It doesn’t offer individual stocks, mutual funds or individual bonds, so it suits passive ETF investors rather than those looking for a multi-asset broker.
Overview
InvestEngine is a UK-based ETF platform that lets you build a portfolio using only ETFs. ETFs cover most major asset classes and sectors, providing broad diversification without the need to select individual stocks or bonds yourself.
With a minimum investment of £100, you get access to all of InvestEngine’s products. The platform also supports fractional investing, so you can invest as little as £1 in an ETF. Regular contributions start from £20 a week or £50 a month.
InvestEngine’s one-click rebalancing feature restores your ETF portfolio to its original target weights. For example, if you initially allocated 30% to ETF A and 70% to ETF B, and over time ETF A has outperformed and the allocation has shifted to, say, 35/65, a single tap returns the portfolio to the original 30/70 split. Smart orders let you set the investment amount and define each ETF’s target weight, while AutoInvest automatically deploys any new deposits across your selected ETFs in line with those weights.
InvestEngine is designed exclusively for UK investors and offers a Stocks & Shares ISA, General Investment Account, SIPP and Business Account for small and medium enterprises.
The fee structure is transparent: a 0.25% annual management fee applies to Managed Portfolios and LifePlans, while DIY portfolios have no InvestEngine management, dealing or platform fees. There are also no account fees on the SIPP or Business Account, and currency conversion is free. You only pay the underlying ETF costs (TER) and market spreads. This makes InvestEngine one of the cheapest options in the UK for self-directed ETF investors.
Finally, as detailed in the Safety section, InvestEngine is authorised and regulated by the Financial Conduct Authority (FCA) (FRN 801128), and eligible clients are protected by the Financial Services Compensation Scheme (FSCS) up to £85,000 if the platform fails.

Highlights
| 🗺️ Supported countries | United Kingdom (UK) |
| 💰 Fees | 0% on DIY portfolios, 0.25% a year on Managed Portfolios and LifePlans (ETF costs apply) |
| 🎮 Demo account | No |
| 📈 Fractional investing | Yes (from £1) |
| 💵 Minimum deposit | £100 |
| 📍 Investment instruments | ETFs only (870+ ETFs) |
| 🧾 Account types | Stocks & Shares ISA, General Investment Account, SIPP, Business Account |
| 🛡️ Regulation | FCA, FRN 801128 (FSCS protection up to £85,000) |
Pros and cons
Pros
- Simple and intuitive investment platform
- No ISA fees
- No deposit or withdrawal fees
- Fractional Investing
- One-click rebalancing
- Auto-invest
Cons
- Only offers ETFs: no bonds, shares, and other products
- No interest on cash balances (still you can invest in money market funds)
Investment products
InvestEngine offers ETFs only. There are currently more than 870 ETFs available on the platform. You can pre-select the range of ETFs you want to include in your portfolio using the following filters:
Asset class
Equities, bonds, or alternatives (mainly commodities such as gold and broad commodity baskets).
Income distribution
Distributing ETFs pay dividends directly to your account on a periodic basis (typically quarterly or semi-annually), while Accumulating ETFs automatically reinvest dividends within the fund, so the income compounds inside the ETF rather than reaching your cash balance. Accumulating ETFs are often preferred for tax-sheltered accounts like ISAs and SIPPs where you don’t need the income, since they remove the need to manually reinvest dividends.
Type of currency hedge
Currency-hedged to GBP: protects you from exchange rate movements when holding assets denominated in foreign currencies (e.g., USD or EUR), useful when you want pure exposure to the underlying asset without currency risk. Unhedged: leaves you exposed to currency fluctuations, which can either work in your favour or against you, depending on how GBP performs against the underlying currencies.
ESG
Filter for “Yes” or “No” to include or exclude ETFs that follow environmental, social, and governance (ESG) criteria. These ETFs screen the underlying companies based on a set of standards covering their impact on the environment, social responsibility, and corporate governance practices.
Investment portfolios
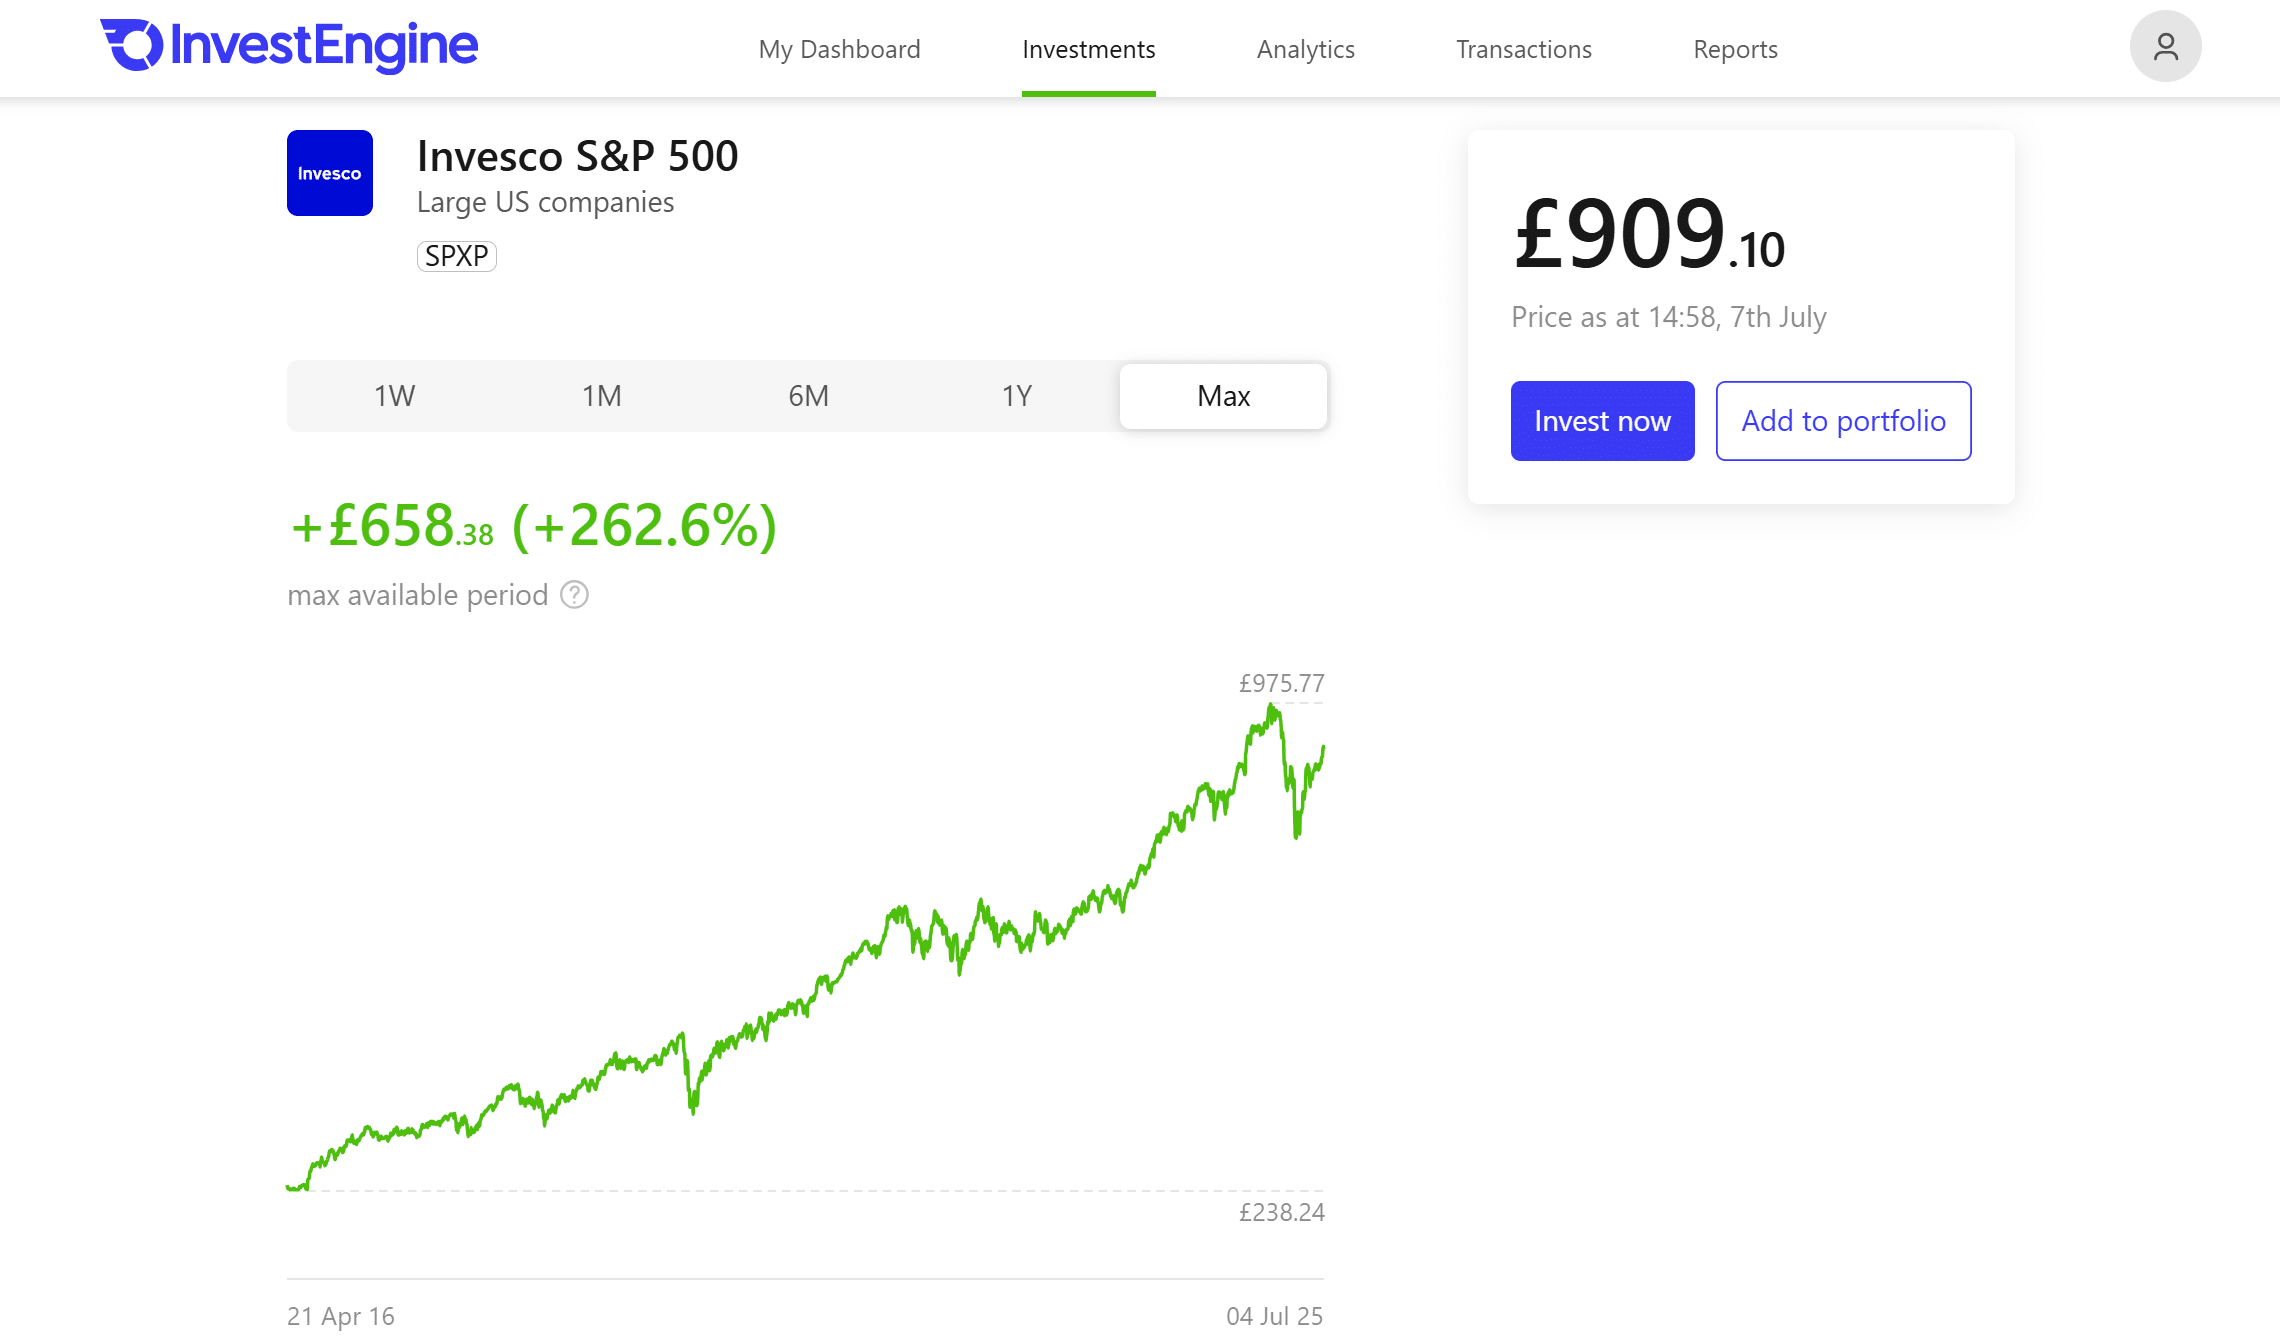
Through the “DIY” approach, you will be completely free to use the ETFs as you see fit. You can easily observe the composition of each ETF by asset classes, holdings, regions and sectors, giving you a better idea of how your portfolio might look afterwards.
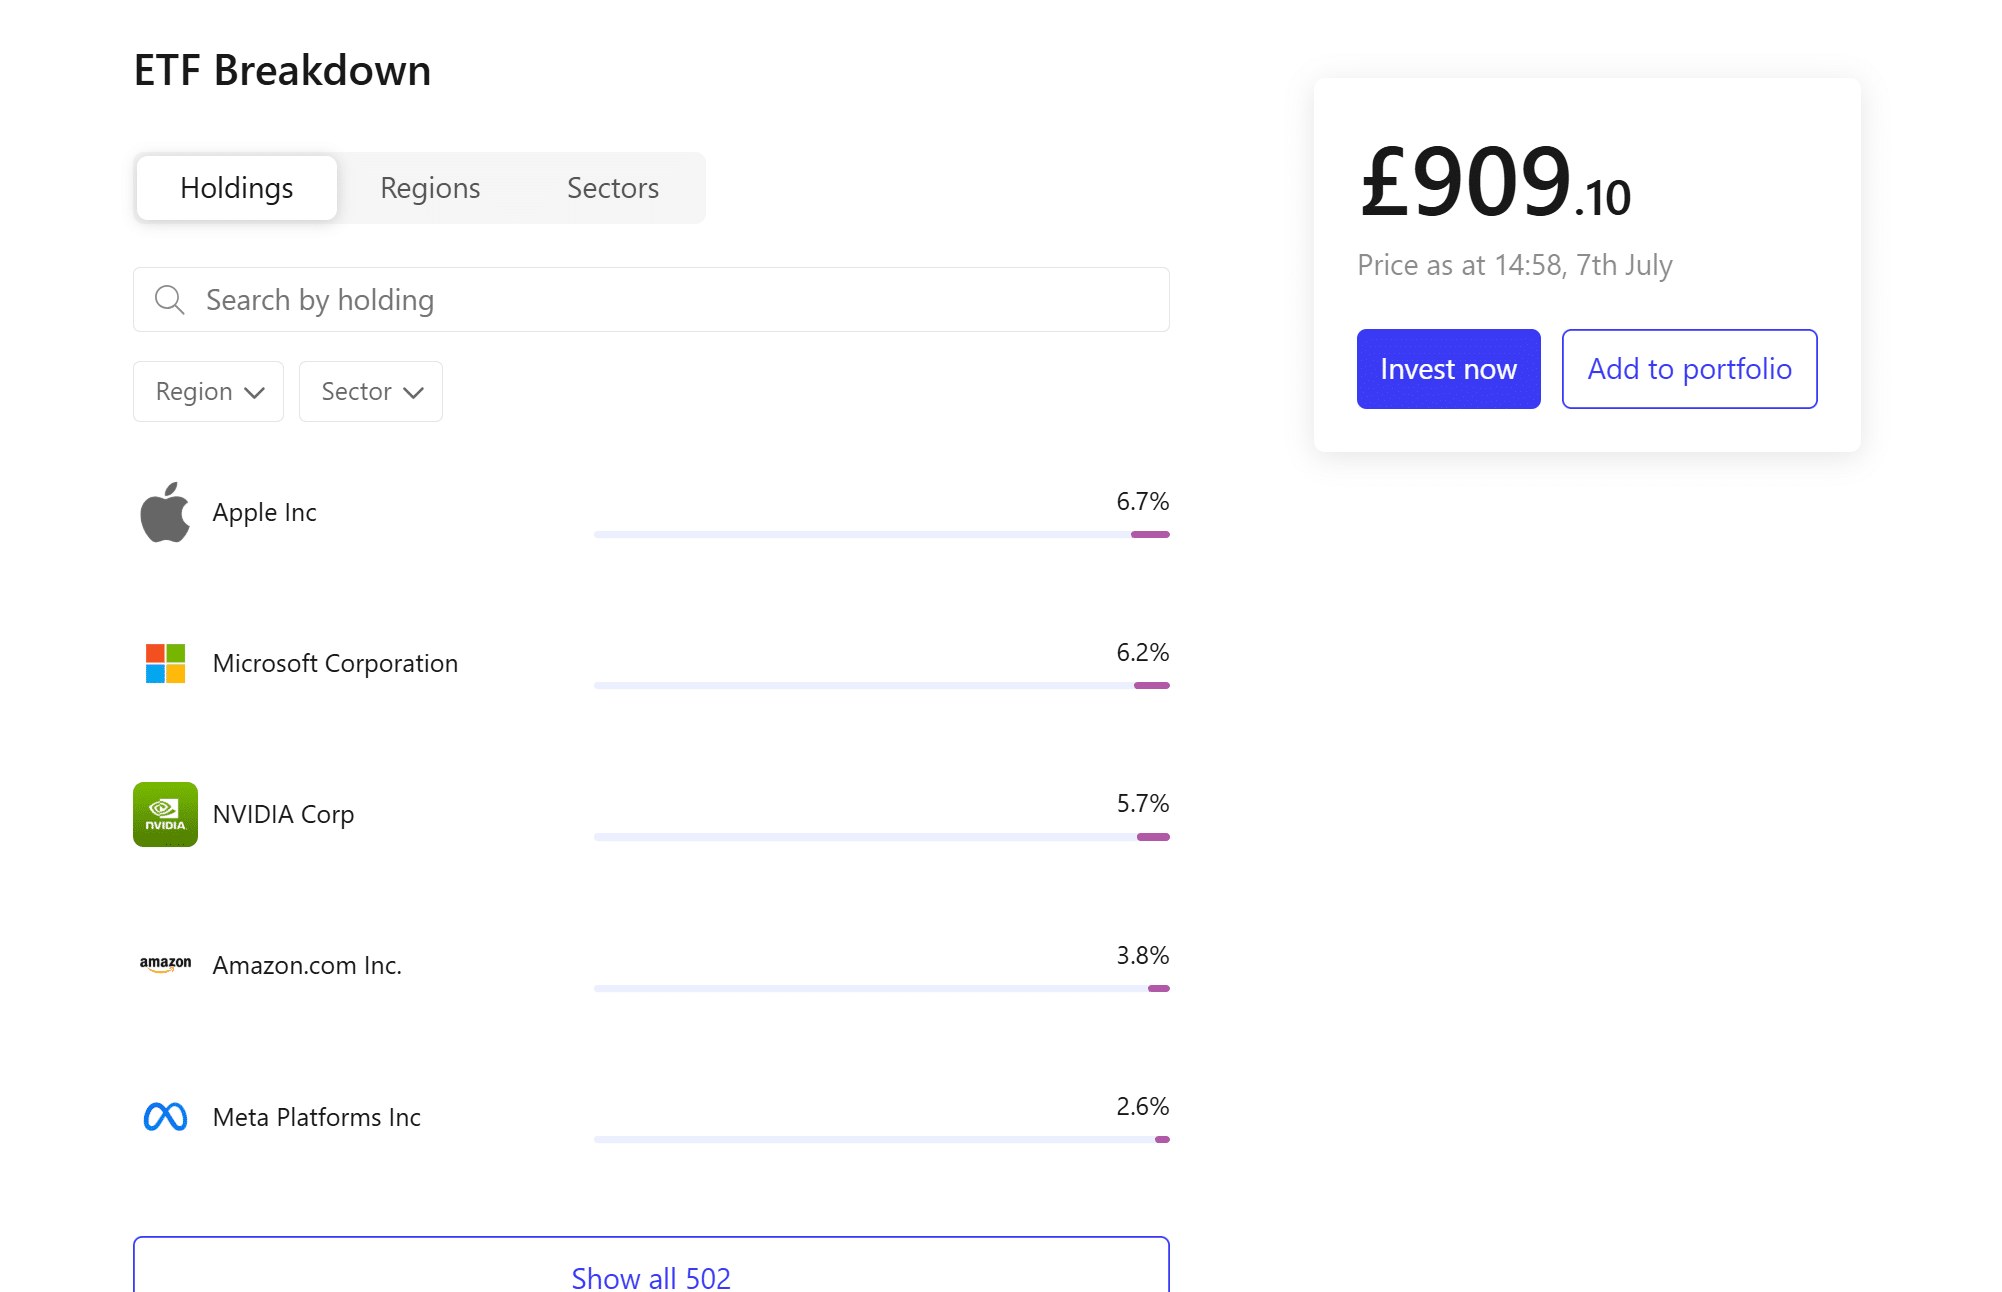
Additionally, you can set your investment weights to create the right balance for your investment goals.
If you don’t want the hassle of looking for ETFs and building a portfolio, InvestEngine offers what it calls “Managed Portfolios” and “LifePlans”. For a 0.25% annual fee, you get a pre-built portfolio.

The InvestEngine LifePlan Portfolios are adaptations of their managed portfolios. They come in five equity levels (20%, 40%, 60%, 80% and 100%), with risk levels from 3 to 5 out of 7, and InvestEngine recommends holding them for at least five years (InvestEngine). They are similar to the Vanguard LifeStrategy funds, but with less of a UK bias. They cost 0.25% a year (£2.50 per £1,000 invested), plus ETF costs, like any managed portfolio.

As an example, let’s analyse the LifePlan 60% equity:
- Description: a balanced portfolio, rated 4 out of 7 for risk, designed for long-term investors comfortable with medium risk.
- Objective: suited to those investing for at least five years, with an emergency fund in place and an understanding of ETF investing.
- Management style: actively managed by InvestEngine using passive ETFs, including both UK and international markets (including emerging markets).

Account types
InvestEngine offers four account types:

ISA
An Individual Savings Account is a tax-efficient wrapper. You can invest up to £20,000 a year across all your ISAs. There’s no income or capital gains tax to pay on any income or profits from your ISA investments. Tax treatment depends on individual circumstances and is subject to change.
With InvestEngine, you pay no ISA account fees (nor withdrawal or dealing fees).
SIPP
Short for “Self-Invested Personal Pension,” and it is a tax-efficient way to save for retirement. It allows individuals to manage their pension investments with flexibility, choosing from a wide range of assets. Contributions up to the annual limit get tax relief: the government adds 20% basic-rate relief, and higher and additional-rate taxpayers can claim more through their tax return. Tax treatment depends on individual circumstances and is subject to change.
InvestEngine charges no account fee on its SIPP, so you only pay the costs of your investments (and the 0.25% fee if you choose a managed portfolio). You can open one from £100.
General Investment Account
Unlike an ISA or SIPP, there is no annual limit on how much you can put in, but depending on your circumstances, you may be subject to tax on interest earned and capital gains.
Business account
Designed to let small and medium-sized enterprises (SMEs) invest surplus cash, with no platform fee. If you want to compare options, see our guide to the best business brokerage accounts.
In these account types, you can choose between a DIY or a Managed Portfolios approach.


Fees
DIY portfolios are free of InvestEngine commissions and platform fees, while Managed Portfolios and LifePlans have a 0.25% annual management fee, calculated daily and deducted monthly (InvestEngine costs). There are no set-up, account, ISA, SIPP, withdrawal, transfer or dealing fees, and currency conversion is free.
However, there are costs that are not set by InvestEngine (and that InvestEngine does not benefit from) which will still apply to your investments:
- ETF Total Expense Ratio (TER): each ETF charges an annual fee that covers the fund manager’s costs. On InvestEngine’s managed portfolios, the average ETF charge is 0.12% a year. ETF charges start from 0.03% a year (for example, the SPDR S&P 500 UCITS ETF, SPYL, at 0.03%, or the Amundi Prime All Country World UCITS ETF at 0.07%).
- Bid-ask spread: when buying or selling an ETF, you’ll notice a small difference between the buy (ask) price and the sell (bid) price. This difference is called the spread and is paid implicitly when you trade, not as a separate charge.
These costs are built into the ETF’s performance and InvestEngine does not earn anything from them. One cost to keep in mind: uninvested cash earns no interest for you, since InvestEngine keeps the interest paid by its banking partners.

Safety and reliability
InvestEngine is authorised and regulated by the Financial Conduct Authority (FCA), (FRN 801128), and eligible clients are protected up to £85,000 by the Financial Services Compensation Scheme (FSCS) if InvestEngine fails. The FSCS does not cover losses from falling markets.
As with most regulated investment platforms in the UK, the firm holds client cash in segregated pooled bank accounts at recognised banks, and client investments in a pooled client account at CREST (operated by Euroclear UK and Ireland), kept legally separate from InvestEngine’s own balance sheet and from any custodian’s assets. This segregation is a key consumer protection mechanism: it means that even if InvestEngine or any of its banking partners were to fail, your assets are identifiable as belonging to you (or, more precisely, to the pool of InvestEngine clients).
As is standard industry practice to reduce administrative complexity and operational costs, the legal registration of your investments is held under InvestEngine Nominees Limited (a “nominee” structure, InvestEngine). This does not change the fact that you remain the beneficial owner of your assets: the nominee has no legal claim to your investments and cannot use them to satisfy any InvestEngine obligations.
Customer support
InvestEngine’s customer support is available only by email ([email protected]) and through the contact form in its Help Centre, with no phone or live chat. Support runs from 5:30am to 11pm on weekdays and from 7am to 10pm at weekends, including public holidays (UK time) (InvestEngine Help Centre).
Supported countries
InvestEngine only accepts UK residents. To open an ISA or SIPP, you must also be a UK tax resident, and you must be at least 18 years old.
Bottom line
InvestEngine is one of the simplest and most intuitive investment platforms in the UK market. The platform focuses exclusively on ETFs, which are transparent, easy to understand and well suited to long-term passive investors.
InvestEngine understands that some investors value the autonomy of managing their own portfolios, while others prefer the convenience of a professionally managed solution. The platform serves both groups well through its DIY portfolios (zero platform fees) and LifePlans managed portfolios (0.25% annual fee).
The combination of a transparent fee structure, a good range of account types (ISA, SIPP, General Investment Account and Business Account), fractional investing from £1 and a selection of 870+ ETFs makes InvestEngine a competitive option in the UK. It deserves a place on your shortlist if you mainly invest in ETFs, especially in an ISA or SIPP, where its free DIY structure can save meaningful amounts over decades.
InvestEngine isn’t the right fit if you want individual stocks, mutual funds or individual bonds, or if you want interest on cash waiting to be invested. For those needs, a multi-asset broker is more appropriate.
